PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125315

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125315
Mechanical Seals - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the mechanical seals market size is expected to grow from USD 7.62 billion in 2025 to USD 7.97 billion in 2026 and is forecast to reach USD 9.97 billion by 2031 at a 4.58% CAGR over 2026-2031.
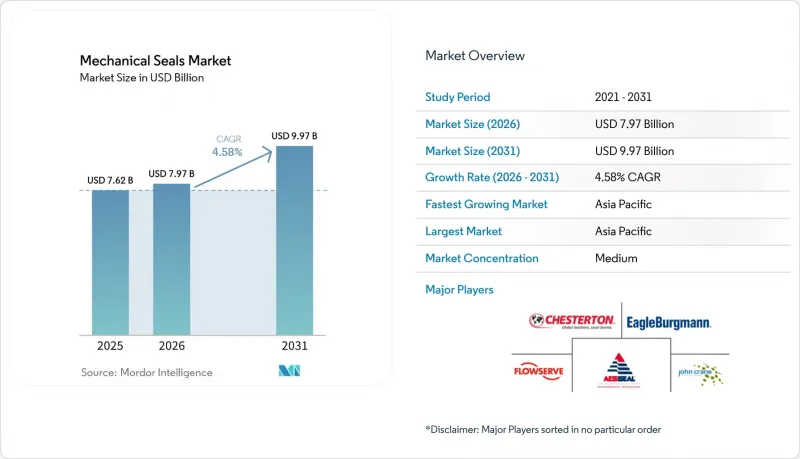
This report is Segmented by Seal Type (Pump Seals, Compressor Seals, and Mixer Seals), Design Type (Component/Pusher, Cartridge, and Split), End-User Industry (Oil and Gas, Power Generation, Chemical, Water and Waste-Water, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). Market Forecasts are Provided in Terms of Value (USD).
Global Mechanical Seals Market Trends and Insights
Growing Demand from Oil and Gas Megaprojects
Saudi Arabia's push into downstream operations highlights a shift in seal requirements driven by crude-to-chemicals integration. Aramco's Amiral complex, set to commence operations in 2027, will demand premium seals for its mixed-feed crackers and high-pressure hydrocarbon pumps. Suppliers are now tasked with providing materials resilient to extreme temperatures and corrosive petrochemical streams. John Crane's Type 8628VL non-contacting spiral-groove seal boasts an extended mean time between repairs while significantly reducing flush demand. Such large-scale projects lean towards upfront investments in advanced technology, promising lifecycle savings, and putting pressure on vendors still dependent on traditional wet-seal lines.
Surge in New Power-Generation Capacity Additions
Worldwide installations of gas turbines, nuclear reactors, and hybrid renewables are on the rise. Yet, the primary demand for seals is concentrated in auxiliary feed-water pumps, cooling circuits, and steam turbines. A retrofit of AESSEAL's STS steam turbine seal at a refinery in the UK resulted in significant steam savings annually per unit. This upgrade extended the turbine's lifespan, translating to impressive annual fleet savings. As grids increasingly incorporate intermittent renewables, combined-cycle turbines are set to cycle more frequently. This heightened activity accelerates seal wear, leading to a surge in aftermarket volumes. On the horizon, while modular nuclear concepts and closed-loop cooling might reduce the number of dynamic sealing points, tempering growth in the very long term, the immediate future looks robust.
High Life-Cycle Cost in Abrasive Slurry Services
Mining and pulp operators frequently opt for packed glands or expeller devices, shunning the premium on slurry seals. Their choice underscores a preference for inventory simplicity over longevity. Meanwhile, John Crane's SB2 dual-cartridge technology, which eliminates the need for an external flush and extends service life, sees its field adoption largely dependent on bundled technical support and performance guarantees. These assurances aim to counterbalance the initial investment. Vendors who solely push products without added services find themselves sidelined in abrasive tasks.
Other drivers and restraints analyzed in the detailed report include:
- Tightening Fugitive-Emission Regulations Worldwide
- Capacity Expansion in Chemical and Petrochemical Complexes
- Seal-Less Mag-Drive and Canned-Motor Pumps Eroding Addressable Market
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pump seals generated 64.35% revenue in 2025 and will track a 4.56% CAGR to 2031. Retrofits into existing centrifugal pumps underpin stable aftermarket sales, but the installed base is vulnerable to seal-less migration in clean chemical services. Non-contacting spiral-groove designs and upstream-pumping faces now headline innovation, allowing suppliers to frame upgrades around energy savings and emissions compliance. Compressor seals, though lower in volume, achieve higher average selling prices via technical complexity and rising regulatory enforcement. Mixer seals remain niche yet mission-critical in hygiene-sensitive reactors, sustaining premium margins.
While the mechanical seals market size for pump applications will expand steadily, competitive intensity is sharpening as Asian manufacturers offer low-cost contact-face cartridges. Established brands differentiate through digital diagnostics, performance warranties, and rapid local service.
Complete Report Scope:
- By Seal Type
- Pump Seals
- Compressor Seals
- Mixer Seals
- By Design Type
- Component/Pusher
- Cartridge
- Split
- By End-user Industry
- Oil and Gas
- Power Generation
- Chemical
- Water and Waste-water
- Other End-user Industries (Mining and Mineral Processing, Food, Pharma, etc.)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific captured 36.35% of the mechanical seals market revenue in 2025 and is projected to post the fastest 4.68% CAGR through 2031. China's expansions in refining, petrochemicals, and power sectors drive a significant demand. Additionally, China's leadership in electrolyser manufacturing has spurred an early adoption of hydrogen-ready seals. Following closely, India is ramping up its refinery and water infrastructure projects. However, due to price sensitivities, the standard pump business is leaning towards domestic producers. Meanwhile, Japan and South Korea, despite their smaller size, are investing in high-performance seals for LNG and semiconductor applications, carving out premium-margin niches.
North America commanded a notable market share in 2025. The EPA's methane regulations are driving retrofits of dry-gas seals throughout the Gulf Coast's midstream network. Capital orders are bolstered by LNG export terminals and petrochemical debottlenecks, while an aging installed base ensures stability in the aftermarket. In Canada, duties on oil sands are pushing the demand for abrasion-resistant dual seals, yet delays in pipeline projects introduce volatility in capital expenditures.
Europe represented a considerable portion of the market value. Projects focused on energy transition-like carbon capture, hydrogen electrolysers, and offshore wind-are fostering growth, though progress is often slowed by permitting delays. Germany and the UK are taking the lead in hydrogen pipelines, yet the bulk of revenues from 2026 to 2028 are anticipated to stem from upgrades in industrial gas and specialty chemicals. While the Middle East and Africa hold a smaller market share, they are involved in some of the industry's largest projects. Notable undertakings include Saudi Arabia's push from crude to chemicals, ADNOC's venture in carbon capture and storage, and South Africa's mining sector-all of which demand hundreds of seals per project. However, suppliers face challenges with longer logistics routes and extended receivables.
- A.W. Chesterton Company
- AESSEAL
- Dana Limited
- Eagle Industry Co., Ltd.
- EagleBurgmann
- Flexaseal Engineered Seals and Systems, LLC
- Flowserve Corporation
- Gallagher Seals
- Garlock
- Hutchinson Industries Inc.
- John Crane
- Parker Hannifin Corp
- SKF
- Technetics Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand from oil and gas megaprojects
- 4.2.2 Surge in new power-generation capacity additions
- 4.2.3 Tightening fugitive-emission regulations worldwide
- 4.2.4 Capacity expansion in chemical and petrochemical complexes
- 4.2.5 Hydrogen and green-ammonia cryogenic infrastructure build-out
- 4.3 Market Restraints
- 4.3.1 High life-cycle cost in abrasive slurry services
- 4.3.2 Seal-less mag-drive and canned-motor pumps eroding addressable market
- 4.3.3 SiC face-material price volatility and supply-chain risk
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Seal Type
- 5.1.1 Pump Seals
- 5.1.2 Compressor Seals
- 5.1.3 Mixer Seals
- 5.2 By Design Type
- 5.2.1 Component/Pusher
- 5.2.2 Cartridge
- 5.2.3 Split
- 5.3 By End-user Industry
- 5.3.1 Oil and Gas
- 5.3.2 Power Generation
- 5.3.3 Chemical
- 5.3.4 Water and Waste-water
- 5.3.5 Other End-user Industries (Mining and Mineral Processing, Food, Pharma, etc.)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 A.W. Chesterton Company
- 6.4.2 AESSEAL
- 6.4.3 Dana Limited
- 6.4.4 Eagle Industry Co., Ltd.
- 6.4.5 EagleBurgmann
- 6.4.6 Flexaseal Engineered Seals and Systems, LLC
- 6.4.7 Flowserve Corporation
- 6.4.8 Gallagher Seals
- 6.4.9 Garlock
- 6.4.10 Hutchinson Industries Inc.
- 6.4.11 John Crane
- 6.4.12 Parker Hannifin Corp
- 6.4.13 SKF
- 6.4.14 Technetics Group
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

