PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125363

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125363
Online Simulation Games - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the online simulation games market size in 2026 is estimated at USD 10.53 billion, growing from 2025 value of USD 9.31 billion with 2031 projections showing USD 19.47 billion, growing at 13.09% CAGR over 2026-2031.
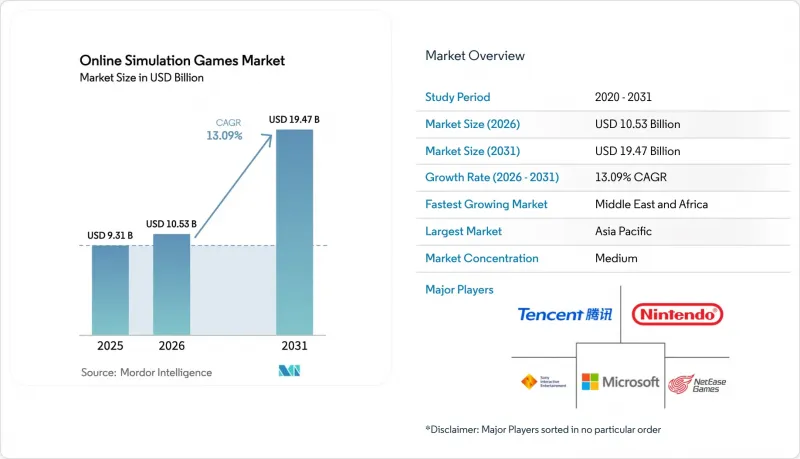
This report is Segmented by Revenue Model (Advertising, In-App Purchase, Subscription, and Paid App), Platform (Mobile, PC, Console, and VR/AR Device), Game Type (Life Simulation, Vehicle Simulation, Construction and Management Simulation, Sports Simulation, and Training and Education Simulation), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Online Simulation Games Market Trends and Insights
Rise in Mobile-First Gaming Uptake across Emerging Asian Markets
Mobile downloads touched 4.2 billion in Southeast Asia during H1 2024, with Indonesia alone contributing 41%. Spending willingness now exceeds 60% across Indonesia, Malaysia, and Thailand, motivating publishers to localize content and lean on culturally resonant food- and sports-themed simulations. Expanding 5G coverage is unlocking complex physics previously limited to PCs, reinforcing the online simulation games market's mobile dominance in the region. Studios exploiting these conditions gain rapid scale without high upfront console or PC marketing costs.
Growth of Cloud Gaming Infrastructure Enabling Low-Latency Simulations in North America
Edge-based architectures such as AccelByte's Multiplayer Servers integrated with Microsoft Azure now offer diverse virtual-machine families tuned for simulation workloads. CableLabs' Low Latency DOCSIS further trims lag, letting bandwidth-heavy flight or city-building simulations run flawlessly over ordinary connections. By abstracting performance away from end-user hardware, developers unlock new regions where high-spec GPUs remain scarce, broadening the online simulation games market addressable base.
High GPU demand outpacing supply, inflating hardware costs for PC simulations
Nvidia's 86% share in discrete gaming GPUs gives shortages direct influence on retail prices. Consumers postpone upgrades, shrinking the premium PC slice of the online simulation games market size. Developers downscale texture packs or add cloud-rendered modes that shift compute to data centers. While streaming bridges the gap, it diverts spending toward platform fees and leaves razor-thin margins for titles reliant on fixed hardware sales.
Other drivers and restraints analyzed in the detailed report include:
- Integration of Generative AI for Real-Time World-Building Boosting Player Engagement
- Expansion of esports broadcasting rights for simulation titles in Europe
- Stringent loot-box regulations in Europe curtailing monetization options
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In-app purchases delivered 54.35% of 2025 revenue, reflecting their low entry barrier and impulse-driven psychology. The online simulation games market size for subscriptions is forecast to expand at a 15.55% CAGR from 2026-2031 as studios value predictable cash flow. Loot-box regulation accelerates that migration, and hybrid structures emerge where optional microtransactions supplement monthly passes. Advertising spend in simulation titles increased 26.7% year over year, fueled by rewarded-video formats that maintain engagement without paywalls. Paid download models persist among niche aircraft or industrial simulators that serve professional communities willing to invest upfront.
Higher annual retention correlates with subscription bundles that include exclusive expansion packs and cross-platform cloud saves. Loyalty metrics demonstrate that users enrolled longer than twelve months average 42% more playtime, evidence that predictable updates secure mindshare. As telecom operators bundle game subscriptions into data plans, the online simulation games market broadens into demographics previously price sensitive.
Complete Report Scope:
- By Revenue Model
- Advertising
- In-App Purchase
- Subscription
- Paid App
- By Platform
- Mobile
- PC
- Console
- VR/AR Devices
- By Game Type
- Life Simulation
- Vehicle Simulation
- Construction and Management Simulation
- Sports Simulation
- Training and Education Simulation
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Peru
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific contributes the largest slice of the online simulation games market, holding 44.70% of 2025 revenue. China, Japan, and South Korea supply high-ARPU users, while Indonesia, Thailand, and Malaysia drive install volumes after mobile downloads reached 4.2 billion in early 2024. Local publishers adopt language packs and culturally themed assets to extend average session length and in-app purchase depth.
The Middle East & Africa region charts the fastest trajectory with an expected 17.62% CAGR to 2031, propelled by sovereign investment funds allocating capital to gaming accelerators and esports arenas. The National Gaming & Esports Strategy in Saudi Arabia outlines job-creation and studio-incubation targets that integrate simulation IP into tourism and education initiatives. Infrastructure rollouts of fiber and 5G networks shrink latency, aligning region-wide with global competitive standards for online titles.
North America maintains technical leadership in cloud delivery and AI tooling, recording USD 2 billion in mobile simulation revenue in April 2025. Europe sets monetization norms, with consumer-protection directives influencing global design choices. South America leverages Brazil's Law 14.852 to grant gaming cultural status, fostering public grants and tax incentives for developers. Rural bandwidth gaps persist, so studios embed offline progression to ensure accessibility, keeping growth steady across diverse economic tiers in the online simulation games market.
- Sony Interactive Entertainment Inc.
- Tencent Holdings Ltd.
- Nintendo Co., Ltd.
- Microsoft Corporation (Xbox Game Studios)
- NetEase, Inc.
- Activision Blizzard, Inc.
- Electronic Arts Inc.
- Take-Two Interactive Software, Inc.
- Bandai Namco Entertainment Inc.
- Square Enix Holdings Co., Ltd.
- Ubisoft Entertainment SA
- Sega Sammy Holdings Inc.
- Paradox Interactive AB
- Frontier Developments plc
- KRAFTON, Inc.
- Roblox Corporation
- Paradox Interactive AB
- Frontier Developments plc
- Wargaming Group Limited
- Colossal Order
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rise in Mobile-First Gaming Uptake across Emerging Asian Markets
- 4.2.2 Growth of Cloud Gaming Infrastructure Enabling Low-Latency Simulations in North America
- 4.2.3 Integration of Generative AI for Real-Time World-Building Boosting Player Engagement
- 4.2.4 Expansion of Esports Broadcasting Rights for Simulation Titles in Europe
- 4.2.5 Government-Backed Digital Economy Initiatives Fueling Indie Simulation Studios in South America
- 4.2.6 Increasing Adoption of VR Flight and Driving Simulators for Training in the Middle East
- 4.3 Market Restraints
- 4.3.1 High GPU Demand Outpacing Supply, Inflating Hardware Costs for PC Simulations
- 4.3.2 Stringent Loot-Box Regulations in Europe Curtailing Monetization Options
- 4.3.3 Bandwidth Limitations in Rural Africa Hindering Real-Time Multiplayer Experiences
- 4.3.4 Rising Development Costs for Photorealistic Physics Engines
- 4.4 Technological Outlook
- 4.5 Macroeconomic Impact Assessment
- 4.6 Investment Analysis
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Revenue Model
- 5.1.1 Advertising
- 5.1.2 In-App Purchase
- 5.1.3 Subscription
- 5.1.4 Paid App
- 5.2 By Platform
- 5.2.1 Mobile
- 5.2.2 PC
- 5.2.3 Console
- 5.2.4 VR/AR Devices
- 5.3 By Game Type
- 5.3.1 Life Simulation
- 5.3.2 Vehicle Simulation
- 5.3.3 Construction and Management Simulation
- 5.3.4 Sports Simulation
- 5.3.5 Training and Education Simulation
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Chile
- 5.4.2.4 Peru
- 5.4.2.5 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 South Korea
- 5.4.4.4 India
- 5.4.4.5 Australia
- 5.4.4.6 New Zealand
- 5.4.4.7 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 United Arab Emirates
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 Turkey
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Rest of Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Strategic Developments
- 6.2 Vendor Positioning Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.3.1 Sony Interactive Entertainment Inc.
- 6.3.2 Tencent Holdings Ltd.
- 6.3.3 Nintendo Co., Ltd.
- 6.3.4 Microsoft Corporation (Xbox Game Studios)
- 6.3.5 NetEase, Inc.
- 6.3.6 Activision Blizzard, Inc.
- 6.3.7 Electronic Arts Inc.
- 6.3.8 Take-Two Interactive Software, Inc.
- 6.3.9 Bandai Namco Entertainment Inc.
- 6.3.10 Square Enix Holdings Co., Ltd.
- 6.3.11 Ubisoft Entertainment SA
- 6.3.12 Sega Sammy Holdings Inc.
- 6.3.13 Paradox Interactive AB
- 6.3.14 Frontier Developments plc
- 6.3.15 KRAFTON, Inc.
- 6.3.16 Roblox Corporation
- 6.3.17 Paradox Interactive AB
- 6.3.18 Frontier Developments plc
- 6.3.19 Wargaming Group Limited
- 6.3.20 Colossal Order
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

