PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125478

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125478
Rotator Cuff Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the rotator cuff treatment market size is expected to grow from USD 760.78 million in 2025 to USD 790.30 million in 2026 and is forecast to reach USD 996.79 million by 2031 at 4.75% CAGR over 2026-2031.
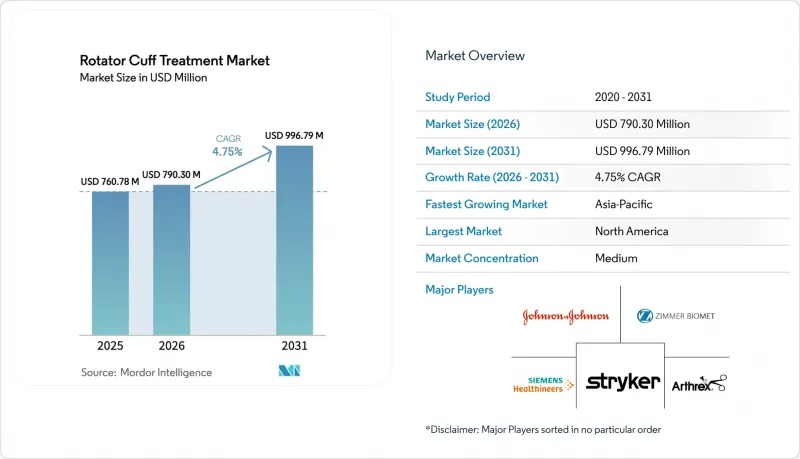
This report is Segmented by Treatment Type (Surgical [Arthroscopic Repair and More], and More), Product Type (Implants, Instruments, and More), Patient Age (Less Than 50, and More), Indication (Sports, and More), Injury Severity (Partial, and More), End User (Hospitals, and More), and Geography (North America, and More). Market Forecasts are Provided in Value (USD).
Global Rotator Cuff Treatment Market Trends and Insights
Rising Incidence of Sports & Work-Related Shoulder Injuries
Participation in overhead sports and manual-labor occupations is elevating rotator cuff injury rates among working-age adults, reversing the perception that tears are confined to older cohorts. The U.S. Bureau of Labor Statistics logged 142,000 shoulder-related workers'-comp claims in 2024, a 9% jump from 2023, with construction, warehousing, and healthcare accounting for 61% of cases. Recreational athletes aged 35-50 are presenting with partial-thickness tears 23% more frequently than a decade ago, driven by CrossFit, pickleball, and obstacle-course racing. Early surgical intervention preserves productivity and athletic performance, compressing the diagnostic-to-repair timeline and enlarging the pool of candidates for minimally invasive repair. Employer prevention efforts lag the pace of injuries, ensuring sustained procedure volumes despite declining per-case reimbursement.
Aging Population Driving Degenerative Tears
Global aging is the most durable structural tailwind. Individuals over 65 already represent 44.84% of procedures, and United Nations projections show that cohort doubling to 1.6 billion by 2050. Degenerative tears often progress silently until weakness forces clinical evaluation, generating a backlog of latent cases poised to convert as imaging access broadens. Japan reported a 12% rise in shoulder arthroscopies in patients over 70 during 2025, an outcome of expanded outpatient coverage and seniors' desire to maintain independence. Reverse shoulder arthroplasty has become the default salvage option for massive irreparable tears, overtaking hemiarthroplasty due to superior functional scores.
High Cost of Advanced Implants & Biologics
Acellular dermal matrices cost USD 2,500-4,500, while PRP kits add USD 800-1,200 per case, outstripping the USD 850 Medicare add-on, particularly in price-sensitive markets. Chinese and Indian patients, who pay 40-60% of orthopedic bills out of pocket, often delay surgery or choose suture-only options. U.S. value-based contracts intensify scrutiny; 68% of surgeons report pressure to justify biologic use with outcomes data.
Other drivers and restraints analyzed in the detailed report include:
- Technological Advances in Minimally Invasive & Robotic Surgery
- Growing Adoption of Orthobiologics & Regenerative Therapies
- Re-Tear Risk and Variable Surgical Outcomes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Orthobiologics are expanding at an 8.36% CAGR through 2031. Surgical repairs still represented 61.53% of 2025 revenue, yet the rotator cuff treatment market size tied to platelet-rich plasma, stem-cell scaffolds, and acellular dermal matrices is rising steadily. Surgeons now integrate biologic augmentation into repairs of large and massive tears to lower re-tear risk, compressing anchor-only margins and spurring incumbent vendors to diversify into tissue engineering. Physiotherapy and palliative regimens remain first-line for partial tears and low-demand elders, while repeated corticosteroid injections face curbs due to documented tendon degeneration and elevated failure rates.
Biologic adoption coexists with a robust pipeline of stemless reverse arthroplasty implants aimed at massive irreparable pathology. The American Shoulder and Elbow Surgeons registry cites a 19% annual increase in reverse procedures across 2024-2025. Preventive programs and eccentric strengthening slow early degeneration but rarely avert surgery once functional decline sets in. Consequently, the rotator cuff treatment market maintains a dual trajectory: elective arthroscopy fortified by biologics for reparable tears and arthroplasty for salvage cases.
Biologic patches and meshes are advancing at a 9.24% CAGR, the fastest product category pace. In contrast, implants and fixation devices commanded 39.46% of 2025 revenue but are maturing as bundled-payment pressures curb anchor counts. Knotless systems fetch USD 450-650 each-higher than conventional anchors-yet ASCs absorb the premium in exchange for quicker OR turnover. Imaging and navigation platforms, such as Stryker's 2024 augmented-reality arthroscopy suite, reduce anchor misplacement by 22% and support premium pricing.
The American Academy of Orthopaedic Surgeons downgraded corticosteroid injections for surgical candidates in 2025. This guidance shrinks the drugs subsegment and redirects capital toward regenerative scaffolds. Minimal-processing allografts retain 68% of native growth factors versus 12% for heavily cross-linked alternatives, accelerating tendon integration. As payers demand outcome data, vendors emphasize biomechanical strength and healing profiles to justify premium price points.
Complete Report Scope:
- By Treatment Type
- Surgical / Curative Treatment
- Arthroscopic Repair
- Open Repair
- Mini-open Repair
- Shoulder Arthroplasty
- Reverse Shoulder Arthroplasty
- Stemless Shoulder Arthroplasty
- Physiotherapy / Palliative Treatment
- Preventive / Conservative Management
- Orthobiologics
- PRP & Growth-Factor Therapy
- Stem-cell Therapy
- Biological Meshes & Patches
- Pharmaceutical Treatment
- NSAIDs
- Corticosteroid Injections
- Surgical / Curative Treatment
- By Product Type
- Implants & Fixation Devices
- Suture Anchors
- Knot-less Fixation Systems
- Biologic Patches & Meshes
- Tendon Grafts & Scaffolds
- Surgical Instruments & Power Systems
- Rehabilitation Equipment
- Physical-Therapy Devices
- Braces & Supports
- Imaging & Navigation Systems
- Drugs
- Others
- Implants & Fixation Devices
- By Patient Age Group
- < 50 Years
- 50 - 64 Years
- >= 65 Years
- By Indication
- Sports-Related Injuries
- Age-Related Degeneration
- Traumatic Injuries
- By Injury Severity
- Partial-Thickness Tears
- Full-Thickness Tears
- Massive / Irreparable Tears
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Orthopedic Clinics & Physician Offices
- Home-Care Settings
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 39.54% of 2025 revenue, anchored by roughly 450,000 annual cuff repairs and payer policies that reward outpatient biologic-augmented arthroscopy. Canada's single-payer constraints prolong waitlists, but cross-border travel to U.S. centers and rising supplemental insurance temper leakage. Mexican providers lure U.S. self-pay patients with 40-60% lower package prices, yet inconsistent follow-up deters broad adoption.
Asia-Pacific is the fastest-growing region at a 6.22% CAGR. China logged a 17% rise in shoulder arthroscopies in 2025. Indian surgeons cite device cost as the top barrier, spurring domestic anchor systems priced at USD 80-120. Japan's stringent PMDA reviews delay high-tech launches 18-24 months, favoring entrenched suppliers. South Korea and Thailand capture medical-tourism flows, with Bangkok's Bumrungrad Hospital posting a 22% rise in shoulder cases from Middle Eastern and Australian patients in 2024.
Europe faces MDR friction that stretches CE marking for novel biologics by up to 18 months. Germany, France, and the United Kingdom account for 55% of regional revenue. NHS waitlists topping 12-18 months catalyzed a 19% uptick in private shoulder procedures in 2024. Southern Europe lags on per-capita volume but leverages medical tourism to mitigate domestic shortfalls. GCC countries lead Middle East adoption thanks to high incomes and Western-trained surgeons, whereas South America remains hampered by macroeconomic volatility despite niche growth in Brazil and Argentina.
- 3S Ortho
- Aevumed
- Anika Therapeutics
- Arthrex
- Atreon Orthopedics
- Bioventus
- Conmed
- DJO Global
- Embody Inc.
- Exactech
- FH ORTHOPEDICS
- Integra LifeSciences
- Johnson & Johnson
- Karl Storz
- LimaCorporate
- Organogenesis
- Ossio
- Parcus Medical
- Shoulder Innovations
- Smiths Group
- Stryker
- Via Surgical
- Xiros Ltd.
- Zimmer Biomet
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Incidence of Sports & Work-Related Shoulder Injuries
- 4.2.2 Aging Population Driving Degenerative Tears
- 4.2.3 Technological Advances in Minimally Invasive & Robotic Surgery
- 4.2.4 Growing Adoption of Ortho biologics & Regenerative Therapies
- 4.2.5 Ambulatory-Surgery-Center Shift Boosting Procedure Volumes
- 4.2.6 Reimbursement Updates Favoring Outpatient Cuff Repairs
- 4.3 Market Restraints
- 4.3.1 High Cost of Advanced Implants & Biologics
- 4.3.2 Re-Tear Risk and Variable Surgical Outcomes
- 4.3.3 Strict EU-MDR / FDA Pathways for Novel Biologics
- 4.3.4 Surgeon-Skill Gaps in Emerging Markets
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Treatment Type
- 5.1.1 Surgical / Curative Treatment
- 5.1.1.1 Arthroscopic Repair
- 5.1.1.2 Open Repair
- 5.1.1.3 Mini-open Repair
- 5.1.1.4 Shoulder Arthroplasty
- 5.1.1.4.1 Reverse Shoulder Arthroplasty
- 5.1.1.4.2 Stemless Shoulder Arthroplasty
- 5.1.2 Physiotherapy / Palliative Treatment
- 5.1.3 Preventive / Conservative Management
- 5.1.4 Orthobiologics
- 5.1.4.1 PRP & Growth-Factor Therapy
- 5.1.4.2 Stem-cell Therapy
- 5.1.4.3 Biological Meshes & Patches
- 5.1.5 Pharmaceutical Treatment
- 5.1.5.1 NSAIDs
- 5.1.5.2 Corticosteroid Injections
- 5.1.1 Surgical / Curative Treatment
- 5.2 By Product Type
- 5.2.1 Implants & Fixation Devices
- 5.2.1.1 Suture Anchors
- 5.2.1.2 Knot-less Fixation Systems
- 5.2.1.3 Biologic Patches & Meshes
- 5.2.1.4 Tendon Grafts & Scaffolds
- 5.2.2 Surgical Instruments & Power Systems
- 5.2.3 Rehabilitation Equipment
- 5.2.3.1 Physical-Therapy Devices
- 5.2.3.2 Braces & Supports
- 5.2.4 Imaging & Navigation Systems
- 5.2.5 Drugs
- 5.2.6 Others
- 5.2.1 Implants & Fixation Devices
- 5.3 By Patient Age Group
- 5.3.1 < 50 Years
- 5.3.2 50 - 64 Years
- 5.3.3 >= 65 Years
- 5.4 By Indication
- 5.4.1 Sports-Related Injuries
- 5.4.2 Age-Related Degeneration
- 5.4.3 Traumatic Injuries
- 5.5 By Injury Severity
- 5.5.1 Partial-Thickness Tears
- 5.5.2 Full-Thickness Tears
- 5.5.3 Massive / Irreparable Tears
- 5.6 By End User
- 5.6.1 Hospitals
- 5.6.2 Ambulatory Surgical Centers
- 5.6.3 Orthopedic Clinics & Physician Offices
- 5.6.4 Home-Care Settings
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 France
- 5.7.2.3 United Kingdom
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 South Korea
- 5.7.3.5 Australia
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East & Africa
- 5.7.4.1 GCC
- 5.7.4.2 South Africa
- 5.7.4.3 Rest of Middle East & Africa
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 3S Ortho
- 6.3.2 Aevumed
- 6.3.3 Anika Therapeutics
- 6.3.4 Arthrex
- 6.3.5 Atreon Orthopedics
- 6.3.6 Bioventus
- 6.3.7 CONMED Corporation
- 6.3.8 DJO Global
- 6.3.9 Embody Inc.
- 6.3.10 Exactech
- 6.3.11 FH ORTHOPEDICS
- 6.3.12 Integra LifeSciences
- 6.3.13 Johnson & Johnson (DePuy Synthes)
- 6.3.14 Karl Storz
- 6.3.15 LimaCorporate
- 6.3.16 Organogenesis
- 6.3.17 Ossio
- 6.3.18 Parcus Medical
- 6.3.19 Shoulder Innovations
- 6.3.20 Smith & Nephew
- 6.3.21 Stryker Corporation
- 6.3.22 Via Surgical
- 6.3.23 Xiros Ltd.
- 6.3.24 Zimmer Biomet
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

