PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125485

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125485
Acute Respiratory Distress Syndrome Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the acute respiratory distress syndrome treatment market size is expected to grow from USD 3.26 billion in 2025 to USD 3.46 billion in 2026 and is forecast to reach USD 4.7 billion by 2031 at 6.28% CAGR over 2026-2031.
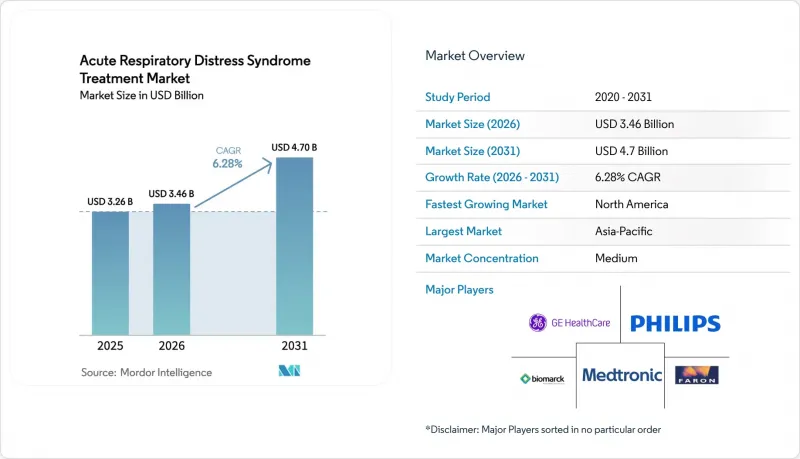
This report is Segmented by Treatment Modality (Medication/Drug Class, Medical Devices), Cause of Lung Injury (Direct Injury, Indirect Injury), Severity (Mild, Moderate, Severe), End User (Hospitals & Intensive Care Units, Specialty Clinics, Other End Users), and Geography (North America, Europe, Asia Pacific and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Acute Respiratory Distress Syndrome Treatment Market Trends and Insights
Rising Global Incidence of Sepsis and Pneumonia as Leading Etiologies of ARDS
Sepsis affects 1.7 million adults in the United States each year and drives about 40% of acute respiratory distress syndrome cases. Ventilator associated pneumonia develops in up to 30% of ventilated patients, lengthening ICU stay by up to nine days and adding USD 24,410 in costs per person. AI powered early warning models can now predict sepsis events six hours before clinical signs appear, shifting care from reactive to preventive. These factors together enlarge the acute respiratory distress syndrome treatment market as hospitals invest in rapid diagnostics and advanced ventilation systems.
High Prevalence of Tobacco Smoking Urbanization and Growing Levels of Pollution
Fine particulate matter exposure contributed to 8.79 million premature deaths worldwide in 2024, many of which progressed to ARDS. Industrial hubs in China experience overlapping risks from urban pollution and high smoking rates, prompting the state to add respiratory-focused ICU beds in tier-2 and tier-3 cities. This environmental driver operates on extended timelines, as population exposure effects accumulate over decades, but the treatment market responds immediately as healthcare systems adapt to higher baseline respiratory morbidity rates across affected regions.
High Cost Burden of Prolonged ICU Stays and Advanced Respiratory Devices
The economic burden of ARDS treatment creates significant market access barriers, with average ICU costs reaching USD 25,927 per bed per day and total treatment expenses for VAP patients averaging USD 544,467 compared to USD 207,416 for non-VAP patients. Capital outlays for extracorporeal systems and specialized staff raise entry barriers in developing regions. Outcome-based reimbursement covers only one in five advanced therapy products in Europe, slowing adoption and tempering the growth of the acute respiratory distress syndrome treatment market.
Other drivers and restraints analyzed in the detailed report include:
- Advancements in Early Diagnosis via Point-of-Care Ultrasound and Biomarker Panels
- Expanding Clinical Pipeline of Immunomodulators and Regenerative Therapies
- Risk of Ventilator Associated Complications and Nosocomial Infections
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Medical devices record the fastest 6.62% CAGR even though medication retains 56.62% of the acute respiratory distress syndrome treatment market share. AI ventilators like the Hamilton C6 optimize tidal volume in real time, while Medtronic VitalFlow ECMO advances portable extracorporeal support. Surfactant formulations and inhaled nitric oxide devices complement drug regimens, illustrating convergence that diversifies the acute respiratory distress syndrome treatment market size.
Applications of vasoconstrictors, corticosteroids, and antibiotics remain essential, yet device-centric strategies lower sedative need. Synthetic surfactants resistant to phospholipase degradation progress through trials and may capture a future share of the acute respiratory distress syndrome treatment market. The convergence of pharmaceutical and device technologies creates integrated treatment platforms that optimize therapeutic outcomes while reducing complications associated with prolonged mechanical ventilation and ICU stays.
Direct injury situations such as pneumonia and aspiration captured 61.75% revenue in 2025, while indirect mechanisms including sepsis are forecast to register 6.83% CAGR. Sepsis driven cytokine storms create systemic inflammation that necessitates immunomodulators, widening opportunities within the acute respiratory distress syndrome treatment market. The distinction between direct and indirect injury mechanisms influences therapeutic selection, as direct injury often responds better to surfactant replacement therapy, while indirect injury may benefit more from immunomodulatory interventions targeting systemic inflammation.
Pancreatitis, burns, and general trauma represent additional indirect injury mechanisms that contribute to ARDS development through complex inflammatory cascades involving complement activation, neutrophil recruitment, and cytokine release. The growing understanding of these pathways drives pharmaceutical development toward targeted therapies that interrupt specific inflammatory mediators rather than broad-spectrum approaches. Biomarker guided protocols help clinicians tailor therapy to injury type, improving efficacy and reducing ventilation days, which lifts overall acute respiratory distress syndrome treatment market size.
Complete Report Scope:
- By Treatment Modality
- Medication/Drug Class
- Vasoconstrictors
- Bronchodilators
- Corticosteroids & Antibiotics
- Sedatives & Paralytics
- Surfactants
- Other Pharmacologics
- Medical Devices
- Mechanical Ventilators
- ECMO & Artificial Lung Systems
- Inhaled Nitric Oxide Delivery Systems
- Diagnostic & Monitoring Devices
- Other Devices
- Medication/Drug Class
- By Cause of Lung Injury
- Direct Injury
- Indirect Injury
- By Severity
- Mild
- Moderate
- Severe
- By End User
- Hospitals & Intensive Care Units
- Specialty Clinics
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America leads with 39.10% market share supported by extensive ICU infrastructure, reimbursement pathways, and over 900 active gene therapy trials. United States hospitals deploy AI predictive modules that reduce ICU delirium and streamline staffing. Canada and Mexico modernize critical care services through cross border research and device sourcing, which expands regional acute respiratory distress syndrome treatment market size.
Asia Pacific is the fastest growing zone with 8.44% CAGR as China channels large scale pollution-related morbidity into policy backed ICU expansion. Japan emphasizes mortality reduction via advanced monitoring that fosters early intervention benefits, while India balances cost and reach through scalable high flow systems. Collective momentum positions the region to claim larger slices of the acute respiratory distress syndrome treatment market.
Europe maintains steady gains through regulatory harmonization under the Advanced Therapy Medical Products framework. Reimbursement remains tight with only one fifth of approved advanced therapies receiving public funding, yet joint accreditation strengthens quality standards that support cross border patient access. Middle East and Africa plus South America remain emerging but strategic initiatives to raise critical care capacity and adopt AI monitoring promise gradual inclusion in the global acute respiratory distress syndrome treatment market.
- Faron Pharmaceuticals
- BioMarck Pharmaceuticals
- GE Healthcare
- Hamilton Medical
- Medtronic
- Koninklijke Philips
- Fisher & Paykel Healthcare
- Dragerwerk
- Athersys
- ALung Technologies Inc. (LivaNova)
- VERO Biotech
- Mesoblast Ltd.
- Gilead Sciences
- Windtree Therapeutics
- Aqualung Therapeutics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global Incidence of Sepsis and Pneumonia as Leading Etiologies of ARDS
- 4.2.2 High Prevalence of Tobacco Smoking, Urbanization, And Growing Levels of Pollution
- 4.2.3 Advancements in Early Diagnosis via Point-of-Care Ultrasound & Biomarker Panels
- 4.2.4 Expanding Clinical Pipeline of Immunomodulators and Regenerative Therapies
- 4.2.5 Healthcare Digitization Enabling Real-Time ICU Data Analytics for Optimized ARDS Management
- 4.2.6 Increased Healthcare Spending and Strategic Partnerships and M&A Activities
- 4.3 Market Restraints
- 4.3.1 High Cost Burden of Prolonged ICU Stays and Advanced Respiratory Devices
- 4.3.2 Risk of Ventilator-Associated Complications and Nosocomial Infections
- 4.3.3 Stringent Regulatory and Ethical Hurdles for Cell-Based & Gene Therapies
- 4.3.4 Lack of Standardized Treatment Protocols and Complex Pathophysiology & Diagnosis
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Treatment Modality
- 5.1.1 Medication/Drug Class
- 5.1.1.1 Vasoconstrictors
- 5.1.1.2 Bronchodilators
- 5.1.1.3 Corticosteroids & Antibiotics
- 5.1.1.4 Sedatives & Paralytics
- 5.1.1.5 Surfactants
- 5.1.1.6 Other Pharmacologics
- 5.1.2 Medical Devices
- 5.1.2.1 Mechanical Ventilators
- 5.1.2.2 ECMO & Artificial Lung Systems
- 5.1.2.3 Inhaled Nitric Oxide Delivery Systems
- 5.1.2.4 Diagnostic & Monitoring Devices
- 5.1.2.5 Other Devices
- 5.1.1 Medication/Drug Class
- 5.2 By Cause of Lung Injury
- 5.2.1 Direct Injury
- 5.2.2 Indirect Injury
- 5.3 By Severity
- 5.3.1 Mild
- 5.3.2 Moderate
- 5.3.3 Severe
- 5.4 By End User
- 5.4.1 Hospitals & Intensive Care Units
- 5.4.2 Specialty Clinics
- 5.4.3 Other End Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Faron Pharmaceuticals
- 6.3.2 BioMarck Pharmaceuticals
- 6.3.3 GE Healthcare
- 6.3.4 Hamilton Medical
- 6.3.5 Medtronic plc
- 6.3.6 Philips Healthcare
- 6.3.7 Fisher & Paykel Healthcare Ltd.
- 6.3.8 Dragerwerk AG & Co. KGaA
- 6.3.9 Athersys Inc.
- 6.3.10 ALung Technologies Inc. (LivaNova)
- 6.3.11 VERO Biotech
- 6.3.12 Mesoblast Ltd.
- 6.3.13 Gilead Sciences Inc.
- 6.3.14 Windtree Therapeutics
- 6.3.15 Aqualung Therapeutics
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

