PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125583

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125583
Aluminium Forging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, aluminium forging market size in 2026 is estimated at USD 14.98 billion, growing from 2025 value of USD 14.25 billion with 2031 projections showing USD 19.23 billion, growing at 5.13% CAGR over 2026-2031.
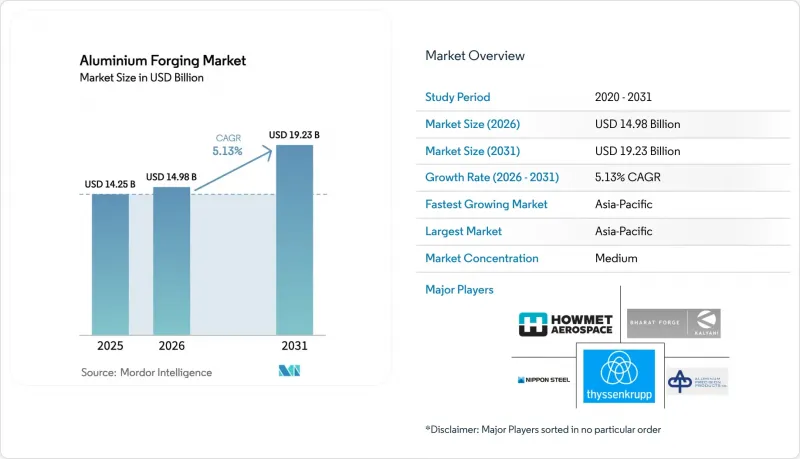
This report is Segmented by Forging Type (Open Die, Closed Die, and Ring Rolled), End-Use Industry (Aerospace and Defense, Automotive and Transportation, Industrial Machinery, Construction, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). Market Forecasts are Provided in Terms of Value (USD).
Global Aluminium Forging Market Trends and Insights
Growing Use of Lightweight Materials Across Industrial Sectors
Automotive and aerospace OEMs report a 40-50% reduction in component weight when aluminium forgings replace steel, resulting in a 6-8% range extension on 75 kWh EV packs Even advanced high-strength steel grades remain 2.9 times denser than aluminium, forcing trade-offs between payload and fuel economy. Industrial robotics firms are adopting forged aluminum manifolds and joints to reduce arm inertia, thereby shortening pick-and-place cycles by 200 ms and increasing throughput over three shifts. Construction equipment manufacturers specify forged aluminum for booms and jibs to comply with axle-load limits, thereby unlocking higher legal payloads without incurring highway permit penalties. Aerospace remains the most weight-sensitive user; each kilogram trimmed from an airframe saves about USD 3,000 in fuel during a 20-year life, making aluminium-lithium forgings preferable to composites for cryogenic tank domes and fuselage frames.
Surging Demand from EV-Oriented Automotive and Transportation OEMs
Ramkrishna Forgings invested INR 57.5 crore (approximately USD 6.9 million) in 2024 to create a 3,000 tpa aluminium forging capacity for EV suspension arms and battery-tray brackets. ILJIN's USD 100 million Alabama greenfield plant, announced in October 2024, will supply forged control arms to General Motors and Stellantis by Q3 2026. Mass reduction remains a key selling point; a 20 kg weight cut in unsprung parts yields an 8 km range gain on a 400-km EV, a critical margin in consumer purchase decisions. Fleet operators see analogous savings in commercial-vehicle electrification, as forged aluminium wheel hubs and steering knuckles lower rolling resistance and total cost per tonne-kilometer.
Aluminium LME Price Volatility and Hedging Costs
LME prices fell 20% from USD 2,600 per tonne in early 2024 to USD 2,080 in December, squeezing margins for spot-exposed forgers. Options premiums on 12-month collars widened to 4.5% of notional in 2024 versus 2.8% a year earlier, while the U.S. Midwest premium spiked to USD 1,323 per tonne in June 2025 on tariff-driven logistics snarls. Smaller Southeast Asian and Latin American suppliers lack access to sophisticated hedges and forfeit 8-12% of their margin to tolling structures. Japan's quarterly premium jumped 30% to USD 228 per tonne in Q1 2025 on scrap scarcity and LNG-linked power costs.
Other drivers and restraints analyzed in the detailed report include:
- Rising Aero-Engine Backlog Driving Closed-Die Orders
- Hydrogen-Ready Gas-Turbine Build-Out
- Stringent Defect-Detection Standards in Aerospace Supply Chains
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Closed-die processes held a 62.93% share of the aluminium forging market in 2025 and are projected to expand at a 5.24% CAGR, driven by +-0.5 mm tolerances that eliminate secondary machining in high-volume automotive and aerospace parts. Investments such as Aubert & Duval's EUR 75 million 60-MN press, due online in 2027, underline expectations of a sustained aero-engine backlog.
Ring-rolled forging retains niche status for bearings and pressure-vessel rings where weld-free geometry is indispensable. Open-die forging remains the preferred method for producing ultra-large parts exceeding 50 kg; China's 16,500-tonne Tai'an press underscores the state's support for the nuclear and petrochemical markets. Digital simulation platforms, such as FORGE NxT 4.1, reduce prototype cycles from five to two, thereby reducing scrap and energy costs across all forging types.
Complete Report Scope:
- By Forging Type
- Open Die Forging
- Closed Die Forging
- Ring Rolled Forging
- By End-Use Industry
- Aerospace and Defense
- Automotive and Transportation
- Industrial Machinery
- Construction
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Thailand
- Indonesia
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordic Countries
- Turkey
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- Qatar
- United Arab Emirates
- Nigeria
- Egypt
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
The Asia-Pacific region dominated the aluminium forging market with a 37.97% share in 2025, a position expected to widen at a 6.35% CAGR through 2031. China's withdrawal of its 13% aluminium semi-finished products rebate in December 2024 increased landed costs for ASEAN buyers, prompting them to consider long-term tolling deals. India's aluminium forging market is gaining momentum, driven by a per-capita consumption that lags behind the global average by a factor of four. A USD 40 billion investment in smelting expansion is needed to meet a demand of 10 million tonnes per annum by 2030.
North America's outlook improves with ILJIN's USD 100 million Alabama plant, which will supply EV control arms starting in Q3 2026, recapturing volume lost to Mexico. Europe consolidates around aerospace; Aubert & Duval's new press and EGA's 30,000 tpa recycled billet line in Germany support local circular-economy mandates. South America and the Middle East remain import-led for complex, closed-die parts, although Saudi Arabia's NEOM and Brazil's defense offsets are expected to foster joint ventures that will increase in-region share post-2026.
- Accurate Steel Forgings (INDIA) Limited
- Al Forge Tech Co., Ltd
- All Metals & Forge Group
- Aluminum Precision Products
- Anchor Harvey
- Anderson Shumaker Company
- Bharat Forge
- Ellwood Group Inc.
- Howmet Aerospace
- ILJIN co., ltd.
- KOBE STEEL, LTD.
- NIPPON STEEL CORPORATION
- Norsk Hydro ASA
- Ramkrishna Forgings LTD
- Scot Forge Company
- Thyssenkrupp AG
- Wheel India Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing use of lightweight materials across industrial sectors
- 4.2.2 Surging demand from EV-oriented automotive and transportation OEMs
- 4.2.3 Rising aero-engine backlog driving closed-die orders
- 4.2.4 Hydrogen-ready gas-turbine build-out
- 4.2.5 Local-content mandates in emerging economies
- 4.3 Market Restraints
- 4.3.1 Aluminium LME price volatility and hedging costs
- 4.3.2 Stringent defect-detection standards in aerospace supply chains
- 4.3.3 Energy-intensive hammer/press operations facing carbon taxes
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Forging Type
- 5.1.1 Open Die Forging
- 5.1.2 Closed Die Forging
- 5.1.3 Ring Rolled Forging
- 5.2 By End-Use Industry
- 5.2.1 Aerospace and Defense
- 5.2.2 Automotive and Transportation
- 5.2.3 Industrial Machinery
- 5.2.4 Construction
- 5.2.5 Other End-user Industries
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Malaysia
- 5.3.1.6 Thailand
- 5.3.1.7 Indonesia
- 5.3.1.8 Vietnam
- 5.3.1.9 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Nordic Countries
- 5.3.3.7 Turkey
- 5.3.3.8 Russia
- 5.3.3.9 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Colombia
- 5.3.4.4 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 Qatar
- 5.3.5.3 United Arab Emirates
- 5.3.5.4 Nigeria
- 5.3.5.5 Egypt
- 5.3.5.6 South Africa
- 5.3.5.7 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Accurate Steel Forgings (INDIA) Limited
- 6.4.2 Al Forge Tech Co., Ltd
- 6.4.3 All Metals & Forge Group
- 6.4.4 Aluminum Precision Products
- 6.4.5 Anchor Harvey
- 6.4.6 Anderson Shumaker Company
- 6.4.7 Bharat Forge
- 6.4.8 Ellwood Group Inc.
- 6.4.9 Howmet Aerospace
- 6.4.10 ILJIN co., ltd.
- 6.4.11 KOBE STEEL, LTD.
- 6.4.12 NIPPON STEEL CORPORATION
- 6.4.13 Norsk Hydro ASA
- 6.4.14 Ramkrishna Forgings LTD
- 6.4.15 Scot Forge Company
- 6.4.16 Thyssenkrupp AG
- 6.4.17 Wheel India Limited
7 Market Opportunities and Future Outlook
- 7.1 Advanced forging simulation and digitised press controls
- 7.2 Aluminium-Li alloy adoption in space and launch vehicles
- 7.3 White-space and Unmet-need Assessment

