PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125697

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125697
Table And Floor Lamps - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the table and floor lamps market size in 2026 is estimated at USD 26.41 billion, growing from 2025 value of USD 25.24 billion with 2031 projections showing USD 33.08 billion, growing at 4.62% CAGR over 2026-2031.
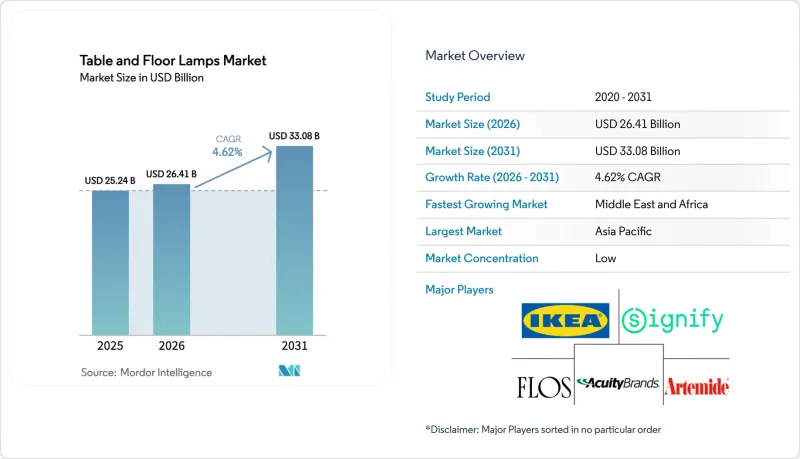
This report is Segmented by Product Type (Table Lamps, Floor Lamps and More), by Material (Metal, Wood, and More), by End-User (Residential, Commercial, and More), by Distribution Channel (Offline and Online) and by Geography (North America, Europe, Asia-Pacific, Latin America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Table And Floor Lamps Market Trends and Insights
Proliferation of Smart-Home Ecosystems Boosting Connected Lamps
Connected fixtures stand at the forefront where illumination converges with IoT, transforming the table and floor lamps market from commodity decor pieces into interactive nodes that respond to voice, occupancy, and security cues. Consumers expect seamless pairing with voice assistants and mobile dashboards, making interoperability a baseline rather than a luxury. The value comes not just from switching or dimming but from color-temperature tuning that syncs to circadian rhythms, adaptive light levels informed by ambient sensors, and predictive usage analytics that conserve energy. These functions justify higher average selling prices and subscription revenues for cloud-based scene libraries and remote diagnostics, lifting margins while binding customers to brand ecosystems. The desk-lamp category benefits disproportionately, as knowledge workers demand granular control to reduce eye strain and extend productive focus windows. Brands now embed upgradeable wireless chips and open APIs to future-proof purchases, turning lamps into long-life platforms rather than disposable appliances.
Growing Penetration of LED-Integrated Decorative Lamps
LED maturity has erased the historical efficiency-price trade-off, pushing the table and floor lamps market toward unqualified LED standardization. LEDs cover 70% of global lamp sales, and the looming secondary replacement wave-5.8 billion units in 2024-sustains volume even as lifetimes lengthen. Miniaturized emitter footprints unleash daring shapes and ultra-thin profiles, while addressable RGB arrays let one lamp toggle between task brightness and lounge mood at the swipe of a screen. Manufacturing cost curves now allow mainstream price points, making decorative LED pieces accessible in mass retail and hospitality alike. For designers, LED boards embedded in organic or translucent substrates enable fresh narratives; for consumers, top-tier color rendering and 50,000-hour lifespans translate to longer satisfaction cycles and reduced maintenance costs.
Margin Pressure from DIY Furniture-Store Private Labels
Mega-retailers exploit integrated supply chains to debut private-label lamps that undercut branded rivals by double-digit percentages while offering acceptable build quality. IKEA's top-five market status exemplifies how bundled home-furnishing assortments steer shoppers away from specialist brands. Mid-tier producers feel the squeeze, prompting portfolio rationalization, regional exit strategies, or downstream mergers financed by private equity. Kingswood Capital's USD 256 million sweep of Kichler and Progress Lighting into Coleto Brands illustrates that scale consolidation is a preferred defense. Legacy names now couple proprietary app ecosystems and designer collaborations to justify price premiums and shield margin integrity.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Hotel-Room Refurb Cycles in Lifestyle and Boutique Segments
- Workplace Wellness Programs Embracing Circadian-Lighting Task Lamps
- Safety-Code Tightening on Portable Luminaires
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Desk/task lamps generated the largest slice of the table and floor lamps market in 2025, seizing 48.62% revenue as employers and home workers converge on circadian-aligned illumination. Segment revenue reached USD 12.27 billion in 2025, and analysts project a steady 3.82% CAGR through 2031 as hybrid workflows persist. Floor lamps remain the breakout star, poised for a 14.02% CAGR, because hospitality operators and short-term landlords crave sculptural pieces that double as statement art. Traditional table lamps stay relevant, particularly when retrofitted with Wi-Fi drivers or voice-control modules that enable automation scenes. Accent, torchiere, and niche reading formats maintain modest volume, yet achieve healthy margins thanks to specialized optics and materials that address aging eyesight and design eccentricities. Competitive dynamics encourage multipurpose hybrids-task heads mounted on ambient towers-allowing a single SKU to satisfy living-room ambiance and focused worktop duties. Such versatility sustains upselling potential even as minimalism trends influence furniture footprints.
Second-generation smart task lamps integrate occupancy sensors, glare-control louvers, and USB-C charging docks, streamlining desktop clutter. Employers quantify lighting efficacy via wellness audits, correlating spectrum shifts with biometric feedback from wearables, thereby turning lamps into participatory wellbeing assets. The segment's premium tier enjoys lower price elasticity: corporate buyers allocate budget based on productivity gains rather than unit cost. Conversely, entry-level desk fixtures sold through mass e-commerce lean on commodity LEDs and plastic housings, showing thin margins yet vast unit potential. The table and floor lamps market size for desk/task lamps is set to approach USD 15.36 billion by 2031, underscoring persistent dominance even as newer categories accelerate.
Metal remained the material of choice in 2025, holding 35.78% revenue, primarily through steel and aluminum constructions that grant durability, thermal management for LEDs, and broad aesthetic range. Robust supply chains and CNC versatility streamline design iterations, letting brands combine brushed finishes with powder-coat colors for rapid trend response. Nonetheless, wood posts the highest 14.28% CAGR outlook thanks to sustainability appeal and emerging research on transparent, phosphorescent wood panels that emit soft afterglow while showcasing natural grain. Such composites ally eco-credentials with functional luminosity, attractive to eco-conscious millennials who value carbon narratives simplified through FSC-certified sourcing.
Glass persists as the premium medium for sculptural statement lamps, leveraging optical clarity and hand-blown craftsmanship to tap luxury price bands. Glass also benefits from LED's low heat output, allowing thinner profiles without thermal cracks. Ceramic resurges in boutique studios where tactile glazes produce individualistic finishes; small-batch ceramic runs exploit local clay traditions and align with the burgeoning "slow decor" movement. Recycled plastic alloys and hemp-fiber biopolymers populate budget-friendly lines, their color flexibility supporting seasonal palettes. As commodity metals face price unpredictability, design teams adopt mixed-material strategies-metal frames with wooden arms or rattan shades-to hedge costs and lift perceived artisanal value. Segment leaders now disclose life-cycle assessments, reinforcing transparency and tipping procurement decisions among contract buyers weighing ESG metrics.
Complete Report Scope:
- By Product Type
- Table Lamps
- Floor Lamps
- Desk/Task Lamps
- Accent and Decorative Lamps
- Torchieres and Uplights
- Others
- By Material
- Metal
- Wood
- Glass
- Ceramic
- Plastic and Others
- By End-user
- Residential
- Commercial
- Hospitality
- Offices and Co-working Spaces
- Retail and Restaurants
- Healthcare Facilities
- Educational Institutions
- Others (Commercial)
- Institutional
- Industrial and Others
- By Distribution Channel
- Offline
- Specialty Lighting Stores
- Furniture and Home-center Chains
- Hypermarkets / Department Stores
- Online
- Brand-owned Webstores
- Marketplaces (Amazon, Wayfair, etc.)
- Offline
- By Geography
- North America
- Canada
- United States
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia Pacific
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Middle East and Africa
- United Arab of Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East And Africa
- North America
Geography Analysis
Asia-Pacific led the table and floor lamps market with 34.11% revenue in 2025 on the back of concentrated manufacturing clusters, competitive labor costs, and expanding urban middle-class consumption. China's introduction of eight lighting standards in January 2024 underscores regulatory drive to elevate quality and safety while encouraging domestic innovation. Japan and South Korea showcase early-adopter appetite for voice-assistant lighting scenes and ultra-compact desk lamps suited to dense living spaces. India's Smart Cities Mission and rising disposable incomes spur premium demand, although fragmented distribution networks pose reach challenges beyond tier-one metros. Southeast Asian economies, including Vietnam and Indonesia, see accelerating project pipelines in hospitality and residential high-rises, generating contract volumes for both domestic and foreign brands.
Middle East & Africa posts the fastest 9.21% CAGR forecast to 2031, propelled by mega-projects in Gulf states, energy diversification strategies, and robust hospitality pipelines targeting tourism diversification. The UAE lighting sector, valued at USD 336 million, targets 15% growth as Dubai's solar-park initiatives dovetail with architectural showpieces that specify smart LED installations. Saudi Arabia's Vision 2030 funds cultural hubs, entertainment districts, and luxury resorts that demand high-spec lamps for guest rooms and public lounges. African metros from Nairobi to Lagos modernize hotel stock and upscale residences, though erratic power supply pushes appetite for LED efficiency and integrated battery backup.
North America continues to display strong adoption of connected solutions; the U.S. Department of Energy's tightened lamp efficiency rules effective July 2024 accelerate the shift toward integrated LED fixtures. Consumers embrace voice synchronization across smart-speaker ecosystems, and corporate buyers scale datacentric wellness pilots. European markets mirror North America in maturity but intensify circular-economy criteria, rewarding brands that offer repairable modules and certified recycled content. In Germany and the Nordics, public procurement frameworks now award points for end-of-life recyclability, steering tenders toward modular designs. Despite slower unit growth, both regions offer high average selling prices and early adoption for emerging control protocols such as Matter, reinforcing their influence on global standards.
- Signify (Philips Lighting)
- IKEA Group
- Acuity Brands Lighting
- FLOS
- Artemide
- Hudson Valley Lighting
- Generation Lighting (Visual Comfort)
- Kichler Lighting
- Eglo Leuchten
- Foscarini
- Lutron Electronics
- Ralph Lauren Home
- Quoizel
- House of Troy
- Adesso Inc.
- Zumtobel Group
- NVC Lighting
- Osram GmbH
- Zaozuo
- Targetti Sankey*
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of smart-home ecosystems boosting connected lamps
- 4.2.2 Growing penetration of LED-integrated decorative lamps
- 4.2.3 Rapid hotel-room refurb cycles in lifestyle and boutique segments
- 4.2.4 Workplace wellness programs embracing circadian-lighting task lamps
- 4.2.5 Surge in short-term rental hosts demanding statement lighting
- 4.2.6 AI-driven design-to-manufacture platforms enabling micro-brands
- 4.3 Market Restraints
- 4.3.1 Margin pressure from DIY furniture-store private labels
- 4.3.2 Safety-code tightening on portable luminaires (fire and tip-over)
- 4.3.3 Volatility in metal and glass commodity prices
- 4.3.4 Lengthening replacement cycles due to ultra-long-life LEDs
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts
- 5.1 By Product Type
- 5.1.1 Table Lamps
- 5.1.2 Floor Lamps
- 5.1.3 Desk/Task Lamps
- 5.1.4 Accent and Decorative Lamps
- 5.1.5 Torchieres and Uplights
- 5.1.6 Others
- 5.2 By Material
- 5.2.1 Metal
- 5.2.2 Wood
- 5.2.3 Glass
- 5.2.4 Ceramic
- 5.2.5 Plastic and Others
- 5.3 By End-user
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.2.1 Hospitality
- 5.3.2.2 Offices and Co-working Spaces
- 5.3.2.3 Retail and Restaurants
- 5.3.2.4 Healthcare Facilities
- 5.3.2.5 Educational Institutions
- 5.3.2.6 Others (Commercial)
- 5.3.3 Institutional
- 5.3.4 Industrial and Others
- 5.4 By Distribution Channel
- 5.4.1 Offline
- 5.4.1.1 Specialty Lighting Stores
- 5.4.1.2 Furniture and Home-center Chains
- 5.4.1.3 Hypermarkets / Department Stores
- 5.4.2 Online
- 5.4.2.1 Brand-owned Webstores
- 5.4.2.2 Marketplaces (Amazon, Wayfair, etc.)
- 5.4.1 Offline
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 Canada
- 5.5.1.2 United States
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Peru
- 5.5.2.3 Chile
- 5.5.2.4 Argentina
- 5.5.2.5 Rest of South America
- 5.5.3 Asia-Pacific
- 5.5.3.1 India
- 5.5.3.2 China
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- 5.5.3.7 Rest of Asia Pacific
- 5.5.4 Europe
- 5.5.4.1 United Kingdom
- 5.5.4.2 Germany
- 5.5.4.3 France
- 5.5.4.4 Spain
- 5.5.4.5 Italy
- 5.5.4.6 BENELUX (Belgium, Netherlands, and Luxembourg)
- 5.5.4.7 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.5.4.8 Rest of Europe
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab of Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Nigeria
- 5.5.5.5 Rest of Middle East And Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Signify (Philips Lighting)
- 6.4.2 IKEA Group
- 6.4.3 Acuity Brands Lighting
- 6.4.4 FLOS
- 6.4.5 Artemide
- 6.4.6 Hudson Valley Lighting
- 6.4.7 Generation Lighting (Visual Comfort)
- 6.4.8 Kichler Lighting
- 6.4.9 Eglo Leuchten
- 6.4.10 Foscarini
- 6.4.11 Lutron Electronics
- 6.4.12 Ralph Lauren Home
- 6.4.13 Quoizel
- 6.4.14 House of Troy
- 6.4.15 Adesso Inc.
- 6.4.16 Zumtobel Group
- 6.4.17 NVC Lighting
- 6.4.18 Osram GmbH
- 6.4.19 Zaozuo
- 6.4.20 Targetti Sankey*
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

