PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125717

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125717
Ad Tech - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the advertising tech market size was valued at USD 0.898 trillion in 2025 and estimated to grow from USD 0.99 trillion in 2026 to reach USD 1.59 trillion by 2031, at a CAGR of 10.05% during the forecast period (2026-2031).
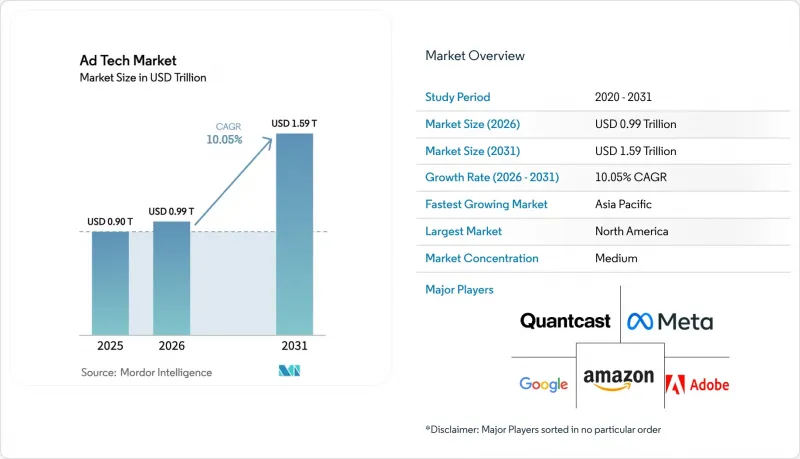
This report is Segmented by Platform (DSP, SSP, Ad Exchanges, DMP, and More), Ad Format (Search, Display, Video, Social Media, Email, and More), Device Platform (Mobile, Desktop, CTV and OTT, and More), End-User Industry (Retail, BFSI, Healthcare, Media, IT, Automotive, Education, and More), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Ad Tech Market Trends and Insights
CTV-led programmatic surge
Streaming publishers are shifting inventory from direct insertion orders to open auctions, and programmatic CTV now attracts 17% of total brand budgets. The Trade Desk's Ventura operating system improves frequency capping and audience reach for buyers while lowering publisher tech spend. Convergence with retail-media datasets delivers deterministic attribution that ties viewership to purchases. Over 95% of surveyed advertisers plan to maintain or expand CTV allocations, highlighting resilient demand even amid economic volatility. Platforms with unified ID frameworks gain priority access to premium video placements, which in turn accelerates supply-path optimisation across the advertising tech market.
Third-party-cookie deprecation
Chrome's phased withdrawal of cookies and the EU's consent string ruling are accelerating migration to first-party identifiers. Google's Privacy Sandbox faces yield gaps of up to 33% for publishers during early testing phases. Marketers are therefore increasing contextual targeting budgets and adopting clean-room integrations that retain addressability without personal identifiers. Retailers with authenticated transaction data benefit from surging advertiser interest, while smaller publishers exploit semantic-signal models to preserve CPMs. Customer-data-platform deployments have become standard practice for omni-channel brands aiming to future-proof activation workflows.
Global privacy laws limiting cross-device graphs
The March 2024 Court of Justice ruling classifies consent strings as personal data, making IAB Europe a joint controller and raising compliance burdens across the supply chain. New obligations under the Digital Markets Act demand clear opt-ins for every data use, eroding performance of cross-device identifiers. Gatekeeper platforms must provide click-level transparency, shifting competitive advantage toward privacy-native contextual solutions. Many large advertisers have capped EU retargeting spend and diverted incremental funds to curated marketplaces, diminishing short-term growth potential in the advertising tech market.
Other drivers and restraints analyzed in the detailed report include:
- AI-driven dynamic creative optimisation
- Retail-media monetisation of first-party data
- Rising sophistication of ad-fraud
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ad Exchanges delivered 63.62% of 2025 spend, anchoring liquidity across open auctions. Demand-Side Platforms, while smaller, are growing at 12.08% annually as buyers prefer automated optimisations that cut operational overheads. The advertising tech market size captured by DSPs is projected to widen materially through 2031 as enterprise advertisers migrate bulk budgets into self-serve workflows. Amazon's DSP already accounts for almost one-third of the retailer's ad turnovers, underscoring the synergies of commerce data with programmatic bidding.
Supply-Side Platforms respond by deepening supply-path optimisation, with PubMatic funnelling more than half of traded impressions through preferential pipes that carry reduced take-rates. Smaller data-management-platform vendors lose relevance when third-party cookies vanish and are either shuttered or absorbed by larger stacks. Microsoft's planned exit from stand-alone DSP operations illustrates the capital intensity required to keep pace with machine-learning innovation. As competitive barriers climb, platform consolidation is expected, compressing the long-tail provider base inside the advertising tech market.
Search captured 38.15% of revenue in 2025 and is still expanding at a 11.92% CAGR, leveraging AI-driven multimodal query interpretation to surface commerce-adjacent results. Video formats, buoyed by CTV and mobile apps, siphon incremental brand dollars away from static display. Social media growth is flattening due to tighter content policies, particularly within sensitive health and financial categories.
In-game and augmented-reality placements are embryonic yet show high engagement, attracting exploratory budgets from consumer-electronics brands. Email remains resilient thanks to authenticated data sets that circumvent identifier restrictions. Google's Gemini platform is expected to embed native search ads into conversational responses, creating fresh inventory pools without disrupting user intent. The advertising tech market continues to evolve from banner impressions toward experience-centric formats that promise measurable outcomes across immersive environments.
Complete Report Scope:
- By Platform
- Demand-Side Platforms (DSP)
- Supply-Side Platforms (SSP)
- Ad Exchanges
- Data Management Platforms (DMP)
- Others
- By Ad Format
- Search Advertising
- Display/Banner
- Video Advertising
- Social Media
- Others
- By Device Platform
- Mobile Devices and Smartphones
- Desktop and Laptop
- Connected TV and OTT Devices
- Other Devices (Smart Speakers, Wearables)
- By End-user Industry
- Retail and E-commerce
- BFSI
- Healthcare and Pharmaceuticals
- Media and Entertainment
- IT and Telecommunications
- Services
- Automotive
- Education
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
North America retained 40.12% of 2025 turnover, supported by mature infrastructure, deep advertiser sophistication, and robust CTV adoption that lifted streaming spend to USD 30.1 billion. Large retail-media networks and advanced identity frameworks reinforce the region's primacy, even as emerging state privacy statutes add compliance friction. Technology vendors headquartered in the United States account for the majority of intellectual-property filings and attract the bulk of venture funding, further entrenching leadership within the advertising tech market.
Asia-Pacific is the fastest-growing territory at a 12.16% CAGR, propelled by mobile-first consumer behaviour, accelerated 5G coverage, and surging e-commerce activity. GSMA estimates mobile technology contributed USD 880 billion to regional GDP in 2023, with a USD 1 trillion forecast for 2030. China's super-app ecosystems integrate payments, social, and content, creating blueprints that advertisers in India, Indonesia, and Vietnam are now adopting. Regulatory approaches remain heterogeneous, but most jurisdictions continue to encourage foreign investment in digital media, sustaining long-term momentum for the advertising tech market.
Europe shows moderate growth as comprehensive privacy laws squeeze cross-device targeting but encourage innovation in contextual and cohort-based models. Retail-media spending is projected to reach EUR 25 billion by 2026 on the back of harmonised measurement protocols. South America and the Middle East and Africa represent early-stage adoption curves characterised by improving broadband penetration and rising local content production. Programmatic spend in South America climbed from USD 5.2 billion in 2017 to USD 16.8 billion in 2023, while the MENA region's digital advertising outlay is on track to quintuple between 2022 and 2025. These trends confirm a broadening global footprint for the advertising tech market.
- Alphabet Inc.
- Meta Platforms, Inc.
- Amazon.com, Inc.
- The Trade Desk, Inc.
- Microsoft Corporation
- Adobe Inc.
- Yahoo Inc. (Owned by Apollo Global Management)
- Magnite, Inc.
- PubMatic, Inc.
- Criteo S.A.
- Oracle Corporation
- Index Exchange Inc.
- MediaMath Inc.
- InMobi Pte. Ltd.
- AppLovin Corporation
- Zeta Global Holdings Corp.
- Adform A/S
- Quantcast Corporation
- Rakuten Group, Inc.
- IronSource Ltd. (Merged with Unity Software Inc.)
- StackAdapt Inc.
- Xandr Inc. (Acquired by Microsoft)
- Mediaocean LLC
- OpenX
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 CTV-Led Programmatic Surge in North America
- 4.2.2 Deprecation of Third-Party Cookies Accelerating First-Party Data Solutions
- 4.2.3 AI-Driven Dynamic Creative Optimisation Uplifting ROAS
- 4.2.4 Retail Media Networks Monetising First-Party Shopper Data
- 4.2.5 GDPR-Style Regulations Fueling Contextual Targeting in Europe
- 4.2.6 5G Roll-outs Enabling Rich Mobile Video Ads Across Asia
- 4.3 Market Restraints
- 4.3.1 Global Privacy Laws Constraining Cross-Device Identity Graphs
- 4.3.2 Rising Sophistication of Ad-Fraud in Emerging Markets
- 4.3.3 Supply-Path Complexity Elevating Transparency Costs
- 4.3.4 Acute Data-Engineering Talent Shortages
- 4.4 Technological Outlook
- 4.4.1 Digital Transformation in Advertising Platforms
- 4.4.2 Location-Based and Contextual Advertising Advances
- 4.5 Regulatory Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
- 4.7 Impact of Macroeconomic Headwinds on Digital Ad Spend
5 Market Size and Growth Forecasts (Value)
- 5.1 By Platform
- 5.1.1 Demand-Side Platforms (DSP)
- 5.1.2 Supply-Side Platforms (SSP)
- 5.1.3 Ad Exchanges
- 5.1.4 Data Management Platforms (DMP)
- 5.1.5 Others
- 5.2 By Ad Format
- 5.2.1 Search Advertising
- 5.2.2 Display/Banner
- 5.2.3 Video Advertising
- 5.2.4 Social Media
- 5.2.5 Email
- 5.2.6 Others
- 5.3 By Device Platform
- 5.3.1 Mobile Devices and Smartphones
- 5.3.2 Desktop and Laptop
- 5.3.3 Connected TV and OTT Devices
- 5.3.4 Other Devices (Smart Speakers, Wearables)
- 5.4 By End-user Industry
- 5.4.1 Retail and E-commerce
- 5.4.2 BFSI
- 5.4.3 Healthcare and Pharmaceuticals
- 5.4.4 Media and Entertainment
- 5.4.5 IT and Telecommunications
- 5.4.6 Services
- 5.4.7 Automotive
- 5.4.8 Education
- 5.4.9 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Rest of Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Strategic Moves (M&A, Partnerships, Funding)
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.3.1 Alphabet Inc.
- 6.3.2 Meta Platforms, Inc.
- 6.3.3 Amazon.com, Inc.
- 6.3.4 The Trade Desk, Inc.
- 6.3.5 Microsoft Corporation
- 6.3.6 Adobe Inc.
- 6.3.7 Yahoo Inc. (Owned by Apollo Global Management)
- 6.3.8 Magnite, Inc.
- 6.3.9 PubMatic, Inc.
- 6.3.10 Criteo S.A.
- 6.3.11 Oracle Corporation
- 6.3.12 Index Exchange Inc.
- 6.3.13 MediaMath Inc.
- 6.3.14 InMobi Pte. Ltd.
- 6.3.15 AppLovin Corporation
- 6.3.16 Zeta Global Holdings Corp.
- 6.3.17 Adform A/S
- 6.3.18 Quantcast Corporation
- 6.3.19 Rakuten Group, Inc.
- 6.3.20 IronSource Ltd. (Merged with Unity Software Inc.)
- 6.3.21 StackAdapt Inc.
- 6.3.22 Xandr Inc. (Acquired by Microsoft)
- 6.3.23 Mediaocean LLC
- 6.3.24 OpenX
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

