PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125724

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125724
Cruise Tourism - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the cruise tourism market size is expected to grow from USD 191.27 billion in 2025 to USD 203.79 billion in 2026 and is forecast to reach USD 279.76 billion by 2031 at 6.55% CAGR over 2026-2031.
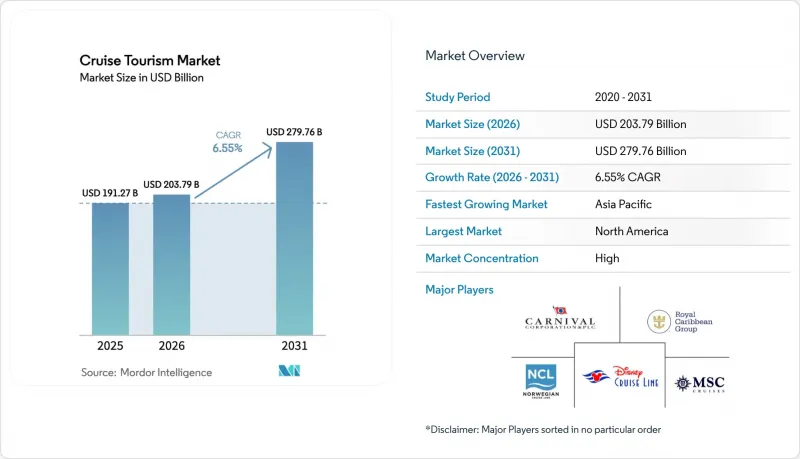
This report is Segmented by Type (River Cruise, Ocean Cruise, Expedition Cruise, Theme Cruise, Adventure Cruise, Others), Duration (1-7 Days, 8-14 Days, 15-20 Days, More Than 21 Days), Passenger Age (Less Than 12 Years, 13-19 Years, 20-39 Years, 40-59 Years, Above 60 Years), and Geography (North America, South America, Europe, and Other). The Market Forecasts are Provided in Terms of Value (USD).
Global Cruise Tourism Market Trends and Insights
Growing Middle-Class Income Expansion Reshapes Passenger Demographics
Emerging market prosperity fundamentally alters cruise accessibility, with China's middle-class households earning above USD 10,000 annually projected to reach 550 million by 2030. This demographic expansion drives first-time cruiser adoption rates exceeding 15% annually across ASEAN markets, where multi-generational family bookings now represent 35% of regional demand. The shift enables operators to deploy larger vessels on Asia-Pacific itineraries, with average ship capacity increasing 23% since 2024 as lines chase economies of scale. Pricing strategies adapt accordingly, with premium operators launching mid-market brands specifically targeting emerging market consumers who prioritize value over luxury amenities.
Mega-Ship Economics Transform Capacity Deployment Strategies
Twenty-five ships ordered in 2024 add 6,000-plus berths each and cut per-capita operating expenses by up to 22% thanks to fuel-efficient hulls . Larger vessels enable older tonnage redeployment into secondary markets without diluting premium route pricing. Balance-sheet risk rises, however, if demand misaligns with supply in mature corridors. Operators mitigate exposure by aligning delivery schedules with forward bookings and by forging favorable long-term financing at today's relatively low borrowing costs. Airports and ports race to expand infrastructure that accommodates ships exceeding 250,000 gross tons.
Economic Volatility Pressures Discretionary Travel Budgets
Inflationary pressures and recession fears create headwinds for cruise demand, particularly among price-sensitive emerging market consumers who represent the industry's primary growth engine. Central bank monetary tightening cycles reduce household disposable income, with cruise bookings showing a 0.7-0.9 correlation to consumer confidence indices across major source markets. Operators respond through dynamic pricing strategies and flexible payment plans, yet sustained economic weakness could force capacity reductions or aggressive discounting that erodes profitability. The challenge intensifies in markets like China and India, where nascent cruise cultures lack the loyalty patterns that sustain demand during downturns.
Other drivers and restraints analyzed in the detailed report include:
- Post-Pandemic Experiential Travel Demand Sustains Premium Pricing
- Retiree Wealth Concentration Drives Extended Voyage Demand
- Environmental Compliance Costs Strain Operating Margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Expedition vessels generate a 10.12% CAGR, even though ocean cruises retain 71.12 of % 2025 revenue dominance. The cruise tourism market size for expedition itineraries is set to climb from USD 7.9 billion in 2025 to USD 14.1 billion by 2031, benefiting from per-passenger yields exceeding USD 1,000 daily. Operators invest in ice-class hulls, zodiac fleets, and science partnerships to differentiate, yet must balance growth against fragile polar ecosystems. River cruises, theme voyages, and adventure sailings broaden customer choice but face port-infrastructure and seasonality constraints that slow expansion.
Passengers' appetite for authenticity drives niche-segment proliferation. Smaller ships access restricted bays and remote villages, fostering cultural exchange and sustainable tourism narratives. However, polar-region restrictions could cap capacity if environmental thresholds tighten further. High ticket prices insulate margins but expose demand to macroeconomic swings. Strategic collaboration with local authorities ensures controlled visitor volumes while preserving itinerary appeal.
Complete Report Scope:
- By Type
- River Cruise
- Ocean Cruise
- Expedition Cruise
- Theme Cruise
- Adventure Cruise
- Others
- By Duration
- 1-7 Days
- 8-14 Days
- 15-20 Days
- More than 21 Days
- By Passenger Age
- Less than 12 Years
- 13-19 Years
- 20-39 Years
- 40-59 Years
- Above 60 Years
- By Geography
- North America
- Canada
- United States
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Geography Analysis
North America retains 52.20% revenue share, anchored by Caribbean and Alaska routes supported by extensive port networks and favorable regulatory frameworks. Environmental restrictions in Alaska tighten itinerary windows, but Canada's Arctic infrastructure upgrades unlock new summer options. Mexico's Caribbean investments expand embarkation alternatives, reducing reliance on U.S. ports.
Asia-Pacific's 10.78% CAGR crowns it the fastest-growing region. Governments allocate more than USD 15 billion to port facilities, customs modernization, and cruise-specific marketing. China's state-backed shipbuilding accelerates domestic capacity, and Singapore leverages Changi Airport connectivity to capture fly-cruise traffic. Australia benefits from southern-hemisphere seasonality that fills berths during the Northern Hemisphere winter.
Europe enjoys mature but modest growth as Mediterranean and Baltic voyages capitalize on UNESCO-rich ports. However, the EU ETS raises operating expenses and may redirect older tonnage to less-regulated waters. Eastern European terminals emerge as cost-efficient alternatives, while Brexit complicates itinerary planning between the UK and continental ports.
- Carnival Corporation & plc
- Royal Caribbean Group
- Norwegian Cruise Line Holdings Ltd.
- MSC Cruises S.A.
- Disney Cruise Line
- Viking Cruises Ltd.
- Genting Hong Kong Ltd. (Dream Cruises)
- Silversea Cruises
- Ponant
- Lindblad Expeditions
- Hurtigruten Group
- Scenic Luxury Cruises & Tours
- Oceania Cruises
- Regent Seven Seas Cruises
- Crystal Cruises
- Azamara
- Seabourn Cruise Line
- Holland America Line
- Celebrity Cruises
- Princess Cruises
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing middle-class disposable income in emerging markets
- 4.2.2 Rapid expansion of new-build ocean vessels & mega-ships
- 4.2.3 Strong post-COVID pent-up demand for experiential travel
- 4.2.4 Surge in retiree wealth fueling longer cruise vacations
- 4.2.5 Opening of previously restricted polar waterways (Arctic/Antarctic)
- 4.2.6 Government-backed port infrastructure upgrades in developing economies
- 4.3 Market Restraints
- 4.3.1 Macroeconomic shocks elevating travel-cost sensitivity
- 4.3.2 Environmental regulations raising operating costs (IMO 2030 targets)
- 4.3.3 Limited berth capacity at marquee ports causing itinerary congestion
- 4.3.4 Rising geopolitical instability along key cruise corridors
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Type
- 5.1.1 River Cruise
- 5.1.2 Ocean Cruise
- 5.1.3 Expedition Cruise
- 5.1.4 Theme Cruise
- 5.1.5 Adventure Cruise
- 5.1.6 Others
- 5.2 By Duration
- 5.2.1 1-7 Days
- 5.2.2 8-14 Days
- 5.2.3 15-20 Days
- 5.2.4 More than 21 Days
- 5.3 By Passenger Age
- 5.3.1 Less than 12 Years
- 5.3.2 13-19 Years
- 5.3.3 20-39 Years
- 5.3.4 40-59 Years
- 5.3.5 Above 60 Years
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 Canada
- 5.4.1.2 United States
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Peru
- 5.4.2.3 Chile
- 5.4.2.4 Argentina
- 5.4.2.5 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 United Kingdom
- 5.4.3.2 Germany
- 5.4.3.3 France
- 5.4.3.4 Spain
- 5.4.3.5 Italy
- 5.4.3.6 BENELUX (Belgium, Netherlands, and Luxembourg)
- 5.4.3.7 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.4.3.8 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 India
- 5.4.4.2 China
- 5.4.4.3 Japan
- 5.4.4.4 Australia
- 5.4.4.5 South Korea
- 5.4.4.6 South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- 5.4.4.7 Rest of Asia-Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 United Arab Emirates
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 South Africa
- 5.4.5.4 Nigeria
- 5.4.5.5 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Carnival Corporation & plc
- 6.4.2 Royal Caribbean Group
- 6.4.3 Norwegian Cruise Line Holdings Ltd.
- 6.4.4 MSC Cruises S.A.
- 6.4.5 Disney Cruise Line
- 6.4.6 Viking Cruises Ltd.
- 6.4.7 Genting Hong Kong Ltd. (Dream Cruises)
- 6.4.8 Silversea Cruises
- 6.4.9 Ponant
- 6.4.10 Lindblad Expeditions
- 6.4.11 Hurtigruten Group
- 6.4.12 Scenic Luxury Cruises & Tours
- 6.4.13 Oceania Cruises
- 6.4.14 Regent Seven Seas Cruises
- 6.4.15 Crystal Cruises
- 6.4.16 Azamara
- 6.4.17 Seabourn Cruise Line
- 6.4.18 Holland America Line
- 6.4.19 Celebrity Cruises
- 6.4.20 Princess Cruises
7 Market Opportunities & Future Outlook
- 7.1 Development of carbon-neutral cruise itineraries & vessels
- 7.2 Monetization of private-island experiential hubs in emerging regions

