PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154242

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154242
Aircraft Lighting - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
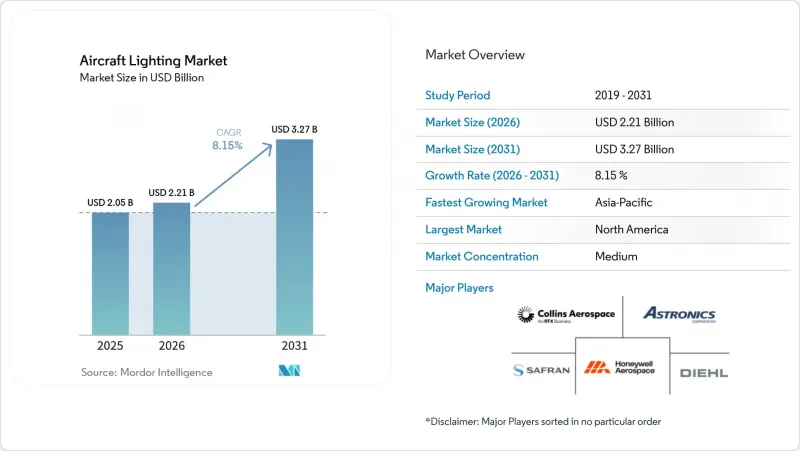
According to Mordor Intelligence, the aircraft lighting market size was valued at USD 2.05 billion in 2025, and is forecast to grow from USD 2.21 billion in 2026 to USD 3.27 billion by 2031 at a 8.12% CAGR during the forecast period (2026-2031).
Global Aircraft Lighting Market Trends and Insights
Growth in Aircraft Deliveries and Fleet Expansion
Aircraft delivery volumes directly support the aircraft lighting market, as each new aircraft requires certified interior, exterior, cockpit, and emergency lighting before entering service. Airbus delivered 793 commercial aircraft in 2025, a 4% increase from the prior year, and targets 870 deliveries in 2026. These deliveries create linefit demand for lighting suppliers that have positions on commercial aircraft programs. The large installed order backlog also gives suppliers visibility beyond short production cycles, even though each aircraft program has its own approved configuration. Military procurement adds another source of demand, as combat, tanker, and transport aircraft require platform-specific lighting. The US Air Force FY2026 budget covers aircraft procurement and modernization programs that require specialized systems, including night-vision-compatible lighting.
LED Adoption for Lower Power Consumption and Maintenance
LED adoption continues to reshape the aircraft lighting market because airlines seek lower electrical load and fewer component replacements. SAE ARP6253A, revised in 2025, sets requirements for LED aircraft applications across electrical interfaces, thermal management, and electromagnetic compatibility. The FAA is also converting more than 900 Medium Intensity Approach Lighting Systems to LED technology, with work beginning in early 2024 and a transition expected to take 6-8 years. Certified LED reading lights can exceed 100,000 hours of mean time between failures, use up to 50% less power, and reduce weight by up to 36.50 kg on widebody aircraft. Longer service life reduces routine replacements, but the technology creates inspection and compliance work when wiring, controls, or interfaces require attention. The FAA's 2026 directive on B777 LED sidewall wire bundles illustrates how maintenance needs can follow a fleetwide lighting upgrade.
High Certification, Integration, and Aircraft Constraints
Certification costs can limit adoption in the aircraft lighting market, particularly for connected products and aircraft-specific retrofit programs. EASA Amendment 25/29, effective in August 2024, extended airworthiness security requirements to new large aircraft and major changes. Suppliers may need to complete validation across several authorities, which can lengthen documentation and approval work. Fire testing, electrical integration, thermal management, weight limits, and available aircraft power all add design constraints for a new lighting installation. Smaller specialists often need third-party test facilities, which adds cost and scheduling risk. Operators can face higher prices for certified retrofit kits, while spending priorities may favor in-flight entertainment and connectivity projects over lighting upgrades.
Other drivers and restraints analyzed in the detailed report include:
- Aircraft Cabin Modernization and Retrofit Programs
- Passenger Experience Differentiation Through Dynamic Lighting
- Cybersecurity and Electromagnetic-Compatibility Validation for Connected Lighting
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fixed-wing aircraft held 82.67% of revenue in 2025, supported by commercial narrowbody production and high-value military transport programs. Airbus delivered 793 commercial aircraft in 2025 and ended the year with an order backlog of 8,754 aircraft. New narrowbody aircraft use multi-zone LED systems that must meet the environmental qualification requirements of SAE ARP5873B and RTCA DO-160. Military fixed-wing platforms, including the F-35A, F-15EX, and KC-46A, require premium lighting packages to increase revenue per aircraft. These programs keep fixed-wing aircraft as the main source of OEM linefit demand in the aircraft lighting market.
Rotorcraft is forecast to grow at a 9.69% CAGR from 2026 to 2031. Military rotary-wing modernization, offshore energy operations, and advanced air mobility platforms support this growth. NATO member states are adopting night-vision-compatible cockpit illumination and formation-lighting upgrades on helicopters, which can bring retrofit work forward from normal replacement cycles. Offshore operators of the Airbus H175 and Leonardo AW189 face airworthiness requirements for maritime exterior lighting intensity and failure-mode performance. EASA's Special Condition for Small VTOL aircraft established lighting certification criteria for eVTOL aircraft, creating an additional procurement category for rotary-adjacent aircraft.
Interior lighting accounted for 45.27% of revenue in 2025 because it covers passenger cabins, galleys, lavatories, reading lights, service areas, emergency lighting, and ambient systems. Passenger cabin lighting is highly valued by airlines, as they install programmable LED systems that support color tuning and cabin branding. Emergency and exit lighting needs rigorous qualification and traceability because it is safety-critical equipment. Galley and lavatory lights may require more frequent replacement due to exposure to heat and moisture. These operating conditions make reliability and service support important selection factors.
Cockpit lights are forecast to grow at an 11.49% CAGR through 2031, the fastest rate among light types in the aircraft lighting market. Avionics upgrades and wider use of night-vision-compatible lighting support this demand in military and para-public aircraft. Exterior systems must meet FAA and EASA color and intensity requirements, maintaining replacement demand as operators convert older systems to LED technology. Mood lighting is increasingly selected against measurable chromaticity and thermal performance requirements, a change that broadens the technical basis for supplier evaluation.
Complete Report Scope:
- By Aircraft Type
- Fixed-Wing Aircraft
- Commercial Aircraft
- Business Jets and General Aviation Aircraft
- Military Aircraft
- Rotorcraft
- Fixed-Wing Aircraft
- By Light Type
- Interior Lights
- Passenger Cabin Lighting
- Galley and Lavatory Lighting
- Reading and Service Lighting
- Emergency and Exit Lighting
- Mood and Ambient Lighting
- Other Interior Lighting
- Exterior Lights
- Navigation and Position Lights
- Anti-Collision Lights
- Landing and Taxi Lights
- Other Exterior Lighting
- Cockpit Lights
- Interior Lights
- By End User
- OEM Linefit
- Aftermarket/Retrofit
- By Technology
- LED
- Conventional Lighting
- Other Emerging Lighting
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- France
- Germany
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America accounted for 40.89% of the aircraft lighting market in 2025, supported by Boeing production, dense MRO activity, and US military procurement. The United States has more than 200,000 registered general aviation aircraft, which supports replacement demand for cockpit and exterior LED equipment. Boeing increased its cleared B737 MAX output rate from 42 to 47 aircraft per month in 2026, adding linefit volume for narrowbody suppliers. The FAA had completed more than 28 MALS conversions by May 2025 and is targeting over 900 systems for LED transition.
Europe is the second-largest regional market, supported by Airbus production sites in Toulouse and Hamburg. The aircraft lighting market benefits from the region's network of qualified suppliers, integrators, and MRO operators. EASA requirements for photometric performance and airworthiness security raise approval costs while protecting suppliers with established testing resources. France and Germany lead regional activity due to their ties to the Airbus supply chain. European low-cost carriers standardize LED configurations across narrow fleets to limit spares complexity and support repeat replacement work.
Asia-Pacific is forecast to grow at a 10.28% CAGR through 2031, making it the fastest-growing geography within the aircraft lighting market. Airbus forecasts that the region will require 19,120 new passenger aircraft by 2045, driven by growth in its middle-income population. China Eastern Airlines ordered 101 Airbus aircraft in March 2026, while AirAsia ordered 150 A220-300 aircraft. China's rising fleet age creates retrofit demand alongside new deliveries. Embraer's commercial programs in Brazil support South America, while the Middle East is important because Emirates is investing USD 5 billion to refurbish 219 aircraft.
- Collins Aerospace (RTX Corporation)
- Safran S.A.
- Diehl Stiftung & Co. KG
- Astronics Corporation
- SCHOTT AG
- Honeywell Aerospace Inc.
- Luminator Technology Group
- Bruce Aerospace Inc. (TransDigm Group)
- Cobalt Aerospace Group Limited
- S.E.L.A. Lighting Systems
- Soderberg Manufacturing Company, Inc.
- Prizm Aircraft Lighting
- Madelec Aero SAS
- Beadlight Limited
- Aveo Engineering Group, s.r.o.
- Heads Up Technologies, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY AND KEY FINDINGS
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth in aircraft deliveries and fleet expansion
- 4.2.2 LED adoption for lower power consumption and maintenance
- 4.2.3 Aircraft cabin modernization and retrofit programs
- 4.2.4 Passenger-experience differentiation through dynamic lighting
- 4.2.5 Plug-and-play certified retrofit kits reducing aircraft downtime
- 4.2.6 IoT-enabled smart lights enabling predictive maintenance
- 4.3 Market Restraints
- 4.3.1 High certification and integration costs
- 4.3.2 Aircraft weight, power, and thermal-management constraints
- 4.3.3 Cybersecurity and electromagnetic-compatibility validation for connected lighting
- 4.3.4 Capital reallocation toward IFEC/connectivity over lighting
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Aircraft Type
- 5.1.1 Fixed-Wing Aircraft
- 5.1.1.1 Commercial Aircraft
- 5.1.1.2 Business Jets and General Aviation Aircraft
- 5.1.1.3 Military Aircraft
- 5.1.2 Rotorcraft
- 5.1.1 Fixed-Wing Aircraft
- 5.2 By Light Type
- 5.2.1 Interior Lights
- 5.2.1.1 Passenger Cabin Lighting
- 5.2.1.2 Galley and Lavatory Lighting
- 5.2.1.3 Reading and Service Lighting
- 5.2.1.4 Emergency and Exit Lighting
- 5.2.1.5 Mood and Ambient Lighting
- 5.2.1.6 Other Interior Lighting
- 5.2.2 Exterior Lights
- 5.2.2.1 Navigation and Position Lights
- 5.2.2.2 Anti-Collision Lights
- 5.2.2.3 Landing and Taxi Lights
- 5.2.2.4 Other Exterior Lighting
- 5.2.3 Cockpit Lights
- 5.2.1 Interior Lights
- 5.3 By End User
- 5.3.1 OEM Linefit
- 5.3.2 Aftermarket/Retrofit
- 5.4 By Technology
- 5.4.1 LED
- 5.4.2 Conventional Lighting
- 5.4.3 Other Emerging Lighting
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 France
- 5.5.2.3 Germany
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Qatar
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Collins Aerospace (RTX Corporation)
- 6.4.2 Safran S.A.
- 6.4.3 Diehl Stiftung & Co. KG
- 6.4.4 Astronics Corporation
- 6.4.5 SCHOTT AG
- 6.4.6 Honeywell Aerospace Inc.
- 6.4.7 Luminator Technology Group
- 6.4.8 Bruce Aerospace Inc. (TransDigm Group)
- 6.4.9 Cobalt Aerospace Group Limited
- 6.4.10 S.E.L.A. Lighting Systems
- 6.4.11 Soderberg Manufacturing Company, Inc.
- 6.4.12 Prizm Aircraft Lighting
- 6.4.13 Madelec Aero SAS
- 6.4.14 Beadlight Limited
- 6.4.15 Aveo Engineering Group, s.r.o.
- 6.4.16 Heads Up Technologies, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

