PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154259

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154259
Fruit Fillings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
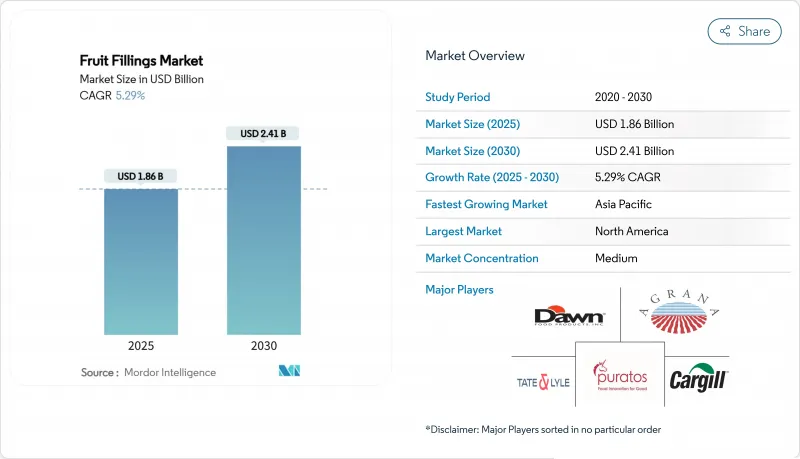
According to Mordor Intelligence, the fruit fillings market size is expected to grow from USD 1.86 billion in 2025 to USD 1.96 billion in 2026 and is forecast to reach USD 2.54 billion by 2031 at a 5.32% CAGR over 2026-2031.
Global Fruit Fillings Market Trends and Insights
Increasing Use of Fruit Fillings in Dairy and Frozen Desserts
The growing use of fruit fillings in dairy and frozen dessert products is emerging as a major growth driver for the fruit fillings market. Consumers are increasingly seeking products that combine indulgence with natural ingredients, prompting manufacturers to use fruit fillings to enhance flavor, texture, visual appeal, and perceived nutritional value. Fruit fillings also enable product differentiation through seasonal, premium, and mixed-fruit variants while supporting clean-label positioning by emphasizing the use of real fruit. As demand for premium yogurts, frozen yogurts, ice creams, and dairy desserts continues to rise, the demand for high-quality fruit fillings is expanding in parallel. This is reflected in new product launches across the dairy industry. In April 2025, Lactalis Canada, in collaboration with Nestle Canada, expanded the iOGO and iOGO nano brands into the frozen yogurt category with a portfolio of bars, tubs, and pops featuring flavors such as strawberry cheesecake, blueberry swirl, cherry swirl, mixed berry, and peach. The products were made with real fruit and introduced multiple fruit-based flavor formats across the range, demonstrating how fruit inclusions and fillings have become central to innovation in frozen dairy desserts. Such launches reinforce demand for specialized fruit fillings that provide consistent taste, appearance, and stability throughout processing and frozen storage, thereby supporting sustained growth of the fruit fillings market.
Expansion of Industrial, Convenience, and Ready-To-Eat Bakery Products
The expansion of industrial bakery manufacturing and rising consumption of convenience and ready-to-eat (RTE) bakery products are driving demand for fruit fillings worldwide. Packaged cakes, muffins, croissants, Danish pastries, pies, donuts, and snack bars increasingly rely on fruit fillings to enhance flavor, texture, moisture retention, and visual appeal, while ensuring consistency in large-scale production. As consumers seek convenient, premium, and on-the-go bakery options, manufacturers are expanding production of fruit-filled baked goods, creating sustained demand for bake-stable and shelf-stable fruit fillings that can withstand industrial processing and extended distribution. The growing scale of commercial bakery operations further reinforces this inclination. According to a 2025 United States Department of Agriculture (USDA) Foreign Agricultural Service (FAS) report, China had more than 338,000 bakery outlets as of May 2025. It also had 68.4% of bakery consumption linked to breakfast occasions, reflecting the increasing role of convenient bakery products in daily diets. The report also highlights the rapid expansion of retail bakery chains, supermarket bakeries, and cafe formats, all of which continue to introduce fruit-filled pastries and baked goods to meet evolving consumer preferences. As industrial bakery production expands globally and manufacturers diversify their ready-to-eat product portfolios, demand for high-performance fruit fillings is expected to grow steadily.
Seasonal Volatility in Fruit Supply and Crop Quality
Seasonal volatility in fruit supply and crop quality is a significant restraint for the fruit fillings market. Manufacturers depend on a consistent supply of high-quality fruits to maintain standardized flavor, texture, color, and processing performance. Weather variability, irregular rainfall, droughts, heatwaves, and crop diseases can reduce fruit yields and affect quality, making procurement more challenging and increasing raw material price volatility. These fluctuations can disrupt production planning and limit the availability of fruits suitable for commercial processing. Post-harvest losses across the fruit supply chain further compound this challenge. According to the Food and Agriculture Organization (FAO), 13.2% of food produced globally was lost between harvest and retail in 2024, with fruits and vegetables among the commodities most vulnerable to spoilage due to their perishability. Such losses reduce the availability of processing-grade fruits, increasing sourcing uncertainty and raw material costs for fruit filling manufacturers. As a result, producers may face supply constraints, inconsistent fruit quality, and pressure on operational efficiency and profit margins, particularly when relying on seasonal harvests and external supplier networks.
Other drivers and restraints analyzed in the detailed report include:
- Premiumization of Artisanal and Gourmet Bakery Offerings
- Growing Popularity of Seasonal and Exotic Fruit Flavors
- Short Shelf Life and Cold-Chain Dependence for Premium Formulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The without pieces segment accounted for the largest share of the fruit fillings market in 2025, capturing 55.64% of total revenue. Its dominance is driven by superior processing efficiency, consistent viscosity, and compatibility with high-speed depositing systems used in industrial bakery production. Homogeneous formulations ensure precise portion control and stable performance across applications such as croissants, doughnuts, confectionery centers, dairy products, and frozen desserts. Once integrated into commercial production lines, these formulations also benefit from high supplier retention due to stringent process validation requirements.
The with pieces segment is projected to register the fastest CAGR of 5.93% during 2026-2031, supported by rising demand for premium, artisanal, and visually differentiated food products. Bakers, cafes, and foodservice operators increasingly favor fillings containing visible fruit pieces to enhance product authenticity and consumer appeal. Manufacturers are responding by developing formulations that preserve fruit integrity while maintaining processing stability, including hybrid formats that combine a smooth fruit base with suspended fruit pieces. These innovations allow suppliers to address premium product demand without significantly increasing production complexity.
Complete Report Scope:
- By Product Type
- With Pieces
- Without Pieces
- By Fruit Category
- Berries
- Citrus Fruits
- Stone Fruits
- Tropical Fruits
- Other Fruit Categories
- By Distribution Channel
- Industrial
- Bakery and Pastry
- Dairy and Frozen Desserts
- Confectionery
- Beverages and Smoothies
- Other Industrial Applications
- Foodservice
- Retail
- Supermarkets and Hypermarkets
- Convenience Stores
- Online Retail
- Other Retail Channels
- Industrial
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Netherlands
- Poland
- Belgium
- Sweden
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Indonesia
- South Korea
- Thailand
- Singapore
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
- Middle East and Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
- Nigeria
- Egypt
- Morocco
- Turkey
- Rest of Middle East and Africa
- North America
Geography Analysis
North America accounted for the largest share of the fruit fillings market in 2025, representing 37.08% of global revenue. The region's position is supported by a mature industrial bakery sector, extensive supermarket and foodservice networks, and well-developed cold-chain infrastructure that enables the distribution of premium fruit fillings. High consumption of bakery, dairy, and frozen dessert products, combined with strong demand for convenience foods, continues to sustain market growth across the United States, Canada, and Mexico.
Asia-Pacific is projected to register the fastest CAGR of 6.21% during 2026-2031, driven by rapid urbanization, rising disposable incomes, and expanding consumption of packaged bakery and confectionery products. Countries such as China, India, Indonesia, and other Southeast Asian markets are investing heavily in food processing capacity while benefiting from abundant domestic production of tropical fruits. Growing local demand and improved processing capabilities are strengthening the region's position as both a major producer and consumer of fruit fillings.
Europe remains a technologically advanced and highly competitive market, supported by the presence of established fruit filling manufacturers and continuous product innovation. South America benefits from abundant fruit production and expanding exports of berry and stone fruit ingredients, reinforcing its role in the global supply chain. The Middle East and Africa is emerging as a promising market, driven by the growth of organized retail, hospitality, and quick-service restaurants, with increasing demand for shelf-stable and reduced-sugar fruit filling formulations.
- Puratos Group
- AGRANA Beteiligungs-AG
- Dawn Food Products Inc.
- Tate & Lyle
- Cargill, Incorporated
- Bakels Sweden
- Zeelandia International B.V.
- Zentis Fruchtwelt GmbH & Co. KG
- Aldia S.p.A.
- Andros Group
- Lemonconcentrate S.L.U.
- Barry Callebaut AG
- Bakels Group
- Frulact S.A.
- Zuegg S.p.A.
- PastryStar
- Cornaby's LLC
- Fuit Fillings, Inc.
- World of Chia
- VS Apple Industries B.V.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing use of fruit fillings in dairy and frozen desserts
- 4.2.2 Expansion of industrial, convenience, and ready-to-eat bakery products
- 4.2.3 Premiumization of artisanal and gourmet bakery offerings
- 4.2.4 Growing popularity of seasonal and exotic fruit flavors
- 4.2.5 Product innovation with new flavors, textures, and functional ingredients
- 4.2.6 Rising preference for natural colors and sweeteners
- 4.3 Market Restraints
- 4.3.1 Seasonal volatility in fruit supply and crop quality
- 4.3.2 Short shelf life and cold-chain dependence for premium formulations
- 4.3.3 Food safety, labeling, and export compliance burden
- 4.3.4 Formulation complexity in maintaining texture stability under freeze-thaw and bake-stable conditions
- 4.4 Supply Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Bargaining Power of Buyers
- 4.6.4 Threat of Substitutes
- 4.6.5 Industry Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 With Pieces
- 5.1.2 Without Pieces
- 5.2 By Fruit Category
- 5.2.1 Berries
- 5.2.2 Citrus Fruits
- 5.2.3 Stone Fruits
- 5.2.4 Tropical Fruits
- 5.2.5 Other Fruit Categories
- 5.3 By Distribution Channel
- 5.3.1 Industrial
- 5.3.1.1 Bakery and Pastry
- 5.3.1.2 Dairy and Frozen Desserts
- 5.3.1.3 Confectionery
- 5.3.1.4 Beverages and Smoothies
- 5.3.1.5 Other Industrial Applications
- 5.3.2 Foodservice
- 5.3.3 Retail
- 5.3.3.1 Supermarkets and Hypermarkets
- 5.3.3.2 Convenience Stores
- 5.3.3.3 Online Retail
- 5.3.3.4 Other Retail Channels
- 5.3.1 Industrial
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.1.4 Rest of North America
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 Italy
- 5.4.2.4 France
- 5.4.2.5 Spain
- 5.4.2.6 Netherlands
- 5.4.2.7 Poland
- 5.4.2.8 Belgium
- 5.4.2.9 Sweden
- 5.4.2.10 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 Australia
- 5.4.3.5 Indonesia
- 5.4.3.6 South Korea
- 5.4.3.7 Thailand
- 5.4.3.8 Singapore
- 5.4.3.9 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Colombia
- 5.4.4.4 Chile
- 5.4.4.5 Peru
- 5.4.4.6 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 South Africa
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 United Arab Emirates
- 5.4.5.4 Nigeria
- 5.4.5.5 Egypt
- 5.4.5.6 Morocco
- 5.4.5.7 Turkey
- 5.4.5.8 Rest of Middle East and Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Company Highlights, Core Segments, Financials (if available), Strategic Information, Market Share Analysis for key companies, Products, and Recent Developments)
- 6.4.1 Puratos Group
- 6.4.2 AGRANA Beteiligungs-AG
- 6.4.3 Dawn Food Products Inc.
- 6.4.4 Tate & Lyle
- 6.4.5 Cargill, Incorporated
- 6.4.6 Bakels Sweden
- 6.4.7 Zeelandia International B.V.
- 6.4.8 Zentis Fruchtwelt GmbH & Co. KG
- 6.4.9 Aldia S.p.A.
- 6.4.10 Andros Group
- 6.4.11 Lemonconcentrate S.L.U.
- 6.4.12 Barry Callebaut AG
- 6.4.13 Bakels Group
- 6.4.14 Frulact S.A.
- 6.4.15 Zuegg S.p.A.
- 6.4.16 PastryStar
- 6.4.17 Cornaby's LLC
- 6.4.18 Fuit Fillings, Inc.
- 6.4.19 World of Chia
- 6.4.20 VS Apple Industries B.V.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

