PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154292

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154292
Automotive Pump - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
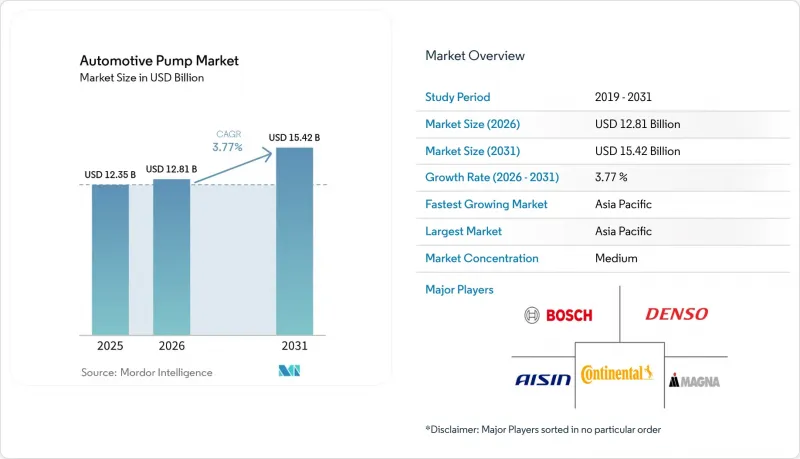
According to Mordor Intelligence, the automotive pump market size is projected to expand from USD 12.35 billion in 2025 to USD 12.81 billion in 2026, and to USD 15.42 billion by 2031, registering a CAGR of 3.77% during the forecast period (2026-2031).
Global Automotive Pump Market Trends and Insights
Tightening Global CO2 / CAFE Norms Accelerating E-Pump Adoption
Greenhouse gas regulations are the single most powerful catalyst for the automotive pump market. The U.S. EPA's Phase 3 standards, finalized in 2024, compel light-duty fleets to cut CO2 emissions by 56 g/mi by model year 2032, prompting OEMs to replace fixed-displacement coolant and oil pumps with variable-speed electric units that run only on demand . India's CAFE III rules, toughened in 2024, impose credit penalties for inefficient auxiliaries, and China's dual-credit policy awards compliance points when electric pumps are fitted even in hybrids. Decoupled coolant flow keeps HVAC and battery-pack temperatures stable during engine-off events, a requirement for start-stop, plug-in hybrids, and idle-reduction mandates. Consequently, nearly every new 800-volt EV platform launched in 2025-2026 specifies dual or triple electric coolant pumps sized from 150 W to 600 W.
Rapid Ramp-Up of Asia-Pacific ICE and EV Production Capacity
In the near future, the Asia-Pacific region is expected to dominate the automotive pump market with a significant share, driven by the establishment of new assembly lines. Recently, Stellantis made a substantial investment to modernize its plants in India and Indonesia, ensuring the production of localized pump modules in compliance with content regulations. Meanwhile, Chinese electric vehicle newcomer VinFast is setting up factories in ASEAN, necessitating the use of pre-validated thermal-management skids that seamlessly integrate pumps, valves, and reservoirs. Schaeffler's Integrated Coolant System, with plans to scale up production at its Xiangtan and Wuhu facilities by the end of the year, showcases the trend among suppliers to enhance value by consolidating multiple wet components into a single, coded assembly. The electrification of two-wheelers presents additional growth potential; a recent SAE paper underscores the use of forced-air and micro-liquid pumps in Indian e-scooters, signaling a shift of active thermal loops into more budget-friendly segments .
Upfront Cost Delta of Electric Versus Mechanical Pumps
OEMs remain hesitant to adopt electric pumps in entry-level vehicles, deterred by a significant price premium. Munro's 2024 teardown highlighted an electric coolant pump priced notably higher compared to its mechanical counterpart. Innovations like brushless-motor scaling, rare-earth-free magnets, and integrated electronics are gradually bridging this price divide. For instance, TI Fluid Systems' latest eCP family achieves a remarkably low sound level at minimal power consumption. However, achieving price parity within a close margin seems improbable in the near future. Consequently, in cost-sensitive markets such as India and Brazil, a blend of mechanical and electric units persists, hindering the full electrification of the automotive pump sector.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Power-Dense Turbo-Hybrid Engines
- OEM Preference for Integrated, Modular Pump Packages
- Global Aluminum Price Volatility Inflating Pump Housing Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fuel pumps accounts 33.14% of the share 2025 revenue, cementing their importance in gasoline direct-injection and diesel systems where pressures exceed 200 bar. The automotive pump market size for water pumps is projected to expand fastest, reflecting a 3.79% CAGR as 800-volt EVs and hydrogen ICE pilots demand multi-circuit cooling. Schaeffler's 260-W electric water pump now services range-extended EVs that outgrow earlier 150-W designs. Although oil pumps remain indispensable, steering pumps decline as electric power steering saturates. Vacuum pumps enjoy modest upside in hybrids that cannot rely on manifold vacuum.
Second-generation electric water pumps from Nidec GPM and Grayson Thermal Systems push flow beyond 100 L/min for buses and off-highway gear, illustrating how the automotive pump market is bifurcating between high-volume mechanical legacy and low-volume, high-margin electronic modules. Hydrogen injection, if commercialized, could reshape the supplier pecking order because ultra-high-pressure fuel pumps require fresh metallurgy and sealing expertise.
Mechanical units held 67.73% of the automotive pump market share in 2025, owing to their proven reliability and low cost. Electric counterparts grow at 3.92% CAGR through 2031, capturing margins with brushless motors and firmware upgrades. Automotive electric water pumps are gaining traction as OEMs increasingly use variable-speed coolant circulation to improve thermal efficiency and reduce parasitic energy losses. Bosch's PDE line spans 110-200 W, letting OEMs reuse the same casting with software tweaks. Europe leads penetration, Asia lags due to price sensitivity, and North America sits in between. A 2025 Applied Sciences study confirmed that 10-30 L/min liquid cooling is now viable even for e-motorcycles, foreshadowing wider adoption.
As battery-electric penetration climbs toward half in the early 2030s, the crossover where electric pumps exceed mechanical pumps in unit terms approaches. Suppliers scaling motor winding and embedded-control capacity earlier will lock in design wins, shaping the next decade of the automotive pump market.
Complete Report Scope:
- By Pump Type
- Fuel Pump
- Fuel Injection Pump
- Oil Pump
- Water Pump
- Steering Pump
- Windshield Washer Pump
- Vacuum Pump
- Others
- By Technology
- Mechanical Pumps
- Electric Pumps
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- Two-Wheelers
- Off-Highway Vehicles
- By Application
- Engine
- Transmission
- Cooling System
- Lubrication
- Windshield
- HVAC
- Others
- By Sales Channel
- OEM
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- Spain
- Italy
- France
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Indonesia
- Malaysia
- Singapore
- Vietnam
- Philippines
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific generated 42.36% revenue in 2025 and will expand 3.91% CAGR through 2031. China's dual-credit scheme incentivizes electric auxiliaries, while India's CAFE III regulations steer compact cars towards variable-speed pumps. Schaeffler's lines in Xiangtan and Wuhu produce significant volumes monthly, primarily for local range-extended EVs.
Even as diesel's prominence wanes, Europe retains its foothold through technological innovation. The C-Class EQ heat-pump HVAC from Mercedes sets a new standard with substantial energy reduction. Meanwhile, Continental's hydrogen hose plant in Korbach signals a strategic move towards alternative fuels. Although CBAM tariffs have driven aluminum casting operations to Turkey and Mexico, R&D remains firmly rooted in Germany and France.
North America's growth is tempered, primarily supported by ICE pickups but increasingly buoyed by a shift towards off-highway electrification. Evidence of this trend is seen in BorgWarner's long-term contract for off-highway controllers and Continental's significant investment in a hose plant in Mexico, both highlighting OEMs' focus on regional supply stability.
- Robert Bosch GmbH
- Denso Corporation
- Aisin Seiki Co. Ltd.
- Continental AG
- Magna International Inc.
- Mahle GmbH
- Hitachi Astemo Ltd.
- Johnson Electric Holdings Ltd.
- ZF Friedrichshafen AG
- Valeo SA
- BorgWarner Inc.
- Rheinmetall Automotive
- Schaeffler AG
- Toyota Industries Corporation
- Gates Corporation
- GMB Corporation
- Trico Products Corp.
- HELLA GmbH & Co. KGaA
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Tightening Global CO2 / CAFE Norms Accelerating E-Pump Adoption
- 4.2.2 Rapid Ramp-Up of Asia-Pacific ICE and EV Production Capacity
- 4.2.3 Shift Toward Power-Dense Turbo-Hybrid Engines Demanding High-Pressure Fuel and Oil Pumps
- 4.2.4 OEM Preference for Integrated, Modular Pump Packages
- 4.2.5 On-Board Diagnostics and Smart-Sensor Integration Enabling Predictive Maintenance
- 4.2.6 Hydrogen ICE Pilots Driving Ultra-High-Pressure Injection Pumps
- 4.3 Market Restraints
- 4.3.1 Upfront Cost Delta of Electric Versus Mechanical Pumps
- 4.3.2 Global Aluminum Price Volatility Inflating Pump Housing Costs
- 4.3.3 Decline in Diesel Vehicle Share in Europe
- 4.3.4 Tier-2 Recall Exposure from Counterfeit Aftermarket Parts
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Pump Type
- 5.1.1 Fuel Pump
- 5.1.2 Fuel Injection Pump
- 5.1.3 Oil Pump
- 5.1.4 Water Pump
- 5.1.5 Steering Pump
- 5.1.6 Windshield Washer Pump
- 5.1.7 Vacuum Pump
- 5.1.8 Others
- 5.2 By Technology
- 5.2.1 Mechanical Pumps
- 5.2.2 Electric Pumps
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Light Commercial Vehicles
- 5.3.3 Medium and Heavy Commercial Vehicles
- 5.3.4 Two-Wheelers
- 5.3.5 Off-Highway Vehicles
- 5.4 By Application
- 5.4.1 Engine
- 5.4.2 Transmission
- 5.4.3 Cooling System
- 5.4.4 Lubrication
- 5.4.5 Windshield
- 5.4.6 HVAC
- 5.4.7 Others
- 5.5 By Sales Channel
- 5.5.1 OEM
- 5.5.2 Aftermarket
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 Spain
- 5.6.3.4 Italy
- 5.6.3.5 France
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 India
- 5.6.4.2 China
- 5.6.4.3 Japan
- 5.6.4.4 Indonesia
- 5.6.4.5 Malaysia
- 5.6.4.6 Singapore
- 5.6.4.7 Vietnam
- 5.6.4.8 Philippines
- 5.6.4.9 South Korea
- 5.6.4.10 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 Turkey
- 5.6.5.4 Egypt
- 5.6.5.5 South Africa
- 5.6.5.6 Rest of Middle East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Robert Bosch GmbH
- 6.4.2 Denso Corporation
- 6.4.3 Aisin Seiki Co. Ltd.
- 6.4.4 Continental AG
- 6.4.5 Magna International Inc.
- 6.4.6 Mahle GmbH
- 6.4.7 Hitachi Astemo Ltd.
- 6.4.8 Johnson Electric Holdings Ltd.
- 6.4.9 ZF Friedrichshafen AG
- 6.4.10 Valeo SA
- 6.4.11 BorgWarner Inc.
- 6.4.12 Rheinmetall Automotive
- 6.4.13 Schaeffler AG
- 6.4.14 Toyota Industries Corporation
- 6.4.15 Gates Corporation
- 6.4.16 GMB Corporation
- 6.4.17 Trico Products Corp.
- 6.4.18 HELLA GmbH & Co. KGaA
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

