PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154301

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154301
Automotive Chassis - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the automotive chassis market size was valued at USD 161.25 billion in 2025, is estimated at USD 180.21 billion in 2026, and is projected to reach USD 278.65 billion by 2031, growing at a CAGR of 9.11% between 2026 and 2031.
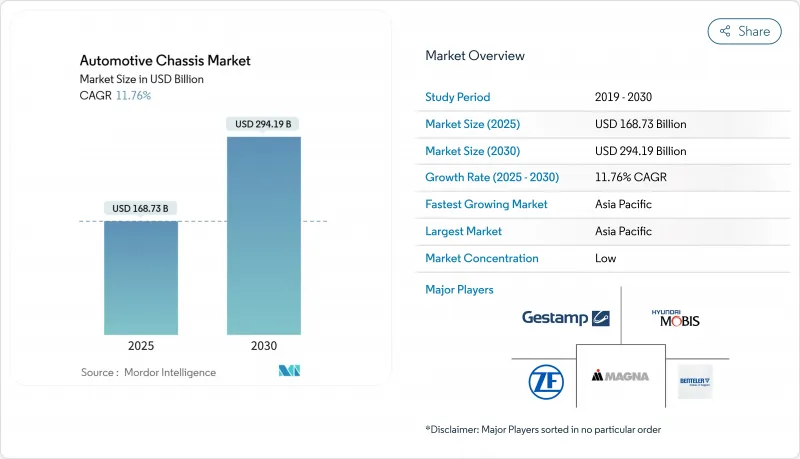
Global Automotive Chassis Market Trends and Insights
Surging EV Production Driving Skateboard/Platform Chassis
Battery electric architectures are increasingly adopting skateboard frames. These frames position batteries, e-motors, power electronics, and cooling circuits beneath flat floors. This innovation enhances cabin space and streamlines tool changeovers across derivative models. Rivian has ingeniously designed its carbon-fiber battery enclosure to serve as a torsion box, achieving significant weight reduction compared to traditional steel enclosures. Meanwhile, Hyundai Mobis showcased adaptable wheelbases, enabling a single production line to cater to both cars and crossovers. Suppliers specializing in structural adhesives and gap-filler pastes are securing new contracts. However, traditional stampers face potential displacement unless they acquire expertise in high-voltage isolation.
Lightweighting to Meet Fuel-Economy and EV-Range Targets
Stricter EU CO2 emission caps of 93.6 g/km for new passenger cars registered between 2025 and 2029 are compelling automakers to replace steel with aluminum and carbon fiber, despite rising raw material costs. GM's Ultium battery trays achieved significant weight reduction due to Novelis' Advanz 7-series alloy, resulting in improved range. Ford's F-150 Lightning benefited from substantial weight savings through the use of aluminum but faced higher procurement costs due to tariffs. SGL Carbon's thermoplastic composites can now be formed rapidly, but their premium price tag restricts their use to mainly premium trims.
High Capex for Composite and Multi-Material Manufacturing
Establishing greenfield composite lines involves significant investment, limiting operations to premium market segments. SGL Carbon highlights the substantial costs associated with setting up a single CFRP line. Meanwhile, Benteler faced delays in launching new programs despite additional investments in retrofits. Qualification cycles for composites subjected to ISO 14125 destructive testing are longer than those for steel. Furthermore, smaller tier-two players in emerging regions face challenges in securing patient capital.
Other drivers and restraints analyzed in the detailed report include:
- Megacasting and Structural Battery Packs Creating New Value Pools
- Tightening Crash-Safety Norms Elevating Material Complexity
- Raw-Material Price Volatility (Steel, Aluminum, CFRP)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Monocoque designs accounted for 68.15% of the automotive chassis market share in 2025, underscoring their crash energy efficiency and mass advantage for passenger cars. Ladder frames, though heavier, are forecast to grow at a 12.56% CAGR through 2031 as electric vans and Class 4-6 trucks adopt modular battery trays that bolt between longitudinal rails. The automotive chassis market size for ladder frames is projected to rise sharply as ride-hailing shuttles demand flat floors and quick battery swaps.
Advances in hot-stamping have enabled monocoques to reduce B-pillar thickness while maintaining side-impact performance, achieving significant weight savings per body-in-white. Rivian's Amazon delivery van has shown that ladder frames can be made lighter by incorporating composite cross-members, offering a substantial reduction compared to steel. This dual-track evolution has ensured high tooling utilization in the automotive chassis market, enabling suppliers to efficiently amortize press costs across SUVs and medium-duty chassis cabs.
Steel retained 66.33% of the automotive chassis market size in 2025 due to its significantly lower cost compared to aluminum and CFRP. However, carbon-fiber composite is expected to grow at a 14.38% CAGR between 2026 and 2031, driven by the increasing focus on weight reduction in EV programs. Aluminum alloys serve as a middle-ground material, particularly in battery enclosures, where they offer superior heat dissipation and reduce the need for active cooling systems.
SGL Carbon's thermoplastic CFRP under-body panels provide substantial weight savings and faster production times, although their higher cost limits widespread adoption. Advanced high-strength steels with improved strength and elongation properties are narrowing the weight gap, offering cost-conscious OEMs a practical solution to meet Euro NCAP 2026 standards without significant capital investments. These material advancements are expected to keep the automotive chassis industry diversified well into 2031.
Complete Report Scope:
- By Chassis Type
- Ladder Frame
- Monocoque
- By Material Type
- Steel
- Aluminum Alloy
- Carbon Fiber Composite
- Others
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles (LCVs)
- Medium and Heavy Commercial Vehicles (MHCVs)
- Buses and Coaches
- By Propulsion Type
- Internal Combustion Engine
- Battery Electric Vehicle (BEV)
- Plug-in Hybrid EV (PHEV)
- Hybrid Electric Vehicle (HEV)
- Fuel-Cell Electric Vehicle (FCEV)
- By Sales Channel
- OEM
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- Spain
- Italy
- France
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle-East and Africa
- North America
Geography Analysis
Asia-Pacific accounted for 49.28% of the automotive chassis market share in 2025 and is forecast to expand at a CAGR of 9.76% through 2031, driven by China's production of more than 9.5 million BEV units and foreign direct investment inflows into India's aluminum-intensive monocoque segment . Japan and South Korea leverage high-strength steel and carbon-fiber know-how, yet home-market stagnation caps output, pushing suppliers such as Toyota Boshoku and Aisin to export hybrid chassis kits.
North America faces Section 232 tariffs that have increased aluminum premiums, prompting OEMs to source from domestic smelters or absorb the additional costs. As fleets in the United States adopt electric Class 8 tractors, they are reaching gross-weight ceilings, driving the use of aluminum ladder frames. These frames cost significantly more than steel alternatives and compress ROI timelines. Europe faces similar dynamics. Stricter CO2 fleet targets have already driven substantial platform capital expenditure among German OEMs, including investments in Volkswagen's MEB and PPE skateboard chassis, which reduce part counts considerably.
South America and the Middle East & Africa collectively hold a modest slice of the automotive chassis market but post pockets of growth. Brazil's Rota 2030 tax credits are prompting Stellantis and GM to deploy flex-fuel hybrids with lightweight steel chassis, while Argentina's export-oriented ladder-frame plants are increasing pickup subframe shipments despite domestic volatility. South Africa exports vehicles equipped with galvanized frames designed for corrosive coastal conditions in target markets, including the United Kingdom and Australia.
- ZF Friedrichshafen AG
- Magna International Inc.
- Benteler International AG
- Hyundai Mobis Co., Ltd.
- Gestamp Automocion S.A.
- E&E Manufacturing
- Press Kogyo Co., Ltd.
- Tenneco Inc.
- Autocomp Corporation Panse Pvt Ltd (ACPPL)
- F&P America Mfg., Inc.
- ALF Engineering Pvt Ltd
- CIE Automotive
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging EV Production Driving Skateboard/Platform Chassis
- 4.2.2 Lightweighting to Meet Fuel-Economy and EV-Range Targets
- 4.2.3 Megacasting and Structural Battery Packs Creating New Value Pools
- 4.2.4 Tightening Crash-Safety Norms Elevating Material Complexity
- 4.2.5 Coastal-Region Corrosion-Resistance Demand-Boosting Coated Frames
- 4.2.6 Autonomous Shuttle "Pod" Designs Requiring Flat-Floor Chassis
- 4.3 Market Restraints
- 4.3.1 High Capex for Composite and Multi-Material Manufacturing
- 4.3.2 Raw-Material Price Volatility (Steel, Aluminum, CFRP)
- 4.3.3 EV Weight Pushing GVWR Limits, Hurting Fleet Economics
- 4.3.4 Skilled-Labor Shortages in Advanced Joining and Bonding
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Chassis Type
- 5.1.1 Ladder Frame
- 5.1.2 Monocoque
- 5.2 By Material Type
- 5.2.1 Steel
- 5.2.2 Aluminum Alloy
- 5.2.3 Carbon Fiber Composite
- 5.2.4 Others
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Light Commercial Vehicles (LCVs)
- 5.3.3 Medium and Heavy Commercial Vehicles (MHCVs)
- 5.3.4 Buses and Coaches
- 5.4 By Propulsion Type
- 5.4.1 Internal Combustion Engine
- 5.4.2 Battery Electric Vehicle (BEV)
- 5.4.3 Plug-in Hybrid EV (PHEV)
- 5.4.4 Hybrid Electric Vehicle (HEV)
- 5.4.5 Fuel-Cell Electric Vehicle (FCEV)
- 5.5 By Sales Channel
- 5.5.1 OEM
- 5.5.2 Aftermarket
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 Spain
- 5.6.3.4 Italy
- 5.6.3.5 France
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 India
- 5.6.4.2 China
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 Turkey
- 5.6.5.4 Egypt
- 5.6.5.5 South Africa
- 5.6.5.6 Rest of Middle-East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 ZF Friedrichshafen AG
- 6.4.2 Magna International Inc.
- 6.4.3 Benteler International AG
- 6.4.4 Hyundai Mobis Co., Ltd.
- 6.4.5 Gestamp Automocion S.A.
- 6.4.6 E&E Manufacturing
- 6.4.7 Press Kogyo Co., Ltd.
- 6.4.8 Tenneco Inc.
- 6.4.9 Autocomp Corporation Panse Pvt Ltd (ACPPL)
- 6.4.10 F&P America Mfg., Inc.
- 6.4.11 ALF Engineering Pvt Ltd
- 6.4.12 CIE Automotive
7 Market Opportunities & Future Outlook

