PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154319

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154319
Robotics Components - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
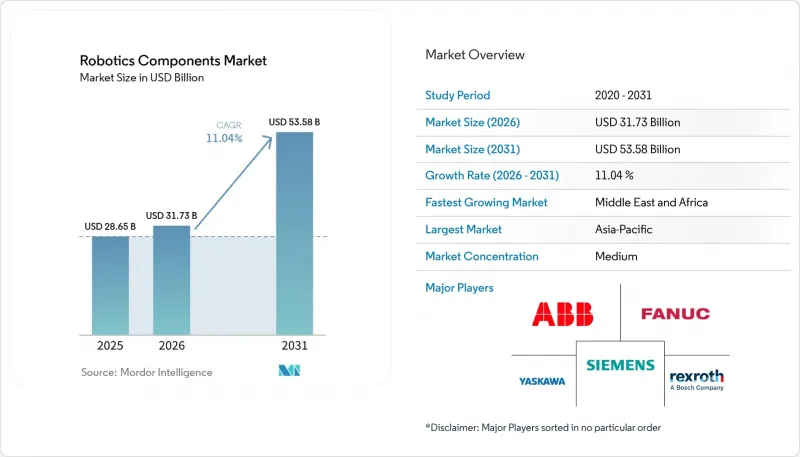
According to Mordor Intelligence, the robotics components market size is projected to expand from USD 28.65 billion in 2025 to USD 31.73 billion in 2026, and to USD 53.58 billion by 2031, registering a CAGR of 11.04% between 2026 and 2031.
Global Robotics Components Market Trends and Insights
Labor Shortages and Rising Manufacturing Wages
Demographic decline is creating durable demand for automation in several major manufacturing economies. South Korea, Japan, Germany, and China are facing smaller working-age populations while remaining major users of industrial robots. South Korea had the highest robot density worldwide, and the United States recorded 38,000 industrial robot installations in 2025, its third-highest annual total. These conditions make replacement of repetitive manual work a longer-term operating decision rather than a cyclical purchase. The Robotics components market benefits as more robots are installed, requiring motors, actuators, drives, and control electronics. Automation suppliers can therefore plan around demand from a wider group of plants, including facilities that have struggled to recruit and retain production workers.
AI-Enabled Perception and Edge Motion Control
Artificial intelligence is moving closer to the robot through embedded vision, control, and motion hardware. NVIDIA stated that its Cosmos 3 Edge policy model produces 32 robotic actions per inference at 15 Hz on Jetson Thor hardware. Bosch Rexroth added an optional Hailo-8 accelerator to its ctrlX COREplus platform for local machine vision and inspection workloads. Festo introduced GripperAI in June 2026 to identify gripping points for unfamiliar and randomly positioned items without prior programming or templates. For robotics components market suppliers, these capabilities raise demand for integrated sensors, processors, controllers, and end effectors, and they increase the value of systems designed for local processing. They also shift supplier competition toward component packages that can process data locally and respond quickly in unstructured settings.
High Upfront Cost and Lengthy Automation Payback
Capital costs remain a major obstacle for the robotics components market, particularly among small- and mid-sized manufacturers with shorter planning horizons. A six-axis industrial robot cell with vision, end effectors, and safety enclosures commonly requires USD 100,000 to USD 300,000 upfront. Payback can take 3 to 7 years, depending on utilization and labor savings. Robotics-as-a-service models reduce this barrier by shifting spending toward recurring operating payments. Warehousing and logistics providers represented 60% of North American robotics orders in the first quarter of 2026, partly reflecting subscription-based deployments. Specialized gearboxes, custom actuators, and tailored sensors remain less suited to service-based models, which continues to slow adoption in cost-sensitive applications.
Other drivers and restraints analyzed in the detailed report include:
- Reshoring, Nearshoring, and Factory Automation Incentives
- Expansion of High-Mix Electronics and Semiconductor Production
- Scarcity of Robotics Integration and Validation Talent
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Motors accounted for 19.75% of the Robotics components market share in 2025 because every robot type requires a source of joint torque and velocity. Servo motors and brushless direct-current motors are widely used across industrial, collaborative, and service robots. Machine vision systems are projected to expand at a 13.51% CAGR through 2031 as inspection moves from rule-based optics toward artificial intelligence-enabled 3D analysis. SICK released its Triton Floor-LOC localization system in June 2026, which combines camera position data and LiDAR into a single output for dynamic logistics environments. This move toward sensor fusion raises the technical content and value of vision systems. Sensors and end effectors also gain importance as collaborative and humanoid deployments require force feedback and flexible gripping.
Within the robotics components market, actuators, drives and controllers, power transmission components, control electronics, communication components, and power supplies account for the remaining revenue base. Nidec Drive Technology highlighted FLEXWAVE strain-wave and KINEX cycloidal gear architectures at Automate 2026 to address different payload needs. Bosch Rexroth said ctrlX OS supports application-based deployment of artificial intelligence vision and motion control workloads directly on the controller. Industrial Internet of Things architectures require dependable networking and uninterrupted power, while suppliers increasingly combine motor, gear, encoder, and sensing functions into a single actuator package. This integration increases unit value and makes separate component purchases less attractive for integrators working under time constraints.
Complete Report Scope:
- By Component
- Actuators
- Motors
- Drives and Controllers
- Sensors
- Machine Vision Systems
- End Effectors
- Power Transmission Components
- Control Electronics
- Power Supply Components
- Communication Components
- By Robot Type
- Industrial Robots
- Service Robots
- Collaborative Robots
- By End-user Industry
- Automotive
- Electronics and Semiconductors
- Healthcare and Medical Devices
- Aerospace and Defense
- Food and Beverage
- Logistics and Warehousing
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of the Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific accounted for 59.14% of revenue in 2025 because it is the largest installation region and an important production base for precision gearboxes, servo motors, and industrial sensors. Asia accounted for 79% of global industrial robot installations in 2025, and installations across the region increased 13%. China, Japan, and South Korea contributed the most to regional volumes. China has a cost advantage in standard motors and drive electronics, while Japan retains strength in precision strain-wave gearboxes and RV reducers. India is adding demand through electronics assembly and automotive production, while South Korea's automated electronics sector requires vision systems, sensors, and precision actuators.
North America and Europe are the next-largest demand areas in the robotics components market, but their current conditions differ. United States robot installations reached 38,000 units in 2025, up 11% from 2024. Warehousing and logistics providers represented 60% of North American orders in the first quarter of 2026. Canada recorded 6% growth in installations in 2025, while Mexico saw its third consecutive annual decline, and Europe's industrial robot installations fell 14% amid weaker investment, high energy costs, and challenging economic conditions. Updated machinery and cybersecurity requirements add costs for suppliers, although higher standards can protect established European vendors from lower-specification imports.
The Middle East and Africa are projected to expand at a 13.73% CAGR through 2031, the fastest regional pace in the robotics components market, as suppliers seek to capture demand in previously underserved geographies. Industrial diversification, e-commerce logistics investment, and local manufacturing development support demand, while Saudi Arabia's Vision 2030 and the United Arab Emirates' Dubai Robotics and Automation Program direct capital toward petrochemicals, food processing, and logistics. South America remains a smaller developing region led by Brazil and Argentina, where adoption is concentrated in automotive and food processing, and robotics-as-a-service can reduce initial costs for mid-sized food manufacturers. Infrastructure gaps and foreign exchange volatility still constrain purchasing decisions across much of the region.
- ABB Ltd.
- FANUC Corporation
- Yaskawa Electric Corporation
- Siemens AG
- Bosch Rexroth AG
- Harmonic Drive Systems Inc.
- Nabtesco Corporation
- Kollmorgen Corporation
- Maxon International AG
- Nidec Corporation
- SCHUNK SE & Co. KG
- ATI Industrial Automation, Inc.
- Festo SE & Co. KG
- SMC Corporation
- THK Co., Ltd.
- SICK AG
- Staubli International AG
- Parker Hannifin Corporation
- Rockwell Automation, Inc.
- OnRobot A/S
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Labor Shortages and Rising Manufacturing Wages
- 4.2.2 AI-Enabled Perception and Edge Motion Control
- 4.2.3 Reshoring, Nearshoring, and Factory Automation Incentives
- 4.2.4 Expansion of High-Mix Electronics and Semiconductor Production
- 4.2.5 Collaborative and Humanoid Robot Commercialization
- 4.2.6 Sensor Fusion for Autonomous Logistics and Inspection
- 4.3 Market Restraints
- 4.3.1 High Upfront Cost and Lengthy Automation Payback
- 4.3.2 Scarcity of Robotics Integration and Validation Talent
- 4.3.3 Precision Gearbox, Actuator, and Rare-Earth Supply Constraints
- 4.3.4 Functional Safety, Cybersecurity, and Liability Compliance Burden
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Actuators
- 5.1.2 Motors
- 5.1.3 Drives and Controllers
- 5.1.4 Sensors
- 5.1.5 Machine Vision Systems
- 5.1.6 End Effectors
- 5.1.7 Power Transmission Components
- 5.1.8 Control Electronics
- 5.1.9 Power Supply Components
- 5.1.10 Communication Components
- 5.2 By Robot Type
- 5.2.1 Industrial Robots
- 5.2.2 Service Robots
- 5.2.3 Collaborative Robots
- 5.3 By End-user Industry
- 5.3.1 Automotive
- 5.3.2 Electronics and Semiconductors
- 5.3.3 Healthcare and Medical Devices
- 5.3.4 Aerospace and Defense
- 5.3.5 Food and Beverage
- 5.3.6 Logistics and Warehousing
- 5.3.7 Other End-user Industries
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Rest of Asia-Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Middle East
- 5.4.5.1.1 Saudi Arabia
- 5.4.5.1.2 United Arab Emirates
- 5.4.5.1.3 Turkey
- 5.4.5.1.4 Rest of the Middle East
- 5.4.5.2 Africa
- 5.4.5.2.1 South Africa
- 5.4.5.2.2 Nigeria
- 5.4.5.2.3 Rest of Africa
- 5.4.5.1 Middle East
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 FANUC Corporation
- 6.4.3 Yaskawa Electric Corporation
- 6.4.4 Siemens AG
- 6.4.5 Bosch Rexroth AG
- 6.4.6 Harmonic Drive Systems Inc.
- 6.4.7 Nabtesco Corporation
- 6.4.8 Kollmorgen Corporation
- 6.4.9 Maxon International AG
- 6.4.10 Nidec Corporation
- 6.4.11 SCHUNK SE & Co. KG
- 6.4.12 ATI Industrial Automation, Inc.
- 6.4.13 Festo SE & Co. KG
- 6.4.14 SMC Corporation
- 6.4.15 THK Co., Ltd.
- 6.4.16 SICK AG
- 6.4.17 Staubli International AG
- 6.4.18 Parker Hannifin Corporation
- 6.4.19 Rockwell Automation, Inc.
- 6.4.20 OnRobot A/S
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

