PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154341

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154341
Retail Fuel Storage Tanks - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
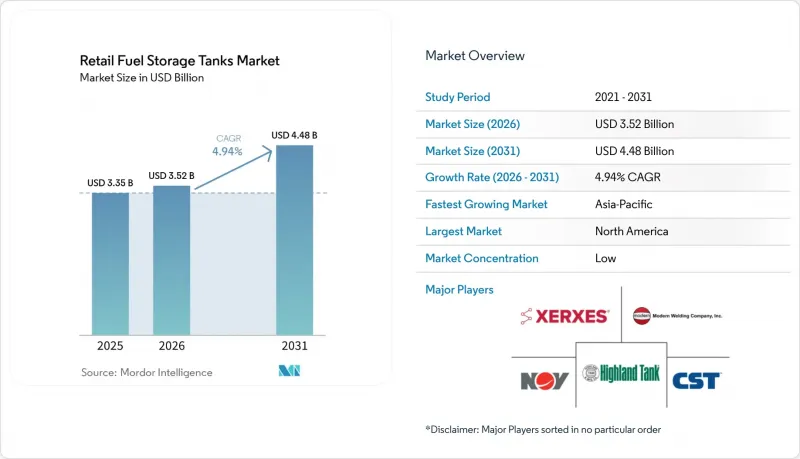
According to Mordor Intelligence, the retail fuel storage tanks market size is expected to grow from USD 3.35 billion in 2025 to USD 3.52 billion in 2026 and is forecast to reach USD 4.48 billion by 2031 at 4.94% CAGR over 2026-2031.
Global Retail Fuel Storage Tanks Market Trends and Insights
Aging Single-Wall UST Replacement Mandates Fuel Near-Term Demand
The retirement of single-wall underground storage tanks is a direct source of demand for the retail fuel storage tanks market. California required the permanent closure of noncompliant single-wall USTs by December 31, 2025. Since January 1, 2026, noncompliance has carried penalties of USD 500 to USD 5,000 per tank each day. The US Environmental Protection Agency reported in December 2024 that at least 7 states had incentive programs that paired financial support with upgrade or removal requirements. The agency's fiscal year 2025 performance reporting also found that double-wall systems had a lower release tendency than single-wall configurations. These rules shift purchasing toward pre-engineered double-wall units, especially where operators need to meet a defined closure date.
Multi-Fuel Retailing Drives Multicompartment Tank Demand
Retailers increasingly need to store regular, premium, mid-grade, ethanol-blended fuel, diesel, and renewable fuels at the same site. A multicompartment tank keeps several products within one structure and can reduce site footprint and equipment complexity. The retail fuel storage tanks market, therefore, benefits when new stations are designed for more than one liquid fuel category. Xerxes states that its fiberglass multicompartment tank uses a double-wall fiberglass bulkhead as a standard feature. US regulations require operators to give notice before switching to regulated substances containing more than 10% ethanol or 20% biodiesel. Operators must also demonstrate that the complete UST system is compatible with the new substance, which makes tank configuration part of the fuel change decision.
High Site-Disruption and Excavation Costs Throttle Replacement Velocity
Excavation and site restoration can cost more than the tank itself, which slows replacement activity at smaller sites. A February 2025 comparison prepared for Port San Luis showed USD 190,500 in excavation and dewatering costs for a 6,000-gallon UST replacement. The same document placed the total project estimate at USD 620,500 before considering the wider effect on station operations. This cost profile can defer compliance work where operators have limited capital or a narrow construction window. It can also make aboveground options more attractive at sites where local rules permit them. The retail fuel storage tanks market may see fewer projects from small independent retailers when civil works costs cannot be spread across a larger network. Larger chains have greater scope to coordinate upgrades, which can support consolidation in fuel retailing while narrowing the independent customer base.
Other drivers and restraints analyzed in the detailed report include:
- Convenience-Store Network Expansion in Asia-Pacific Anchors the Long-Term Volume Story
- Mainstream Adoption of Ethanol and Biodiesel Blends Demands Infrastructure Reconfiguration
- Retail-Fuel Demand Uncertainty from Vehicle Electrification Introduces Long-Range Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Double-wall tanks held 65.1% share in 2025 and are projected to grow at a 5.8% CAGR through 2031. Their position in the retail fuel storage tanks market reflects rules that favor secondary containment for new installations and replacement projects. California's single-wall closure requirement created an immediate reason for operators to procure compliant replacement equipment. Canada also updated the technical standards incorporated into its petroleum storage tank regulations in 2025. The retail fuel storage tanks market size for double-wall products is strengthened by both regulatory replacement and new-site construction.
Triple-wall tanks remain a specialized option for sites near sensitive groundwater or in jurisdictions with more demanding containment rules. Compartmented and jacketed variants become more relevant when stations offer several fuels from a constrained footprint. The European Commission adopted Implementing Decision 2026/989 in May 2026, updating the harmonized standard EN 13616-1:2025 for overfill-prevention devices on static liquid fuel tanks. The decision reinforces the importance of documented product compliance across new installations in member states. Suppliers must therefore compete on certification, installation support, and the ability to meet site-specific fuel and containment requirements.
Steel held 55.3% share by material in 2025. Its position in the retail fuel storage tanks market is supported by established manufacturing capacity, familiar installation practices, and broad fuel compatibility. STI/SPFA states that qualified steel tanks can be used with ethanol blends from E10 to E100 and biodiesel blends from B2 to B100. This makes steel a practical option for operators who expect future fuel blend changes. Steel also remains relevant in large capacity and aboveground applications where product strength and conventional fabrication are valued.
Fiberglass-reinforced plastic is the fastest-growing material category, with a forecast CAGR of 6.3% through 2031. Its corrosion resistance is important in aggressive soil environments and where long service life is a procurement priority. Xerxes offers fiberglass fuel tanks with multicompartment configurations and double-wall bulkheads. Mattr began production at new composite technology facilities in Blythewood, South Carolina, and Rockwall, Texas, in July 2024 under a USD 60 million growth investment. The Blythewood facility is expected to approach normalized production in 2026.
Complete Report Scope:
- By Tank Type
- Single-Wall Tanks
- Double-Wall Tanks
- Triple-Wall Tanks
- Other Tank Types
- By Tank Material
- Steel
- Fiberglass-Reinforced Plastic (FRP)
- Composite Materials
- Other Materials
- By Installation Type
- Underground Storage Tanks (USTs)
- Aboveground Storage Tanks (ASTs)
- By Tank Capacity
- Below 10,000 Gallons
- 10,000-20,000 Gallons
- 20,000-40,000 Gallons
- Above 40,000 Gallons
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- Italy
- Spain
- United Kingdom
- Poland
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Vietnam
- Thailand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- South Africa
- Morocco
- Rest of Middle East and Africa
- North America
Geography Analysis
North America held 31.4% share in 2025. California's enforcement action from January 1, 2026, is driving near-term procurement of compliant double-wall USTs and ASTs. The EPA identified state programs that combine financial support with upgrade or removal requirements. Canada gazetted amendments in September 2025 that updated technical standards for storage tank systems. Mexico adds demand at highway corridor stations where operators are adopting multi-fuel and larger-capacity storage to support cross-border logistics.
Asia-Pacific is the fastest-growing area in the retail fuel storage tanks market, at a forecast 6.7% CAGR through 2031. Sinopec issued tenders covering SF double-wall tanks in several sizes, including a Fujian procurement for 2025-2026. Japan requires internal coating, cathodic protection, or double-shell measures for underground tanks assessed as having high corrosion risk. Shell agreed in May 2025 to transfer its Indonesia gas station business and Gresik fuel storage terminal to a Citadel Pacific and Sefas joint venture. Chandra Asri Pacific agreed in October 2025 to acquire ExxonMobil's retail fuel stations in Singapore.
Europe retained a meaningful position in the retail fuel storage tanks market in 2025, with Germany, France, and Poland among the active installation markets. The European Commission's 2026 decision updated the harmonized standard for overfill-prevention devices on static liquid fuel tanks. This increases the need for current certification documentation on new product lines. The Middle East and Africa offer a longer-term opportunity as Saudi Arabia and the UAE upgrade retail networks, while foreign exchange volatility and financing constraints in South Africa can delay projects.
- Belco Manufacturing Company
- CST Industries, Inc.
- Eaton Sales & Service LLC
- Fiberglass Tank Solutions
- General Industries Co. Ltd.
- Granby Industries
- Highland Tank LLC
- KBK Industries
- Modern Welding Company, Inc.
- NOV Inc.
- Roben Manufacturing, Inc.
- Roth Industries GmbH & Co. KG
- Superior Tank Co., Inc.
- Tank Connection
- Tank Solutions Pty Ltd
- Western Global Limited
- Xerxes Corporation (Mattr)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging Single-Wall UST Replacement Mandates
- 4.2.2 Multi-Fuel Retailing Requires Multicompartment Tanks
- 4.2.3 Convenience-Store Network Expansion in Asia-Pacific
- 4.2.4 Mainstream Adoption of Ethanol and Biodiesel Blends
- 4.2.5 Digital Leak Detection and Remote Inventory Monitoring
- 4.2.6 California-Led Secondary-Containment Compliance Spillover
- 4.3 Market Restraints
- 4.3.1 High Site-Disruption and Excavation Costs
- 4.3.2 Permit and Contractor Bottlenecks for Tank Replacement
- 4.3.3 Corrosion and Compatibility Risk from New Fuel Blends
- 4.3.4 Retail-Fuel Demand Uncertainty from Vehicle Electrification
- 4.4 Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Tank Type
- 5.1.1 Single-Wall Tanks
- 5.1.2 Double-Wall Tanks
- 5.1.3 Triple-Wall Tanks
- 5.1.4 Other Tank Types
- 5.2 By Tank Material
- 5.2.1 Steel
- 5.2.2 Fiberglass-Reinforced Plastic (FRP)
- 5.2.3 Composite Materials
- 5.2.4 Other Materials
- 5.3 By Installation Type
- 5.3.1 Underground Storage Tanks (USTs)
- 5.3.2 Aboveground Storage Tanks (ASTs)
- 5.4 By Tank Capacity
- 5.4.1 Below 10,000 Gallons
- 5.4.2 10,000-20,000 Gallons
- 5.4.3 20,000-40,000 Gallons
- 5.4.4 Above 40,000 Gallons
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 France
- 5.5.2.3 Italy
- 5.5.2.4 Spain
- 5.5.2.5 United Kingdom
- 5.5.2.6 Poland
- 5.5.2.7 Russia
- 5.5.2.8 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Indonesia
- 5.5.3.7 Vietnam
- 5.5.3.8 Thailand
- 5.5.3.9 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Chile
- 5.5.4.4 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Egypt
- 5.5.5.4 South Africa
- 5.5.5.5 Morocco
- 5.5.5.6 Rest of Middle East and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Belco Manufacturing Company
- 6.4.2 CST Industries, Inc.
- 6.4.3 Eaton Sales & Service LLC
- 6.4.4 Fiberglass Tank Solutions
- 6.4.5 General Industries Co. Ltd.
- 6.4.6 Granby Industries
- 6.4.7 Highland Tank LLC
- 6.4.8 KBK Industries
- 6.4.9 Modern Welding Company, Inc.
- 6.4.10 NOV Inc.
- 6.4.11 Roben Manufacturing, Inc.
- 6.4.12 Roth Industries GmbH & Co. KG
- 6.4.13 Superior Tank Co., Inc.
- 6.4.14 Tank Connection
- 6.4.15 Tank Solutions Pty Ltd
- 6.4.16 Western Global Limited
- 6.4.17 Xerxes Corporation (Mattr)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

