PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154354

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154354
Biodegradable Scaffold - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the biodegradable scaffold market was valued at USD 0.61 billion in 2025 and is estimated to reach USD 0.68 billion in 2026. This report is Segmented by Product Type (Hydrogels, Polymeric Scaffolds, and More), Technology (3D Printing, and More), Material Type (Polylactic Acid (PLA), and More), Application (Orthopedics, Musculoskeletal, and Spine, and More), End-User (Hospitals and Diagnostic Centers, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
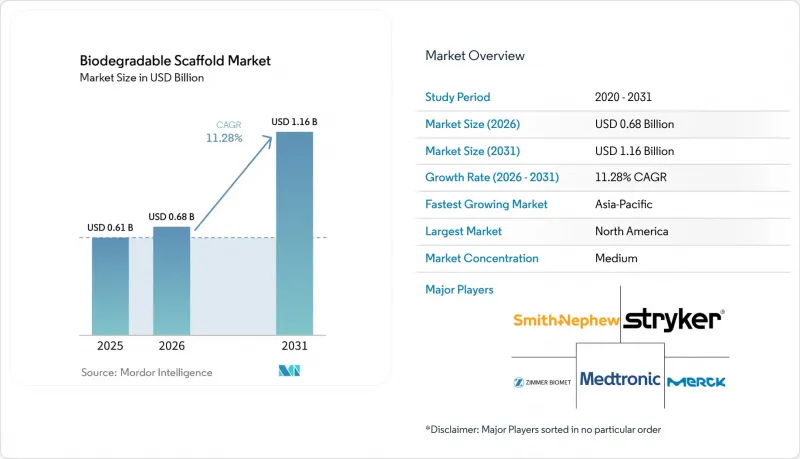
Global Biodegradable Scaffold Market Trends and Insights
Increasing Adoption of Regenerative Medicine and Tissue Engineering
Regenerative medicine has moved beyond experimental settings in several major markets. In September 2025, the FDA had received nearly 370 RMAT designation requests and had approved 184 requests. It had cleared 13 RMAT-designated products for marketing by June 2025. The FDA issued draft guidance on expedited programs for regenerative medicine in September 2025. The guidance supports shorter development pathways for qualifying therapies. Scaffold and matrix carriers can benefit as cell therapy programs progress through development. The Biodegradable scaffold market can therefore draw demand from a broader regenerative medicine pipeline.
Rising Orthopedic, Spine, Trauma, Chronic-Wound Burden, and Hospital Adoption
Orthopedic repair, spine procedures, trauma treatment, and chronic wounds create recurring requirements for biodegradable supports. Organogenesis stated that knee osteoarthritis affected 31 million Americans and could exceed 34 million by 2027. In April 2026, its 170-patient trial of PuraPly AM met the primary endpoint for diabetic foot ulcer closure at 12 weeks. The BEAR Implant provides a resorbable collagen scaffold for bridging torn ACL ends. It fully resorbs within 8 weeks. Hospitals can favor temporary implants when they fit established surgical workflows. This supports steadier procurement across wound, musculoskeletal, and spinal care.
Long Clinical Validation, Regulatory Classification, and Reimbursement Evidence
Regulatory classification uncertainty remains a material constraint for biodegradable scaffold developers. Biological components can place products under both medical device and advanced therapy pathways in Europe. This can extend development timelines by 3 to 5 years compared with predicate-based U.S. routes. Hyalofast had more than 15 years of clinical use in over 35 countries before its U.S. PMA filing process. Its Phase III study faced COVID-related disruptions and changes to the microfracture control arm. The need for clinical evidence, sterility validation, and payer support can raise development costs. These requirements can slow adoption in hospital systems with limited reimbursement headroom.
Other drivers and restraints analyzed in the detailed report include:
- 3D Printing, Patient-Specific Manufacturing, and GMP Outsourcing
- Translation of Scaffold-Based Cell, Drug-Delivery, and Organ-Repair Platforms
- Manufacturing Cost, Material Performance, and Lot-Release Variability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hydrogels accounted for 35.78% of product revenue in 2025. Their high water content and adjustable mechanical properties support cell encapsulation and drug delivery. Injectable formats can reduce the need for more invasive surgery. This can appeal to hospital committees that assess clinical workflow and resource use. Polymeric scaffolds serve orthopedic and spinal procedures that need defined structural performance. Bioactive glass-reinforced and composite products sit within the other product category. Isto Biologics acquired NovaBone Products in August 2026. NovaBone technology has been used in more than 2 million procedures across over 40 countries.
Nanofiber scaffolds are forecast to grow at 11.59% CAGR through 2031. This is the fastest product growth rate in the global category outlook. Commercial-scale electrospinning and additional regulatory clearances support this development. Atreon Orthopedics received FDA 510(k) clearance for BioCharge in February 2025. BioCharge is an electrospun PGA and PLCL nanofiber scaffold for rotator cuff repair. The company reported no adverse events at 5 months after implantation. Nanofiber structures can support cell attachment and controlled degradation. These attributes are relevant to tendon, nerve, and vascular repair. This product pathway strengthens the role of specialized fabrication in the biodegradable scaffold market.
3D printing held 39.52% of technology revenue in 2025. It leads the biodegradable scaffold market through a design process that connects imaging, optimization, fabrication, and validation. This can shorten development cycles relative to conventional fabrication. Synthetic fabrication serves cost-sensitive and high-volume orthopedic procedures. Electrospinning serves fibrous tissue applications that need extracellular matrix-like structures. Each technology addresses a distinct combination of cost, structure, and clinical use. The Biodegradable scaffold industry benefits when these platforms remain complementary rather than interchangeable. This allows suppliers to choose a process that fits a product's required architecture.
Decellularized technology is forecast to grow at 12.36% CAGR through 2031. It is the fastest-growing technology in the biodegradable scaffold market. A 2026 study reported more than 99.8% nuclei removal from lung scaffolds. The same work preserved collagen and elastin within 1 percentage point of native tissue. A 2025 review described the importance of combined physical and chemical methods for biosafe scaffolds with controlled immunogenicity. Greater protocol consistency can support GMP release and wider clinical use. Manufacturing scalability remains necessary for the technology to move beyond specialized applications.
Complete Report Scope:
- By Product Type
- Hydrogels
- Polymeric Scaffolds
- Nanofiber Based Scaffolds
- Others
- By Technology
- 3D Printing
- Decellularized Technology
- Synthetic Scaffold Fabrication
- Electrospinning
- Others
- By Material Type
- Polylactic Acid (PLA)
- Polyglycolic Acid (PGA)
- Polycaprolactone (PCL)
- Collagen
- Chitosan
- Others
- By Application
- Orthopedics, Musculoskeletal, and Spine
- Neurology
- Dental and Cranio-Maxillofacial
- Cardiology and Vascular
- Cancer and Disease Modeling
- Others
- By End-User
- Hospitals and Diagnostic Centers
- Biotechnology and Pharmaceutical Companies
- Academic Institutes and Research Laboratories
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 39.55% of global revenue in 2025. It was the largest regional revenue contributor. The U.S. system can adopt premium scaffold products when clinical evidence and reimbursement pathways are established. FDA 510(k) and PMA routes have created a regular flow of cleared scaffold products. This supports confidence in hospital procurement decisions. Europe was the second-largest regional market. Germany, the United Kingdom, and France were its principal volume centers. The MDR transition raised the evidence requirement for Class III scaffold products. This reduced the number of competing products and favored suppliers with strong clinical data packages.
Asia-Pacific is projected to grow at 14.83% CAGR through 2031. It is the fastest-growing regional part of the biodegradable scaffold market size. Japan's METI has tracked regenerative medicine supply chains as a strategic area. Satake MultiMix is building large-scale single-use bioreactor capacity in Saitama for completion in 2026. Japan's Sakigake designation can support the commercialization of innovative technologies. China is expanding domestic production through biotechnology initiatives. Its suppliers compete with imported products in commodity collagen and synthetic polymer categories. South Korea's engineering base and India's growing CDMO capacity add to the regional opportunity.
The Middle East and Africa and South America remain smaller regional opportunities. Saudi Arabia and the UAE are investing in healthcare infrastructure for orthobiologics and regenerative medicine. These investments can create early hospital demand that is currently served by imports. South Africa has the most developed regulatory environment for advanced medical products in the region. Brazil leads South America through its patient base, private hospital sector, and biomedical research activity. Argentina's evolving advanced-therapy regulations can open localized procurement opportunities. Pricing constraints remain an important barrier in both regions.
- 3D Biotek LLC
- 3DBioFibR Inc.
- Akron Biotech
- Atreon Orthopedics
- BellaSeno GmbH
- Corbion N.V.
- Evonik Industries
- Integra LifeSciences
- Medtronic
- Merck
- Molecular Matrix, Inc.
- NuVasive
- Onkos Surgical
- Organogenesis
- Orthofix
- Osteopore Limited
- Poly-Med, Inc.
- REVA Medical, Inc.
- Smith+Nephew plc
- Stryker
- Thermo Fisher Scientific
- Vericel
- Zimmer Biomet
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Adoption of Regenerative Medicine and Tissue Engineering
- 4.2.2 Rising Orthopedic, Spine, Trauma, and Chronic-Wound Burden
- 4.2.3 3D Printing and Patient-Specific Scaffold Manufacturing
- 4.2.4 Translation of Scaffold-Based Cell, Drug-Delivery, and Organ-Repair Platforms
- 4.2.5 GMP Outsourcing and CDMO Capacity Expansion for Clinical-Grade Scaffolds
- 4.2.6 Hospital Procurement Preference for Temporary, Resorbable Implants
- 4.3 Market Restraints
- 4.3.1 Long Clinical Validation and Regulatory Classification Cycles
- 4.3.2 High Cost of GMP Manufacturing, Sterility Assurance, and Reimbursement Evidence
- 4.3.3 Trade-Offs Between Mechanical Strength, Degradation Rate, and Biocompatibility
- 4.3.4 Lot-Release Variability from Biomaterial and Sterilization Sensitivity
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Hydrogels
- 5.1.2 Polymeric Scaffolds
- 5.1.3 Nanofiber Based Scaffolds
- 5.1.4 Others
- 5.2 By Technology
- 5.2.1 3D Printing
- 5.2.2 Decellularized Technology
- 5.2.3 Synthetic Scaffold Fabrication
- 5.2.4 Electrospinning
- 5.2.5 Others
- 5.3 By Material Type
- 5.3.1 Polylactic Acid (PLA)
- 5.3.2 Polyglycolic Acid (PGA)
- 5.3.3 Polycaprolactone (PCL)
- 5.3.4 Collagen
- 5.3.5 Chitosan
- 5.3.6 Others
- 5.4 By Application
- 5.4.1 Orthopedics, Musculoskeletal, and Spine
- 5.4.2 Neurology
- 5.4.3 Dental and Cranio-Maxillofacial
- 5.4.4 Cardiology and Vascular
- 5.4.5 Cancer and Disease Modeling
- 5.4.6 Others
- 5.5 By End-User
- 5.5.1 Hospitals and Diagnostic Centers
- 5.5.2 Biotechnology and Pharmaceutical Companies
- 5.5.3 Academic Institutes and Research Laboratories
- 5.5.4 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products & Services, and Recent Developments)
- 6.3.1 3D Biotek LLC
- 6.3.2 3DBioFibR Inc.
- 6.3.3 Akron Biotech
- 6.3.4 Atreon Orthopedics
- 6.3.5 BellaSeno GmbH
- 6.3.6 Corbion N.V.
- 6.3.7 Evonik Industries AG
- 6.3.8 Integra LifeSciences Holdings Corporation
- 6.3.9 Medtronic PLC
- 6.3.10 Merck KGaA
- 6.3.11 Molecular Matrix, Inc.
- 6.3.12 NuVasive, Inc.
- 6.3.13 Onkos Surgical
- 6.3.14 Organogenesis Holdings Inc.
- 6.3.15 Orthofix Medical Inc.
- 6.3.16 Osteopore Limited
- 6.3.17 Poly-Med, Inc.
- 6.3.18 REVA Medical, Inc.
- 6.3.19 Smith+Nephew plc
- 6.3.20 Stryker Corporation
- 6.3.21 Thermo Fisher Scientific Inc.
- 6.3.22 Vericel Corporation
- 6.3.23 Zimmer Biomet Holdings, Inc.

