PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154361

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154361
Private Networks For Ports - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
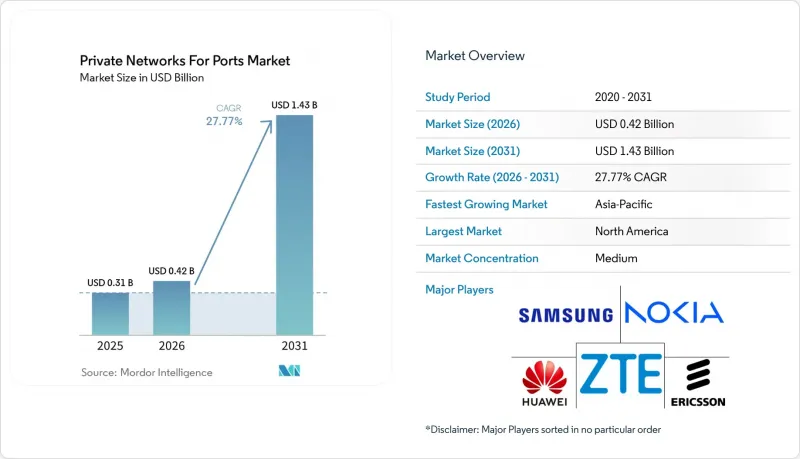
According to Mordor Intelligence, the private networks for Ports Market size was valued at USD 0.31 billion in 2025 and estimated to grow from USD 0.42 billion in 2026 to reach USD 1.43 billion by 2031, at a CAGR of 27.77% during the forecast period (2026-2031).
Global Private Networks For Ports Market Trends and Insights
Port Automation and Autonomous Equipment Adoption
The private networks for the ports market are advancing as terminal automation moves from isolated equipment projects to coordinated operating systems. Automated guided vehicles, rail-mounted gantry cranes, and yard optimization tools need dependable, low-latency communication to exchange positions, commands, and safety data. Konecranes completed live private 5G trials for automated rail-mounted gantry cranes in the third quarter of 2025, supporting the use of 5 G for remote and automated crane operations. The trials also provided terminal operators with a reference for assessing radio coverage, equipment response, and operational safety before replacing established control links. This relationship raises the cost of delaying network deployment because equipment investments cannot deliver their intended operating gains without a stable data layer. It also favors suppliers that understand crane controls, vehicle systems, terminal operating software, and radio networks.
Secure Low-Latency Connectivity for Mission-Critical Operations
The private networks for ports market benefits from demand for connectivity that stays available during safety-sensitive operations. The U.S. Department of Homeland Security reported in 2024 that surveyed ports did not regularly exercise transitions from digital to manual cargo processing, which makes resilient communications an important operational consideration. At the Port of Virginia, Verizon used licensed spectrum rather than General Authorized Access spectrum because nearby Navy and Coast Guard facilities could create channel competition. This decision shows that spectrum protection can matter as much as network speed when a site operates near critical public infrastructure. Dedicated networks also give port operators more control over traffic priorities and access policies than public wireless services. These benefits are most relevant when crane movements, vehicle routing, video feeds, and security systems must operate simultaneously.
High Upfront Deployment and Integration Costs
Private network projects require outdoor radios, a core network, edge computing, rugged devices, and integration with operational technology. These requirements can be difficult to fund when a port has not yet committed to automation programs that can produce measurable throughput or labor gains. At the Baltic Container Terminal in Riga, a private 5G installation replaced 22 legacy Wi-Fi towers with 2 antennas across a 50-hectare site after 12 months of radio planning. The case illustrates potential infrastructure savings, but it also shows the engineering effort required before implementation. Boldyn Networks and Nokia were selected in October 2025 to deploy and operate private 5G at OPCSA's Canary Islands terminal under a managed service structure. Such models can shift spending from a large initial investment toward recurring operating costs, although integration and cybersecurity validation still require time and specialist skills.
Other drivers and restraints analyzed in the detailed report include:
- Industrial IoT and Real-Time Video Analytics Expansion
- Local Spectrum Liberalization and Shared-Spectrum Availability
- Limited Harmonization of Local Spectrum Rules
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Private 5G held 56.78% of the technology segment in 2025 and is forecast to grow at a 28.04% CAGR through 2031. The technology supports high-capacity video, connected equipment, and multiple traffic classes across a single physical network. Standalone 5G cores can separate crane control, sensors, and video via logical network partitions, each with different quality requirements. The Private Networks for Ports Market size tied to private 5G is supported by ports that are planning full automation rather than isolated trials. Konecranes' 2025 trials for automated gantry cranes provided a practical reference point for terminals considering a move from LTE to 5G. The technology is especially relevant when traffic needs to remain predictable around moving equipment and large cargo stacks.
Private LTE remains useful where existing devices depend on LTE or where a staged migration can reduce transition risk. The Port of Virginia combined 5G Ultra Wideband small cells with an LTE packet core, preserving compatibility with existing LTE equipment while expanding its private network capabilities. This hybrid design reflects the varied device base across a terminal, including sensors, handhelds, vehicles, cameras, and control equipment. LTE can also be a practical option for ports with defined use cases that do not require the full capabilities of 5G. Over time, the balance will depend on device availability, safety requirements, and the pace of automation investment. The private networks for ports industry is therefore likely to retain LTE as an operational bridge even as 5G becomes the preferred basis for new large-site deployments.
Hardware accounted for 66.59% of the component segment in 2025. Radios, industrial devices, edge platforms, and core infrastructure form the physical foundation of a port-wide deployment. Nokia's installation at Maher Terminals combined its Digital Automation Cloud, MX Industrial Edge platform, rugged devices, device management software, and a Network Digital Twin. This bundled approach demonstrates that hardware contracts increasingly include software and data-management capabilities. Port conditions require equipment that can tolerate weather, vibration, dust, and large outdoor coverage areas. These requirements keep hardware spending significant even when the operator uses a managed commercial model.
Services are forecast to be the fastest-growing component at a 29.57% CAGR through 2031. Service providers can plan radio coverage, provision SIMs, optimize performance, monitor security, and coordinate incident response. Hughes and Celona announced a managed private wireless partnership in October 2025 that included SIM provisioning, performance optimization, and 24/7 threat detection. The model provides ports with access to private cellular capabilities when they lack internal network operations resources. Software remains the layer that links hardware data to automation systems, digital twins, and analytical tools. As a result, the Private Networks for Ports Market is shifting from equipment procurement toward long-term operating relationships, while hardware remains essential to site coverage.
Complete Report Scope:
- By Technology
- Private LTE
- Private 5G
- By Component
- Hardware
- Software
- Services
- By Deployment Model
- On-Premises and Isolated Non-Public Network
- Operator-Integrated Non-Public Network
- Hybrid Public-Private Network
- Network-as-a-Service
- By Spectrum
- Licensed Spectrum
- Shared Spectrum
- Unlicensed Spectrum
- By Port Type
- Container Ports
- Bulk Ports
- Multipurpose Ports
- Energy and Liquid Bulk Ports
- Inland Ports
- By Application
- Cargo Handling and Yard Automation
- Crane and Terminal Tractor Remote Control
- Autonomous Guided Vehicles and Truck Operations
- Asset Tracking and Positioning
- Worker Communications and Safety
- Video Analytics and Security
- Environmental Monitoring and Drone Inspection
- Port Traffic, Rail, and Vessel Management
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 84.12% of the Private Networks for Ports Market in 2025. The Port of Virginia deployed a dedicated Verizon private 5G network in 2024 as part of a USD 1.4 billion capital program covering its 6 terminals. The port processed 3.4 million TEUs in fiscal year 2025, indicating that the network operated at high throughput. The regional ecosystem gives operators access to vendors, shared-spectrum options, and integration capabilities that are still developing in many other locations. Canadian and Mexican adoption has remained focused on major gateways and cross-border logistics corridors.
Asia-Pacific is forecast to grow at a 29.69% CAGR through 2031. Automated-terminal programs in South Korea, Japan, India, and Singapore increase the need for reliable private wireless systems. The breadth of these programs gives the region a strong growth base, although national spectrum rules remain varied. Local requirements can increase the design work for operators with terminals in more than 1 country.
Europe holds a meaningful position in the Private Networks for Ports Market, with activity in Germany, the United Kingdom, Italy, and the Netherlands. Riga's 2025 private 5G deployment showed how a managed network can replace legacy wireless infrastructure at an active container terminal. The region's local licensing models can provide defined deployment routes, although rules vary across countries. South America and Africa remain early-stage adopters because uncertain spectrum access and high initial costs are difficult to absorb at lower-throughput sites.
- Telefonaktiebolaget LM Ericsson
- Nokia Corporation
- Verizon Communications Inc.
- Huawei Technologies Co., Ltd.
- Samsung Electronics Co., Ltd.
- Cisco Systems, Inc.
- ZTE Corporation
- NEC Corporation
- Siemens AG
- Hewlett Packard Enterprise Company
- Juniper Networks, Inc.
- Mavenir Systems, Inc.
- Airspan Networks Inc.
- Celona, Inc.
- Druid Software Limited
- Future Technologies Venture, LLC
- COCUS AG
- 2degrees Group Limited
- AT&T Inc.
- Deutsche Telekom AG
- Orange S.A.
- Vodafone Group Plc
- Tech Mahindra Limited
- Inseego Corp.
- Khasm Labs
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Port Automation and Autonomous Equipment Adoption
- 4.2.2 Secure Low-Latency Connectivity for Mission-Critical Operations
- 4.2.3 Industrial IoT and Real-Time Video Analytics Expansion
- 4.2.4 Local Spectrum Liberalization and Shared-Spectrum Availability
- 4.2.5 Port-Wide Digital Twin and Environmental Monitoring Programs
- 4.2.6 Seasonal Bandwidth Scaling Through Network-as-a-Service
- 4.3 Market Restraints
- 4.3.1 High Upfront Deployment and Integration Costs
- 4.3.2 Limited Harmonization of Local Spectrum Rules
- 4.3.3 Port-Specific Cybersecurity and Operational Technology Skills Gap
- 4.3.4 RF Complexity from Container Stacks, Cranes, and Metal Structures
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value-Chain Analysis
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology
- 5.1.1 Private LTE
- 5.1.2 Private 5G
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.2 Software
- 5.2.3 Services
- 5.3 By Deployment Model
- 5.3.1 On-Premises and Isolated Non-Public Network
- 5.3.2 Operator-Integrated Non-Public Network
- 5.3.3 Hybrid Public-Private Network
- 5.3.4 Network-as-a-Service
- 5.4 By Spectrum
- 5.4.1 Licensed Spectrum
- 5.4.2 Shared Spectrum
- 5.4.3 Unlicensed Spectrum
- 5.5 By Port Type
- 5.5.1 Container Ports
- 5.5.2 Bulk Ports
- 5.5.3 Multipurpose Ports
- 5.5.4 Energy and Liquid Bulk Ports
- 5.5.5 Inland Ports
- 5.6 By Application
- 5.6.1 Cargo Handling and Yard Automation
- 5.6.2 Crane and Terminal Tractor Remote Control
- 5.6.3 Autonomous Guided Vehicles and Truck Operations
- 5.6.4 Asset Tracking and Positioning
- 5.6.5 Worker Communications and Safety
- 5.6.6 Video Analytics and Security
- 5.6.7 Environmental Monitoring and Drone Inspection
- 5.6.8 Port Traffic, Rail, and Vessel Management
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Chile
- 5.7.2.4 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Spain
- 5.7.3.6 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 India
- 5.7.4.4 South Korea
- 5.7.4.5 Australia
- 5.7.4.6 Rest of Asia-Pacific
- 5.7.5 Middle East
- 5.7.5.1 United Arab Emirates
- 5.7.5.2 Saudi Arabia
- 5.7.5.3 Qatar
- 5.7.5.4 Rest of Middle East
- 5.7.6 Africa
- 5.7.6.1 South Africa
- 5.7.6.2 Egypt
- 5.7.6.3 Nigeria
- 5.7.6.4 Rest of Africa
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Telefonaktiebolaget LM Ericsson
- 6.4.2 Nokia Corporation
- 6.4.3 Verizon Communications Inc.
- 6.4.4 Huawei Technologies Co., Ltd.
- 6.4.5 Samsung Electronics Co., Ltd.
- 6.4.6 Cisco Systems, Inc.
- 6.4.7 ZTE Corporation
- 6.4.8 NEC Corporation
- 6.4.9 Siemens AG
- 6.4.10 Hewlett Packard Enterprise Company
- 6.4.11 Juniper Networks, Inc.
- 6.4.12 Mavenir Systems, Inc.
- 6.4.13 Airspan Networks Inc.
- 6.4.14 Celona, Inc.
- 6.4.15 Druid Software Limited
- 6.4.16 Future Technologies Venture, LLC
- 6.4.17 COCUS AG
- 6.4.18 2degrees Group Limited
- 6.4.19 AT&T Inc.
- 6.4.20 Deutsche Telekom AG
- 6.4.21 Orange S.A.
- 6.4.22 Vodafone Group Plc
- 6.4.23 Tech Mahindra Limited
- 6.4.24 Inseego Corp.
- 6.4.25 Khasm Labs
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

