PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154372

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154372
Private 5G System Integrator - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the private 5G system integrator market size was valued at USD 1.53 billion in 2025 and is estimated to grow from USD 2.21 billion in 2026 to reach USD 5.72 billion by 2031, at a CAGR of 20.95% during the forecast period 2026-2031.
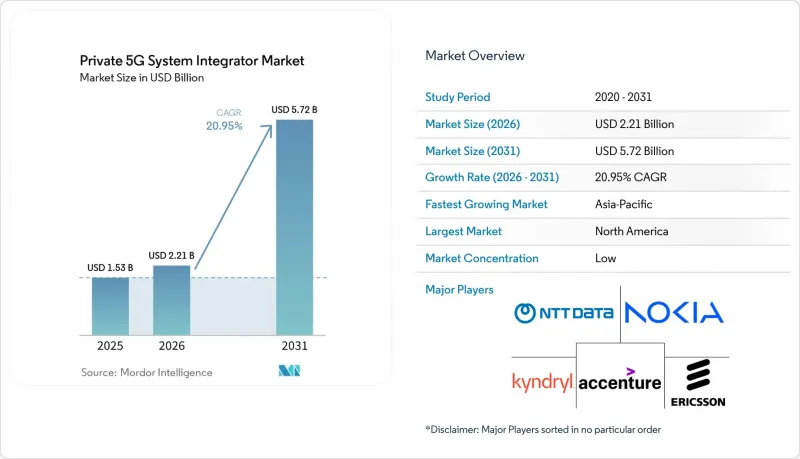
Global Private 5G System Integrator Market Trends and Insights
Industrial Automation and Smart Factory Rollouts
Industrial automation is a major driver of demand because manufacturers need reliable wireless connectivity for mobile equipment, sensors, and production systems. The Private 5G System Integrator Market benefits when enterprises expand a site pilot into a multi-location program. NTT DATA announced in February 2026 that its private 5G service covered 50 Cargill manufacturing and processing sites in the United States and Europe. Such programs require site design, device connection, application integration, and operational support at every location. They also require careful work with older factory equipment and industrial protocols such as Modbus, OPC UA, and Profinet. This gives integrators with industrial and network expertise a role throughout the deployment lifecycle.
Enterprise Demand for Secure, Low-Latency Mission-Critical Connectivity
Enterprises operating rail facilities, mines, utilities, and production plants need dependable local connectivity for time-sensitive activities. The Private 5G System Integrator Market addresses this need by connecting radio systems with security, device management, and local computing. GlobalLogic and Ericsson deployed a private 5G network at Hitachi Rail's 307,000-square-foot digital factory in Maryland in September 2025. The work included technical consulting, deployment, OT and IT integration, and lifecycle management. Verizon reported that private wireless can support operational efficiency when network services are connected with business operations. Full-scope integrators can maintain the network and adapt it as operational needs change.
High Upfront Deployment and Integration Costs
Upfront costs can delay private 5G decisions, especially when a customer already has a working Wi-Fi system. The challenge is greater at older industrial sites, where legacy controls can require custom integration and extended testing. Enterprises must assess the costs of spectrum, equipment, devices, security, support, and integration before approving a program. Smaller businesses can find the initial commitment particularly difficult. Managed service and as-a-service contracts can reduce the initial payment burden by aligning spending with operating needs. Providers must still avoid designs that become expensive to support after deployment.
Other drivers and restraints analyzed in the detailed report include:
- Cloud-Native 5G Standalone Cores and Edge Platforms
- Local and Shared Spectrum Liberalization
- Fragmented Spectrum Rules and Cross-Border Interoperability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Installation and integration services accounted for 47.21% of the Private 5G System Integrator Market size in 2025. This position reflects the substantial design and deployment work required as enterprises build private networks. The service typically includes site assessment, radio design, core setup, device connection, testing, and acceptance. Professional services also remain important because customers need planning and architecture support before deployment begins. These services are particularly relevant where an enterprise must connect legacy production equipment. They also help customers define the responsibilities of the operator, equipment supplier, and systems integrator.
Managed services are projected to grow at a 21.87% CAGR through 2031. The shift reflects customer interest in continuous performance management rather than a one-time delivery model. NTT DATA's private 5G deployment for Cargill covered 50 manufacturing and processing sites by February 2026. The company described the program as a fully managed service supporting several business and operational systems. For providers, repeatable service methods can improve consistency across locations. For customers, managed delivery can provide a single point of contact responsible for network availability and ongoing changes.
On-premises deployment accounted for 45.04% of the Private 5G System Integrator Market share in 2025, and it is favored by users who need close control over operational data and network performance. Defense, utilities, and petrochemical facilities often have requirements that favor local systems. Local deployment can also support applications that cannot accept delays from distant computing resources. These installations require the customer or integrator to manage a larger portion of the stack on-site. That requirement can increase the need for experienced engineering and operations teams.
Hybrid deployment is projected to grow at a 22.76% CAGR through 2031. It can keep sensitive and time-critical functions on-site while using cloud resources for analytics and broader coordination. In 2025, Mavenir reported that 48% of respondents identified private 5G as the most popular network edge cloud workload. This approach can help enterprises manage multiple sites without deploying every application to a remote cloud. Hosted services remain relevant for customers who prefer lower levels of internal infrastructure ownership. Each model requires careful definition of data paths, security responsibilities, and service levels.
Licensed spectrum accounted for 48.12% of the Private 5G System Integrator Market share in 2025, and it is expected to grow at a CAGR of 21.87% by 2031. Enterprises use licensed frequencies when they need predictable performance and stronger control over interference, which is important for applications with safety, production, and real-time communication requirements. Licensed deployments usually involve formal planning and coordination before the system becomes operational. That work can increase project complexity for the integrator. It can also support longer customer engagements because compliance and network operations must be maintained.
Shared spectrum provides an alternative for customers who cannot obtain dedicated frequencies or do not need them. It can be useful in industrial and healthcare settings that need private coverage without the cost of licensed access. Unlicensed 5G remains more limited and is best suited to controlled indoor environments. Germany's local spectrum program had issued 484 allocations by November 2025. This type of framework provides enterprises with a clearer path to dedicated spectrum. It also makes local regulatory expertise an important part of integration and delivery.
Complete Report Scope:
- By Offering
- Professional Services
- Installation and Integration Services
- Managed Services
- By Deployment Model
- On-Premise
- Hybrid
- Hosted
- By Spectrum Allocation
- Licensed Spectrum
- Shared Spectrum
- Unlicensed Spectrum
- By Frequency Band
- Low Band
- Mid Band
- mmWave
- By Network Architecture
- Standalone
- Non-Standalone
- By Cloud Model
- Private or Dedicated Cloud
- Public Cloud
- Hybrid Cloud
- By Enterprise Size
- Large Enterprises
- Small and Medium Enterprises
- By Industry Vertical
- Manufacturing and Factories
- Automotive
- Energy and Utilities
- Transportation and Logistics
- Mining and Oil and Gas
- Agriculture
- Media and Entertainment
- IT and Telecommunications
- Other Industry Verticals
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 74.23% of the Private 5G System Integrator Market share in 2025. The region benefits from a developed CBRS ecosystem, industrial investment, and demand from public-sector users. The United States has a broad base of manufacturing, transport, defense, and utility sites that can use private wireless systems. Canada is also developing industrial private 5G references. TERAGO and Ericsson launched a managed private 5G network at McMaster Manufacturing Research Institute in Canada in May 2026. The deployment supports AI-driven automation, robotics, real-time processing, and smart manufacturing applications.
Asia-Pacific is projected to expand at a 22.67% CAGR through 2031. Japan, South Korea, China, India, and Australia each provide demand through different industrial and policy conditions. South Korea has opened the 4.7 GHz and 28 GHz private 5G frequency bands to non-operator enterprises. Japan is building greater interoperability through its local 5G ecosystem. NTT EAST published results from 265 cross-vendor interconnection tests involving 26 participating companies in March 2026. This work can reduce integration difficulty for enterprises that need to connect equipment from different suppliers. The region's diversity means integrators must adjust their delivery model to each country.
Europe holds a significant position due to Germany's local spectrum framework and its industrial customer base. Germany's 484 local 5G spectrum allocations by November 2025 provide a clear foundation for campus deployments. The United Kingdom, France, Italy, and Spain also offer multi-country opportunities, but their national rules require local planning. South America, the Middle East, and Africa remain earlier-stage opportunities. Their demand is tied to mining, utilities, oil and gas, ports, and smart city programs. The Private 5G System Integrator Market has room to develop in these regions as spectrum access, skills, and enterprise use cases become more established.
- Accenture plc
- Cisco Systems, Inc.
- Hewlett Packard Enterprise Company
- International Business Machines Corporation
- Kyndryl Holdings, Inc.
- Nokia Corporation
- Telefonaktiebolaget LM Ericsson
- Huawei Technologies Co., Ltd.
- Samsung Electronics Co., Ltd.
- ZTE Corporation
- NEC Corporation
- Fujitsu Limited
- Siemens AG
- Deutsche Telekom AG
- Orange S.A.
- Vodafone Group Plc
- AT&T Inc.
- Verizon Communications Inc.
- NTT DATA Corporation
- Amazon Web Services, Inc.
- Microsoft Corporation
- Mavenir Systems, Inc.
- Rakuten Symphony Singapore Pte. Ltd.
- Celona, Inc.
- Federated Wireless, Inc.
- Betacom Incorporated
- Boingo Wireless, Inc.
- JMA Wireless, Inc.
- Tech Mahindra Limited
- Capgemini SE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Industrial Automation and Smart Factory Rollouts
- 4.2.2 Enterprise Demand for Secure, Low-Latency Mission-Critical Connectivity
- 4.2.3 Liberalization of Local and Shared Spectrum
- 4.2.4 Falling Prices of Industrial 5G Modules and Small Cells
- 4.2.5 Cloud-Native 5G Standalone Cores and Edge Platforms
- 4.2.6 Multi-Site Brownfield Integration Requirements
- 4.3 Market Restraints
- 4.3.1 Fragmented Spectrum Rules and Cross-Border Interoperability
- 4.3.2 High Upfront Deployment and Integration Costs
- 4.3.3 Shortage of Spectrum Engineering and Core Orchestration Skills
- 4.3.4 Unclear Return on Investment for Brownfield Retrofits
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value-Chain Analysis
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Offering
- 5.1.1 Professional Services
- 5.1.2 Installation and Integration Services
- 5.1.3 Managed Services
- 5.2 By Deployment Model
- 5.2.1 On-Premise
- 5.2.2 Hybrid
- 5.2.3 Hosted
- 5.3 By Spectrum Allocation
- 5.3.1 Licensed Spectrum
- 5.3.2 Shared Spectrum
- 5.3.3 Unlicensed Spectrum
- 5.4 By Frequency Band
- 5.4.1 Low Band
- 5.4.2 Mid Band
- 5.4.3 mmWave
- 5.5 By Network Architecture
- 5.5.1 Standalone
- 5.5.2 Non-Standalone
- 5.6 By Cloud Model
- 5.6.1 Private or Dedicated Cloud
- 5.6.2 Public Cloud
- 5.6.3 Hybrid Cloud
- 5.7 By Enterprise Size
- 5.7.1 Large Enterprises
- 5.7.2 Small and Medium Enterprises
- 5.8 By Industry Vertical
- 5.8.1 Manufacturing and Factories
- 5.8.2 Automotive
- 5.8.3 Energy and Utilities
- 5.8.4 Transportation and Logistics
- 5.8.5 Mining and Oil and Gas
- 5.8.6 Agriculture
- 5.8.7 Media and Entertainment
- 5.8.8 IT and Telecommunications
- 5.8.9 Other Industry Verticals
- 5.9 By Geography
- 5.9.1 North America
- 5.9.1.1 United States
- 5.9.1.2 Canada
- 5.9.1.3 Mexico
- 5.9.2 South America
- 5.9.2.1 Brazil
- 5.9.2.2 Argentina
- 5.9.2.3 Chile
- 5.9.2.4 Rest of South America
- 5.9.3 Europe
- 5.9.3.1 Germany
- 5.9.3.2 United Kingdom
- 5.9.3.3 France
- 5.9.3.4 Italy
- 5.9.3.5 Spain
- 5.9.3.6 Rest of Europe
- 5.9.4 Asia-Pacific
- 5.9.4.1 China
- 5.9.4.2 Japan
- 5.9.4.3 India
- 5.9.4.4 South Korea
- 5.9.4.5 Australia
- 5.9.4.6 Rest of Asia-Pacific
- 5.9.5 Middle East
- 5.9.5.1 United Arab Emirates
- 5.9.5.2 Saudi Arabia
- 5.9.5.3 Qatar
- 5.9.5.4 Rest of Middle East
- 5.9.6 Africa
- 5.9.6.1 South Africa
- 5.9.6.2 Egypt
- 5.9.6.3 Nigeria
- 5.9.6.4 Rest of Africa
- 5.9.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 Cisco Systems, Inc.
- 6.4.3 Hewlett Packard Enterprise Company
- 6.4.4 International Business Machines Corporation
- 6.4.5 Kyndryl Holdings, Inc.
- 6.4.6 Nokia Corporation
- 6.4.7 Telefonaktiebolaget LM Ericsson
- 6.4.8 Huawei Technologies Co., Ltd.
- 6.4.9 Samsung Electronics Co., Ltd.
- 6.4.10 ZTE Corporation
- 6.4.11 NEC Corporation
- 6.4.12 Fujitsu Limited
- 6.4.13 Siemens AG
- 6.4.14 Deutsche Telekom AG
- 6.4.15 Orange S.A.
- 6.4.16 Vodafone Group Plc
- 6.4.17 AT&T Inc.
- 6.4.18 Verizon Communications Inc.
- 6.4.19 NTT DATA Corporation
- 6.4.20 Amazon Web Services, Inc.
- 6.4.21 Microsoft Corporation
- 6.4.22 Mavenir Systems, Inc.
- 6.4.23 Rakuten Symphony Singapore Pte. Ltd.
- 6.4.24 Celona, Inc.
- 6.4.25 Federated Wireless, Inc.
- 6.4.26 Betacom Incorporated
- 6.4.27 Boingo Wireless, Inc.
- 6.4.28 JMA Wireless, Inc.
- 6.4.29 Tech Mahindra Limited
- 6.4.30 Capgemini SE
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

