PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154415

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154415
Semiconductor Assembly and Packaging Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
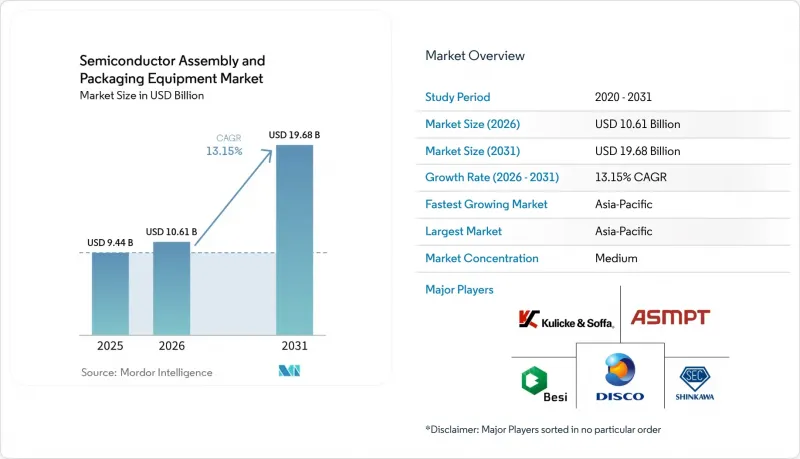
According to Mordor Intelligence, the semiconductor assembly and packaging equipment market was valued at USD 9.44 billion in 2025 and is estimated to grow from USD 10.61 billion in 2026 to reach USD 19.68 billion by 2031, registering a CAGR of 13.15% during the forecast period (2026-2031).
Global Semiconductor Assembly and Packaging Equipment Market Trends and Insights
Rising Demand for Advanced Packaging in AI, HPC, and Data Center Devices
AI infrastructure spending is increasing demand for advanced semiconductor assembly and packaging equipment across bonding, inspection, and wafer-level processing. Global semiconductor equipment billings reached USD 135.1 billion in 2025, up 15% from 2024, while assembly and packaging equipment billings grew 21%. GPUs, AI accelerators, and HBM stacks require more interconnect density than conventional wire-bond packages can provide. This requirement supports investment in advanced packaging lines for high-performance computing and cloud infrastructure. The semiconductor assembly and packaging equipment market, therefore, benefits from customer programs that involve longer tool qualification periods and more stable production roadmaps. These conditions strengthen the visibility of demand for suppliers already qualified on leading packaging lines.
Shift Toward Chiplet Architectures and Heterogeneous Integration
Chiplet designs require equipment capable of placing and connecting different die types with very fine tolerances. Thermo-compression bonding systems can achieve placement accuracy within 1 µm, which raises their value compared with conventional flip-chip tools. ASMPT secured an order for 8 chip-to-wafer thermo-compression bonding tools from a leading global IDM in June 2026 for chiplet-based client and data-center CPUs. Chiplet integration also adds more interfaces that need to be tested during qualification and yield ramp. This can extend equipment approval cycles from 6 months to 12-18 months. EV Group introduced its LITHOSCALE XT maskless exposure system in 2025 to address the needs of heterogeneous integration, fan-out wafer-level packaging, and AI or HPC patterning.
High Capital Intensity for Advanced Packaging Tooling
Advanced packaging lines require substantial spending on bonding, surface preparation, inspection, and cleanroom infrastructure. A CoWoS line expansion of 10,000 wafers per month can require USD 1.5-2.0 billion in capital expenditure. Hybrid bonding and high-end thermo-compression bonding platforms also cost much more than conventional wire-bond systems. Equipment makers must often support customer qualification for 6-18 months before a system generates production revenue. This financial and technical burden limits the number of operators that can move rapidly into leading-edge packaging. The semiconductor assembly and packaging equipment market is therefore split between large foundries, IDMs, and well-funded OSATs that can deploy advanced tools, and smaller firms that remain focused on established package types.
Other drivers and restraints analyzed in the detailed report include:
- HBM, 2.5D/3D Packaging, and Hybrid Bonding Capacity Expansion
- Capacity Localization Fueled by Semiconductor Sovereignty Programs
- Backend Supply-Chain Exposure to Export Controls and Precision Component Shortages
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Die bonders held the largest share of the semiconductor assembly and packaging equipment market, accounting for 30.55% in 2025. The segment supports conventional, flip-chip, and advanced packaging processes, including high-bandwidth memory and chiplet-based architectures. Its lead is reinforced by HBM production, which requires accurate die-to-die and die-to-wafer bonding. ASMPT reported USD 339 million in advanced packaging revenue in the first half of 2026, up 17% year over year, with thermo-compression bonding, high-precision SMT, and photonics systems among its main contributors. Wire bonding remains relevant in automotive power modules, RF front ends, LEDs, and other applications that favor established aluminum or copper wire processes. The semiconductor assembly and packaging equipment market size for die bonding is supported by the need to add more interconnect layers as package designs become denser.
Dicing and singulation equipment continues to benefit from the shift toward thinner, more fragile dies in 3D structures. DISCO reported FY2025 net sales of JPY 436.9 billion and an operating income margin of 42.3%, supported by demand for high-value-added products. Inspection and metrology are becoming more important as defects at hybrid-bonding interfaces can reduce yield. KLA expected advanced packaging revenue of USD 1 billion in fiscal 2026, compared with USD 635 million in 2025. In June 2026, Camtek received orders exceeding USD 105 million from a Tier-1 OSAT and a leading HBM manufacturer. Wafer thinning, backgrinding, and surface preparation also become increasingly important because 3D stacking requires wafers to be thinned before bonding.
Conventional packaging retained the largest installed base and a significant share of the semiconductor assembly and packaging equipment market in 2025. It continues to support consumer electronics, power devices, and IoT products where wire-bond and leadframe methods remain cost-effective. Flip-chip packaging also retains a substantial revenue role in smartphone processors, networking ASICs, and CPUs. ASMPT's February 2026 chip-to-wafer platform order showed that ultrafine-pitch bonding is increasingly important for advanced logic applications. Conventional formats are still growing in absolute demand, although a smaller portion of new capital spending is going to these tools.
Wafer-level and fan-out packaging are expanding as wearables, RF modules, and edge AI devices require higher I/O density in thinner packages. STMicroelectronics established a panel-level packaging pilot line in Tours, France, in 2025 for RF, analog, power, and microcontroller devices. The 2.5D and 3D packaging category has the highest equipment spending per unit because it needs multiple bonding, inspection, and thinning steps. Hybrid bonding and DBI are smaller in volume but are expected to grow fastest as HBM and logic-on-logic designs become more common. BE Semiconductor Industries projected hybrid-bonding revenue of EUR 476 million in 2026. System-in-Package tools also serve automotive, industrial IoT, and wearable health applications that combine analog, digital, and RF components.
Complete Report Scope:
- By Equipment Type
- Die Bonding Equipment
- Wire Bonding Equipment
- Flip-Chip and Thermo-Compression Bonding Equipment
- Wafer Bumping and Plating Equipment
- Dicing and Singulation Equipment
- Molding and Encapsulation Equipment
- Wafer Thinning, Backgrinding and Surface Preparation Equipment
- Inspection and Metrology Equipment
- Other Assembly and Packaging Equipment
- By Packaging Technology
- Conventional Packaging
- Flip-Chip Packaging
- Wafer-Level Packaging
- Fan-Out Packaging
- 2.5D/3D Packaging
- System-in-Package and Module Packaging
- Hybrid Bonding / Direct Bond Interconnect
- By End User
- Outsourced Semiconductor Assembly and Test Companies
- Integrated Device Manufacturers
- Foundries
- Research Institutes, Pilot Lines and Others
- By End-use Industry
- Computing, AI and Data Centers
- Consumer Electronics
- Automotive Electronics
- Telecommunications and Networking
- Industrial Electronics
- Aerospace and Defense
- Medical Devices
- Other End-use Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Rest of South America
- Europe
- Germany
- France
- Ireland
- Italy
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- Taiwan
- South Korea
- Japan
- Singapore
- Malaysia
- Philippines
- Vietnam
- India
- Rest of Asia-Pacific
- Middle East and Africa
- North America
Geography Analysis
Asia-Pacific held the largest share of the semiconductor assembly and packaging equipment market, accounting for 59.60% in 2025, and is projected to remain the fastest-growing region, at a 14.15% CAGR through 2031. Taiwan's total semiconductor equipment spending rose 90% to USD 31.5 billion in 2025 as TSMC increased CoWoS, SoIC, and co-packaged optics capacity. South Korea's spending rose by 26% to USD 25.8 billion, supported by investments in HBM production. China spent USD 49.3 billion on semiconductor equipment in 2025, although controls are directing some purchases toward domestic alternatives. Japan's equipment sales increased 22% to USD 9.5 billion in 2025. Malaysia, Vietnam, Singapore, the Philippines, and Thailand are also attracting OSAT capacity, which broadens regional equipment demand.
North America is expanding its advanced packaging base through public support and new investments by companies. The United States CHIPS Program Office had agreed, or had preliminarily agreed, to more than USD 34 billion in direct funding by June 2026. Amkor broke ground on its USD 7 billion packaging and test campus in Peoria, Arizona, in October 2025. The company acquired an additional 67-acre parcel near the campus in May 2026. North American semiconductor equipment spending declined by 20% to USD 10.9 billion in 2025, reflecting slower growth following earlier expansion. India is at an earlier stage, with packaging activity centered on mid-range devices and power applications.
Europe recorded USD 2.9 billion in semiconductor equipment spending in 2025, down 41% as automotive and industrial demand weakened. ESMC is preparing its Dresden fab for tool installation in the second half of 2026 and targets first wafer production in late 2027. The facility will serve automotive, IoT, and industrial markets. STMicroelectronics is also developing a panel-level packaging pilot line in France. The Netherlands remains important because of Besi's advanced position in the bonding equipment sector. South America, the Middle East, and Africa have limited direct demand for equipment, but Israel contributes to the global supply chain through manufacturing inspection equipment.
- ASMPT
- BE Semiconductor Industries N.V.
- Kulicke and Soffa Industries, Inc.
- DISCO Corporation
- Tokyo Seimitsu Co., Ltd. / ACCRETECH
- TOWA Corporation
- Shinkawa Ltd.
- Hanmi Semiconductor Co., Ltd.
- SUSS MicroTec SE
- EV Group
- Shibaura Mechatronics Corporation
- Yamaha Robotics / APIC Yamada
- Applied Materials, Inc.
- Tokyo Electron Limited
- SCREEN Holdings Co., Ltd.
- KLA Corporation
- Onto Innovation Inc.
- Camtek Ltd.
- ClassOne Technology
- Veeco Instruments Inc.
- Amtech Systems, Inc.
- Nordson Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Advanced Packaging in AI, HPC and Data Center Devices
- 4.2.2 Shift Toward Chiplet Architectures and Heterogeneous Integration
- 4.2.3 HBM, 2.5D/3D Packaging and Hybrid Bonding Capacity Expansion
- 4.2.4 Capacity Localization Fueled by Semiconductor Sovereignty Programs
- 4.2.5 Growth in Automotive, Power, RF and Reliability-Critical Packages
- 4.2.6 Greater Outsourcing to OSATs and Expansion of Captive Advanced Packaging by IDMs and Foundries
- 4.2.7 Increasing Need for Packaging-Level Inspection, Metrology and Process Control
- 4.3 Market Restraints
- 4.3.1 High Capital Intensity for Advanced Packaging Tooling
- 4.3.2 Qualification, Yield Ramp and Process Integration Complexity
- 4.3.3 Advanced Substrate, Interposer and Packaging Materials Constraints
- 4.3.4 Backend Supply-Chain Exposure to Export Controls and Precision Component Shortages
- 4.3.5 Skilled Labor Scarcity in Die Attach, Bonding, Inspection and Automation
- 4.3.6 Technology Obsolescence Risk Across Conventional Packaging Equipment
- 4.4 Value and Supply-Chain Analysis
- 4.4.1 Critical Component and Subsystem Suppliers
- 4.4.2 Packaging Materials and Substrate Suppliers
- 4.4.3 Assembly and Packaging Equipment OEMs
- 4.4.4 Automation, Inspection and Process Control Vendors
- 4.4.5 OSATs, IDMs and Foundries
- 4.4.6 End-Use Demand Verticals
- 4.4.7 Installation, Spares, Refurbishment and Aftermarket Services
- 4.5 Regulatory Landscape
- 4.5.1 Export Control and Trade Compliance
- 4.5.2 Environmental, Health, and Safety Standards
- 4.5.3 Semiconductor Localization and Incentive Policies
- 4.6 Technological Outlook
- 4.6.1 Hybrid Bonding and Thermo-Compression Bonding
- 4.6.2 Fan-Out, Wafer-Level and Panel-Level Packaging Automation
- 4.6.3 2.5D/3D Packaging, Interposers and Chiplet Integration
- 4.6.4 Wafer Thinning, Temporary Bonding and Debonding
- 4.6.5 AI-Enabled Inline Inspection and Process Control
- 4.6.6 Packaging-Level Metrology, X-Ray, Acoustic and Optical Inspection
- 4.7 Insights on Sustainability in Semiconductor Packaging
- 4.8 Patent and Innovation Analysis
- 4.9 Advanced vs Conventional Packaging Equipment
- 4.10 Packaging Technology Attractiveness Matrix
- 4.11 Equipment Demand by Device Category
- 4.12 Impact Assessment of Geopolitical Events on the Market
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Equipment Type
- 5.1.1 Die Bonding Equipment
- 5.1.2 Wire Bonding Equipment
- 5.1.3 Flip-Chip and Thermo-Compression Bonding Equipment
- 5.1.4 Wafer Bumping and Plating Equipment
- 5.1.5 Dicing and Singulation Equipment
- 5.1.6 Molding and Encapsulation Equipment
- 5.1.7 Wafer Thinning, Backgrinding and Surface Preparation Equipment
- 5.1.8 Inspection and Metrology Equipment
- 5.1.9 Other Assembly and Packaging Equipment
- 5.2 By Packaging Technology
- 5.2.1 Conventional Packaging
- 5.2.2 Flip-Chip Packaging
- 5.2.3 Wafer-Level Packaging
- 5.2.4 Fan-Out Packaging
- 5.2.5 2.5D/3D Packaging
- 5.2.6 System-in-Package and Module Packaging
- 5.2.7 Hybrid Bonding / Direct Bond Interconnect
- 5.3 By End User
- 5.3.1 Outsourced Semiconductor Assembly and Test Companies
- 5.3.2 Integrated Device Manufacturers
- 5.3.3 Foundries
- 5.3.4 Research Institutes, Pilot Lines and Others
- 5.4 By End-use Industry
- 5.4.1 Computing, AI and Data Centers
- 5.4.2 Consumer Electronics
- 5.4.3 Automotive Electronics
- 5.4.4 Telecommunications and Networking
- 5.4.5 Industrial Electronics
- 5.4.6 Aerospace and Defense
- 5.4.7 Medical Devices
- 5.4.8 Other End-use Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 France
- 5.5.3.3 Ireland
- 5.5.3.4 Italy
- 5.5.3.5 Netherlands
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Taiwan
- 5.5.4.3 South Korea
- 5.5.4.4 Japan
- 5.5.4.5 Singapore
- 5.5.4.6 Malaysia
- 5.5.4.7 Philippines
- 5.5.4.8 Vietnam
- 5.5.4.9 India
- 5.5.4.10 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 ASMPT
- 6.4.2 BE Semiconductor Industries N.V.
- 6.4.3 Kulicke and Soffa Industries, Inc.
- 6.4.4 DISCO Corporation
- 6.4.5 Tokyo Seimitsu Co., Ltd. / ACCRETECH
- 6.4.6 TOWA Corporation
- 6.4.7 Shinkawa Ltd.
- 6.4.8 Hanmi Semiconductor Co., Ltd.
- 6.4.9 SUSS MicroTec SE
- 6.4.10 EV Group
- 6.4.11 Shibaura Mechatronics Corporation
- 6.4.12 Yamaha Robotics / APIC Yamada
- 6.4.13 Applied Materials, Inc.
- 6.4.14 Tokyo Electron Limited
- 6.4.15 SCREEN Holdings Co., Ltd.
- 6.4.16 KLA Corporation
- 6.4.17 Onto Innovation Inc.
- 6.4.18 Camtek Ltd.
- 6.4.19 ClassOne Technology
- 6.4.20 Veeco Instruments Inc.
- 6.4.21 Amtech Systems, Inc.
- 6.4.22 Nordson Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

