PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154427

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154427
Cobalt Stearate - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
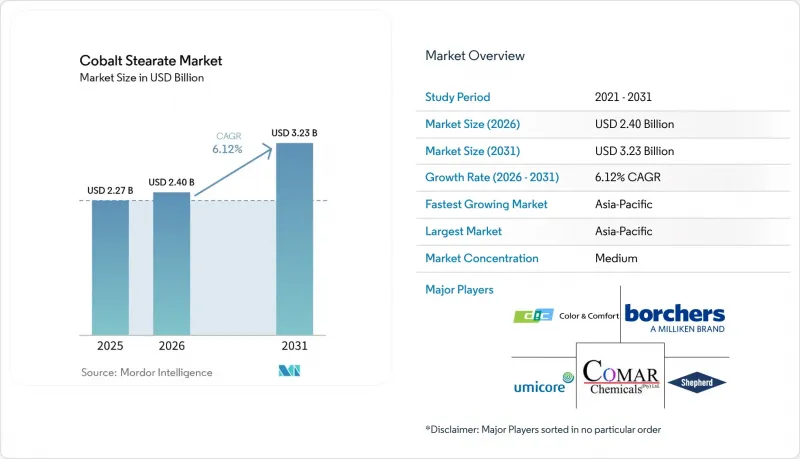
According to Mordor Intelligence, the cobalt stearate market size was estimated at USD 2.27 billion in 2025 and is estimated to grow from USD 2.40 billion in 2026 to USD 3.23 billion by 2031, at a CAGR of 6.12% during the forecast period (2026-2031).
Global Cobalt Stearate Market Trends and Insights
Expansion of Steel-Belted Radial Tire Production Anchors Baseline Demand
Steel-belted radial tires remain the primary end use for cobalt stearate worldwide. The cobalt stearate market benefits as commercial vehicle fleets in developing economies transition from bias-ply to radial tire construction. This shift extends demand across passenger and commercial tire categories in India and ASEAN markets. China produced 1.207 billion rubber outer tires in 2025, providing a large manufacturing base for materials used in tire construction. China also reported output of 149 million all-steel tires in 2025, a 7.19% increase from the prior year, with infrastructure and mining equipment supporting demand for all-steel tires. ISO 23475-2:2025 established a standardized pull-out test for steel tire-cord adhesion, reinforcing the need for reliable and precisely dosed adhesion-promoting materials. The resulting quality requirements make tire producers less willing to replace established adhesion systems without validated alternatives. The cobalt stearate market also benefits from the steady expansion of export-oriented radial capacity outside China, as these plants create demand for materials that can maintain rubber-to-metal bonding under demanding operating conditions.
Rising Demand for High-Performance Rubber Adhesion Extends Cobalt Stearate's Technical Utility
High-performance tire specifications require durable adhesion between rubber compounds and reinforcement materials. This requirement is especially relevant for premium consumer tires and original-equipment tire programs. Pirelli has reported more than 500 homologations for its Elect tire range since 2019, reflecting the scale of validation required for tires designed for electric and plug-in hybrid vehicles. These programs test rubber-cord bonding under higher torque loads and demanding operating conditions. The cobalt stearate market serves this need because cobalt-based adhesion systems remain well established in radial tire formulations. The same chemistry applies to conveyor belts, steel-braided rubber hoses, and off-highway equipment that use comparable rubber-to-metal bonding systems, broadening the customer base beyond passenger tire manufacturing. Consistency in cobalt content and material quality is important because end users must validate adhesion performance before changing formulations. The cobalt stearate market, therefore, holds a technical role that is difficult to replace in applications requiring long-term bond durability.
Cobalt Hazard Classification and Occupational-Exposure Compliance Raise Formulation and Handling Costs
Regulatory requirements for cobalt compounds are becoming more demanding for downstream formulators. In July 2025, the European Commission proposed an inhalable occupational exposure limit of 0.01 mg/m3 for cobalt and inorganic cobalt compounds, with a transitional limit of 0.02 mg/m3. It also proposed a respirable limit of 0.0025 mg/m3, a transitional limit of 0.0042 mg/m3, and a six-year adaptation period after adoption. Facilities that handle cobalt stearate for rubber compounding and as a packaging additive may need improved engineering controls and monitoring. Compliance requirements also affect chemical safety reporting and communication with downstream users. The cobalt stearate market incurs additional handling costs when materials are used in open powder systems. Closed handling, micropellets, and liquid dispersions can become more attractive because they reduce the risk of airborne cobalt particulate. These changes can alter the mix of forms sold into European production sites. The requirement can also influence purchasing decisions for non-European suppliers serving European customers. Formulation and process investments may raise costs, even as they create demand for safer handling formats.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Polyethylene Terephthalate (PET) Oxygen-Scavenging Packaging Diversifies the Demand Base
- Increasing Use of Precision-Engineered Metal Carboxylates Supports Higher-Value Demand
- Cobalt Price Volatility and Supply Concentration Compress Margins and Disrupt Planning Cycles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Industrial-grade accounted for 57.34% of the cobalt stearate market share in 2025, making it the largest segment. This position reflects the large quantity of material required for tire and rubber processing. High-purity grade is projected to grow at a CAGR of 6.86% from 2026 to 2031. PET packaging converters and specialty polymer compounders require tighter metal-content tolerances and lower heavy-metal contamination. The cobalt stearate market size for high-purity material is driven by applications where catalyst performance must remain stable at processing temperatures. Food-contact packaging also requires controls to limit the risks of yellowing and off-flavor. These requirements support a premium position for high-purity products. Industrial-grade material remains important because rubber compounding continues to be the anchor of demand for the cobalt stearate market.
Umicore's ECOS S 9.5 and ECOS S 9.5 V lines illustrate the use of specialized grades in oxygen-scavenging packaging. The bio-based fatty acid version addresses customer interest in sourcing practices and sustainability commitments. Technical grade sits between industrial and high-purity material, serving coatings producers that need reliable drier activity without the strict impurity requirements of food-contact packaging. During cobalt price increases, industrial-grade products can face greater substitution pressure from cobalt-free formulations. High-purity grades are less exposed to substitution where qualified alternatives cannot meet processing-temperature and clarity requirements. The difference in end-use requirements creates a clear split between high-quantity rubber products and higher-value specialty products. The cobalt stearate market retains both segments because their performance needs and purchasing criteria differ. Suppliers must therefore balance scale in industrial material with technical support for higher-purity customers.
Complete Report Scope:
- By Grade
- Industrial Grade
- High-Purity Grade
- Technical Grade
- By Form
- Powder
- Granules/Pellets
- Micropellets
- Liquid Dispersions and Customized Forms
- By Application
- Rubber and Tire Processing
- PET Oxygen Scavenging
- Paints and Coatings
- Plastics and Polymer Processing
- Others (Adhesives and Sealants, Printing Inks, Specialty Chemical and Catalyst Uses)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 36.13% of revenue in 2025 and is forecast to grow at a CAGR of 6.91% from 2026 to 2031. The region combines large tire manufacturing capacity, expanding PET packaging use, and developing cobalt supply chains. China's production of 1.207 billion units of rubber outer tires in 2025 provides a large base for cobalt stearate consumption. Japan produced 933,243 tons of tire rubber in 2025, an increase of 0.8% from the previous year and the first increase in four years. India is becoming a radial tire production hub through production incentives and original-equipment manufacturer localization, creating new demand for cobalt stearate in India and ASEAN markets. Asia-Pacific combines established Chinese scale with new manufacturing capacity across the region.
North America and Europe account for a smaller combined share of the cobalt stearate market but remain strategically important for high-value grades. North America benefits from domestic manufacturing capacity and automotive supply chains that require traceability documentation. Shepherd Chemical maintains a US-based presence in fatty acids and cobalt-based metal carboxylates, supporting regional tire and specialty chemical customers. Europe faces tighter occupational exposure and REACH requirements, increasing compliance needs for cobalt-containing materials. At the same time, electric-vehicle tire development supports demand for materials used in higher-performance tire compounds. Umicore reported strong profitability in its Specialty Materials activities in Q1 2026, supported by cobalt market conditions and demand for premium materials. These regions prioritize quality, traceability, and regulatory-ready product formats over scale.
South America, the Middle-East, and Africa are emerging demand areas for the cobalt stearate market. Brazil combines tire production capacity with growing demand for food and beverage packaging. Argentina supports polyethylene terephthalate (PET) oxygen scavenging through its agri-food packaging activity and the need for longer distribution distances. The Middle-East and Africa are linked to construction, mining, and commercial-vehicle activity. Saudi Arabia and South Africa are relevant markets where conveyor belts and other rubber goods support industrial activity. Infrastructure limitations and small local specialty-chemical distribution networks constrain more rapid adoption. These regions remain relevant as radialization and packaging growth can create incremental demand over time. Their opportunity is more localized than in Asia-Pacific but offers room for regional suppliers and distributors. Reaching these fragmented demand pockets will depend on customer access and technical service capabilities.
- Comar Chemicals
- Dalian Advance Performance Specialty Chemicals Co., Ltd.
- DIC CORPORATION
- Ege Kimya
- Guangsheng Xiangsu
- Jiangsu Yixing Kaou Chemical Co., Ltd.
- Jiangyin Sanliang Rubber & Plastic New Material Co., Ltd.
- Jinchuan Group International Resources Co. Ltd
- Milliken & Company
- Peter Greven GmbH & Co. KG.
- Shandong Yanggu Huatai Chemical Co., Ltd.
- Shepherd Chemical
- Sun Ace Kakoh (Pte.) Ltd.
- Umicore
- Wuhan Jiacheng Biotechnology Co., Ltd.
- Zibo Haiyue New Materials Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Steel-Belted Radial Tire Production
- 4.2.2 Rising Demand for High-Performance Rubber Adhesion
- 4.2.3 Growth of PET Oxygen-Scavenging Packaging
- 4.2.4 Increasing Use of Precision-Engineered Metal Carboxylates
- 4.2.5 Higher Adhesive Loading in Electric-Vehicle Tires
- 4.3 Market Restraints
- 4.3.1 Cobalt Hazard Classification and Occupational-Exposure Compliance
- 4.3.2 Cobalt Price Volatility and Supply Concentration
- 4.3.3 Substitution by Cobalt-Free and Low-Cobalt Adhesion Systems
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Grade
- 5.1.1 Industrial Grade
- 5.1.2 High-Purity Grade
- 5.1.3 Technical Grade
- 5.2 By Form
- 5.2.1 Powder
- 5.2.2 Granules/Pellets
- 5.2.3 Micropellets
- 5.2.4 Liquid Dispersions and Customized Forms
- 5.3 By Application
- 5.3.1 Rubber and Tire Processing
- 5.3.2 PET Oxygen Scavenging
- 5.3.3 Paints and Coatings
- 5.3.4 Plastics and Polymer Processing
- 5.3.5 Others (Adhesives and Sealants, Printing Inks, Specialty Chemical and Catalyst Uses)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Comar Chemicals
- 6.4.2 Dalian Advance Performance Specialty Chemicals Co., Ltd.
- 6.4.3 DIC CORPORATION
- 6.4.4 Ege Kimya
- 6.4.5 Guangsheng Xiangsu
- 6.4.6 Jiangsu Yixing Kaou Chemical Co., Ltd.
- 6.4.7 Jiangyin Sanliang Rubber & Plastic New Material Co., Ltd.
- 6.4.8 Jinchuan Group International Resources Co. Ltd
- 6.4.9 Milliken & Company
- 6.4.10 Peter Greven GmbH & Co. KG.
- 6.4.11 Shandong Yanggu Huatai Chemical Co., Ltd.
- 6.4.12 Shepherd Chemical
- 6.4.13 Sun Ace Kakoh (Pte.) Ltd.
- 6.4.14 Umicore
- 6.4.15 Wuhan Jiacheng Biotechnology Co., Ltd.
- 6.4.16 Zibo Haiyue New Materials Co., Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

