PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154455

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154455
Impingement Syndrome - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
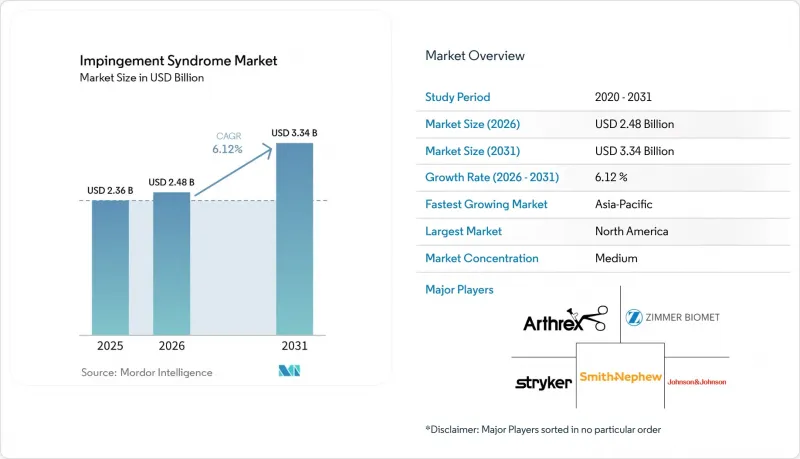
According to Mordor Intelligence, the impingement syndrome market is expected to increase from USD 2.36 billion in 2025 to USD 2.48 billion in 2026 and reach USD 3.34 billion by 2031, growing at a CAGR of 6.12% over 2026-2031.
Global Impingement Syndrome Market Trends and Insights
Rising Sports Participation and Overuse Injuries
The impingement syndrome market continues to benefit from repetitive overhead motion because athletic activity creates a steady stream of shoulder complaints that move patients into diagnosis, therapy, and follow-up care. A 2025 study among university athletes confirmed a statistically significant association between overhead athletic activities and shoulder impingement syndrome across age groups, which supports stable case generation in active populations. A related 2025 exercise study also showed measurable biomechanical risk in overhead athletes, which supports the demand for early rehabilitation protocols instead of waiting for more severe dysfunction to develop. Sport-specific loading patterns also matter because swimming, baseball, and racket sports do not place the same mechanical demands on the shoulder, and that keeps treatment protocols from becoming standardized too quickly. The result is that the impingement syndrome market draws repeat demand from both acute sports injuries and recurring overuse patterns that require monitoring over time.
Aging Population and Degenerative Shoulder Disorders
The impingement syndrome market is becoming more dependent on older adults because degenerative shoulder dysfunction is expanding the case base beyond sports injuries alone. A 2025 analysis of Global Burden of Disease patterns showed that musculoskeletal disorder incidence in China, Japan, and South Korea is expected to remain heavy through 2036 under the combined effect of age, period, and body mass index trends. European billing data published in 2024 also showed that degenerative shoulder conditions were concentrated in women and in people older than 60, with impingement-related presentations peaking in the 60 to 64 age group. Older patients also tend to move through longer conservative care pathways, which keeps imaging, medication, physiotherapy, and rehabilitation relevant even when surgery is not immediate. This leaves the impingement syndrome market with a broader and more persistent patient base, especially in countries where aging is already advanced.
Limited Reimbursement Clarity Across Markets
Reimbursement variation remains a direct brake on the impingement syndrome market because it affects who gets surgery, where the case is scheduled, and how much administrative effort is required before payment is secured. A separate 2025 reimbursement study reported that only 26.5% of 22-modifier shoulder surgery claims were successfully reimbursed, and that commercial payer success rates lagged far behind Medicare. These conditions lower willingness to take on more complex outpatient cases, even when ambulatory settings offer lower cost and faster throughput. Policy-driven documentation rules also slow movement from diagnosis to procedure, which spreads decision-making over a longer period and reduces same-pathway conversion. As a result, the impingement syndrome market can expand in value while still facing friction in the highest-revenue treatment setting.
Other drivers and restraints analyzed in the detailed report include:
- Earlier MRI and Ultrasound Based Diagnosis
- Rise in Arthroscopic and Minimally Invasive Shoulder Procedures
- Underdiagnosis of Non-Traumatic Shoulder Pain
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Primary impingement syndrome held 39.84% of the impingement syndrome market share in 2025, which reflected its position as the most familiar clinical presentation linked to structural narrowing, bursal irritation, and rotator cuff crowding. Its broad clinical visibility supports steady demand across examination, imaging, medication, physical therapy, and surgery, rather than concentrating value in a single point of care. Secondary impingement syndrome remains clinically distinct because instability, scapular dyskinesis, and neuromuscular dysfunction often require more layered management than classic structural narrowing alone. Acute impingement syndrome is projected to grow at a 6.64% CAGR through 2031, which reflects faster movement from sports injury to diagnosis and a shorter path into structured intervention.
This faster-growing acute category favors providers and device makers that can support rapid imaging, arthroscopic treatment, and closely supervised rehabilitation in the same care episode. The impingement syndrome industry, therefore, keeps its volume base in primary presentations, while growth leans toward cases that are diagnosed and escalated more quickly.
Adults held 42.63% share in 2025, which made them the largest age cohort across the impingement syndrome market because sports-related and occupational shoulder loading is concentrated in active working years. Adults also remain the most procedure-ready group because they are more likely to pursue imaging, injection therapy, and surgical resolution when symptoms interfere with work or routine function. Geriatric patients are projected to grow at an 8.67% CAGR through 2031, which reflects a broader structural shift toward degenerative shoulder disease and longer-duration care needs.
The adolescent segment remains the smallest by volume, but it is drawing more clinical attention as overhead athletic activity exposes younger patients to measurable biomechanical stress earlier in life. This keeps rehabilitation and prevention protocols important even when surgery is not the likely first-line route for younger patients. The impingement syndrome industry, therefore, has a volume center in adults and a growth frontier in older patients whose care pathways are often longer and more varied.
Complete Report Scope:
- By Type
- Primary Impingement Syndrome
- Secondary Impingement Syndrome
- Acute Impingement Syndrome
- By Patient Age Group
- Adolescents
- Adults
- Geriatrics
- By Component
- Treatment Type
- Surgical Treatment
- Non-Surgical Treatment
- Physical Therapy
- Medication
- Diagnosis
- Physical Examination
- Imaging Techniques
- Electromyography
- Treatment Type
- By End-User
- Orthopedic Clinics
- Ambulatory Surgical Centers
- Rehabilitation Centers
- Physiotherapy Clinics
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 45.08% of the impingement syndrome market share in 2025, which kept it as the largest regional contributor to revenue. High procedure volumes, broad commercial coverage for arthroscopic care, and a mature ambulatory surgery center network continue to support the region's leading position in the impingement syndrome market. In the United States, Smith & Nephew states that shoulder replacement procedures total 250,000 annually in 2025, which indicates the scale of the shoulder care base that supports adjacent impingement-related intervention. The concentration of advanced workflow launches in North America keeps the region at the center of premium competition, especially for robotics-enabled planning and shoulder surgery execution.
Asia-Pacific is projected to grow at a 9.28% CAGR through 2031, which makes it the fastest-growing regional block in the impingement syndrome market. A 2025 burden analysis showed that musculoskeletal disorder incidence in China, Japan, and South Korea is expected to remain heavy through 2036, which gives the region a strong aging-related demand base. South Korea also offers a clear signal of changing practice because a 2026 survey documented movement toward arthroscopic-first management in suitable cases. This means the region combines expanding patient need with evolving procedural readiness, rather than relying on only one of those growth factors.
Europe remains a meaningful revenue contributor, but growth is shaped more heavily by guideline-based conservative care and more varied reimbursement structures. Germany stands out within the region because degenerative shoulder disease remains widespread, and the shift from inpatient care toward outpatient settings is continuing. This keeps physiotherapy, rehabilitation, and imaging services important in Europe even when procedural growth is more measured than in faster-expanding regions. Middle East and Africa and South America remain smaller, but private orthopedic expansion and infrastructure investment keep long-term opportunities open for the impingement syndrome market.
- Arthrex
- B. Braun
- Bioventus Inc.
- Breg
- Conmed
- DJO Global
- Enovis Corporation
- Globus Medical
- Johnson & Johnson
- LimaCorporate S.p.A.
- Medtronic
- Orthofix
- OssDsign AB
- Ossur
- Smiths Group
- Stryker
- Wright Medical Group
- Zimmer Biomet
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Sports Participation and Overuse Injuries
- 4.2.2 Aging Population and Degenerative Shoulder Disorders
- 4.2.3 Earlier MRI and Ultrasound Based Diagnosis
- 4.2.4 Expansion of Outpatient Orthopedic Care
- 4.2.5 Rise in Arthroscopic and Minimally Invasive Shoulder Procedures
- 4.2.6 Tele-Rehabilitation and Home-Based Recovery Pathways
- 4.3 Market Restraints
- 4.3.1 Conservative Treatment Success Reduces Procedure Conversion
- 4.3.2 High Reliance on Clinical Judgment and Variable Coding
- 4.3.3 Limited Reimbursement Clarity Across Markets
- 4.3.4 Underdiagnosis of Non-Traumatic Shoulder Pain
- 4.4 Supply/Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Type
- 5.1.1 Primary Impingement Syndrome
- 5.1.2 Secondary Impingement Syndrome
- 5.1.3 Acute Impingement Syndrome
- 5.2 By Patient Age Group
- 5.2.1 Adolescents
- 5.2.2 Adults
- 5.2.3 Geriatrics
- 5.3 By Component
- 5.3.1 Treatment Type
- 5.3.1.1 Surgical Treatment
- 5.3.1.2 Non-Surgical Treatment
- 5.3.1.2.1 Physical Therapy
- 5.3.1.2.2 Medication
- 5.3.2 Diagnosis
- 5.3.2.1 Physical Examination
- 5.3.2.2 Imaging Techniques
- 5.3.2.3 Electromyography
- 5.3.1 Treatment Type
- 5.4 By End-User
- 5.4.1 Orthopedic Clinics
- 5.4.2 Ambulatory Surgical Centers
- 5.4.3 Rehabilitation Centers
- 5.4.4 Physiotherapy Clinics
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, Recent Developments)
- 6.3.1 Arthrex, Inc.
- 6.3.2 B. Braun SE
- 6.3.3 Bioventus Inc.
- 6.3.4 Breg, Inc.
- 6.3.5 CONMED Corporation
- 6.3.6 DJO, LLC
- 6.3.7 Enovis Corporation
- 6.3.8 Globus Medical, Inc.
- 6.3.9 Johnson and Johnson
- 6.3.10 LimaCorporate S.p.A.
- 6.3.11 Medtronic plc
- 6.3.12 Orthofix Medical Inc.
- 6.3.13 OssDsign AB
- 6.3.14 Ossur hf.
- 6.3.15 Smith & Nephew plc
- 6.3.16 Stryker
- 6.3.17 Wright Medical Group N.V.
- 6.3.18 Zimmer Biomet
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

