PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154458

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154458
CA 125 Test - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
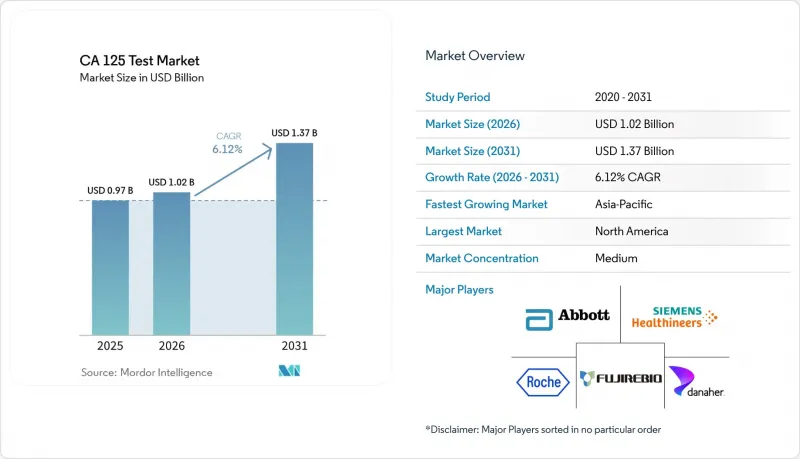
According to Mordor Intelligence, the CA 125 testing market is projected to be USD 0.97 billion in 2025, USD 1.02 billion in 2026, and reach USD 1.37 billion by 2031, growing at a CAGR of 6.12% from 2026 to 2031.
Global CA 125 Test Market Trends and Insights
Rising Ovarian Cancer Surveillance Demand
The 330,731 ovarian cancer cases recorded globally in 2024 provide a large base for ongoing clinical monitoring. A 2026 projection estimated that annual global cases could reach 477,000 by 2050. In the United States, Medicare coverage recognizes CA 125 for specified ovarian and primary peritoneal carcinoma indications. The coverage framework supports repeat testing after therapy, which makes demand less dependent on a single clinical visit. The CA 125 testing market, therefore, relies on established care pathways as well as new diagnostic demand. Rising patient numbers could increase the number of patients who enter these follow-up pathways across high-income and emerging health systems.
Expansion of Automated Immunoassay Menus in Core Laboratories
Automated platforms allow laboratories to run CA 125 within wider tumor-marker menus from a single blood sample. Siemens Healthineers offers CA 125 testing on its Atellica platform, and Roche offers the Elecsys CA 125 II assay within its laboratory diagnostics portfolio.This model reduces the operational burden of adding a test once an analyzer has already been installed. It can also make CA 125 easier to order with other tumor markers when clinicians require a broader laboratory assessment. Japan's health ministry sets reimbursement and laboratory diagnostics policies that shape the adoption environment for automated testing. The CA 125 testing market is supported when laboratories replace smaller systems with high-throughput analyzers that have established tumor-marker menus.
Limited Test Specificity in Benign Gynecologic Conditions
CA 125 levels can be elevated in benign conditions, including endometriosis, fibroids, and pelvic inflammatory disease. This limits the test's diagnostic specificity, particularly for premenopausal women. A 2025 external validation study examined CA 125 and age-based models in 342,278 women tested in English primary care. Age-adjusted thresholds improved specificity compared with a fixed 35 U/mL cutoff, but performance remained lower in women under 50. False-positive results can lead to additional imaging, specialist referrals, and sometimes laparoscopy. This may limit clinician confidence in standalone CA 125 testing for lower-risk patients and supports the move toward panel-based assessment.
Other drivers and restraints analyzed in the detailed report include:
- Bundling of CA 125 With HE4 and ROMA Workflows
- AI-Enabled Reflex Testing and Result Triage
- Low Sensitivity for Early-Stage Ovarian Cancer Detection
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Analyzers and instruments accounted for 52.42% of the CA 125 testing market size in 2025. This position reflects the cost of high-throughput and semi-automated immunoassay equipment used by laboratories. An installed analyzer can create ongoing demand for compatible reagents and consumables. That relationship gives established platform suppliers recurring revenue from their existing laboratory base.
Reagents and kits are forecasted to grow at a 6.47% CAGR through 2031, the fastest rate among product categories. The growth outlook reflects the expansion of CA 125 menus on installed systems and more frequent testing within multi-marker pathways. European in vitro diagnostic rules also increase documentation demands for suppliers that seek to register relevant products in the region.
Automated immunoassay systems held 43.53% of the CA 125 testing market share in 2025. These systems are used in laboratories that process many analytes and require standardized workflows. CA 125 can be run with other tumor markers on the same platform, which supports routine laboratory use.
Semi-automated immunoassay systems are forecasted to grow at a CAGR of 7.23% through 2031. Their expansion is driven by the increasing demand for cost-effective and rapid CA 125 testing in community hospitals, diagnostic centers, and decentralized laboratory settings. These systems offer a practical balance between automation and affordability, making them attractive for routine ovarian cancer monitoring and follow-up testing. Growth is particularly strong in emerging healthcare markets, although fully automated platforms remain the preferred choice in large reference laboratories due to their higher throughput and workflow efficiency.
Complete Report Scope:
- By Product Type
- Reagents and Kits
- Analyzers and Instruments
- By Technology
- Automated Immunoassay Systems
- Semi-Automated Immunoassay Systems
- By Indication
- Cancer
- Uterine Fibroids
- Endometriosis
- Liver Disease
- Other Indications
- By End-User
- Hospitals
- Clinical Laboratories
- Diagnostic Centers
- Academic and Research Organizations
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 47.33% of the CA 125 testing market share in 2025. Medicare coverage and local policy for ovarian cancer-related multimarker tests create a structured basis for testing in the United States. This framework supports repeat testing after therapy and helps laboratories plan for consistent volumes. Canada contributes through provincial oncology programs, while private hospitals in Mexico add demand for immunoassay platforms.
Europe was the second-largest regional market in 2025, with Germany and the United Kingdom holding the largest national shares. France, Italy, and Spain contribute through public hospital procurement and centralized laboratory contracts. The European Union's in vitro diagnostic regulation raises technical documentation and conformity assessment requirements for relevant immunoassay platforms. This favors suppliers that can maintain compliant portfolios and support customers through regulatory changes. Asia-Pacific is forecasted to grow at an 8.24% CAGR through 2031, supported by China's oncology patient base, South Korean automation investment, India's diagnostic networks, and Japan's reimbursement environment.
The Middle East, Africa, and South America remain earlier-stage regions for CA 125 testing. Their growth depends on laboratory infrastructure, procurement capacity, and access to automated immunoassay systems. Private hospitals in Saudi Arabia and the United Arab Emirates are expanding oncology-testing capabilities, while South Africa has established academic hospital networks using major platforms. Brazil leads South American revenue through its private diagnostic laboratories and public oncology programs, while quantitative lateral-flow kits offer an accessible option for laboratories without full automation.
- Abbott Laboratories
- Beckton Dickinson
- bioMerieux
- Bio-Rad Laboratories
- Danaher
- DiaSorin
- Roche
- Fujirebio Holdings, Inc.
- Hologic
- Ortho Clinical Diagnostics Holdings plc
- QIAGEN
- Quest Diagnostics
- Randox Laboratories
- Sekisui Diagnostics
- Shenzhen New Industries Biomedical Engineering
- Siemens Healthineers
- Sysmex
- Thermo Fisher Scientific
- Tosoh
- Werfen S.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Ovarian Cancer Surveillance Demand
- 4.2.2 Expansion of Automated Immunoassay Menus in Core Labs
- 4.2.3 Bundling of CA 125 with HE4 and ROMA Workflows
- 4.2.4 Reimbursement Pressure Favoring Earlier Risk Stratification
- 4.2.5 Self-Collection and Decentralized Sample Logistics
- 4.2.6 AI-Enabled Reflex Testing and Result Triage
- 4.3 Market Restraints
- 4.3.1 Limited Test Specificity in Benign Gynecologic Conditions
- 4.3.2 Clinical Preference for Multi-Marker Panels Over CA 125 Alone
- 4.3.3 Budget Constraints in Low-Resource Laboratory Networks
- 4.3.4 Low Sensitivity for Early-Stage Ovarian Cancer Detection
- 4.4 Supply/Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Reagents and Kits
- 5.1.2 Analyzers and Instruments
- 5.2 By Technology
- 5.2.1 Automated Immunoassay Systems
- 5.2.2 Semi-Automated Immunoassay Systems
- 5.3 By Indication
- 5.3.1 Cancer
- 5.3.2 Uterine Fibroids
- 5.3.3 Endometriosis
- 5.3.4 Liver Disease
- 5.3.5 Other Indications
- 5.4 By End-User
- 5.4.1 Hospitals
- 5.4.2 Clinical Laboratories
- 5.4.3 Diagnostic Centers
- 5.4.4 Academic and Research Organizations
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 Becton, Dickinson and Company
- 6.3.3 bioMerieux SA
- 6.3.4 Bio-Rad Laboratories, Inc.
- 6.3.5 Danaher Corporation
- 6.3.6 DiaSorin S.p.A.
- 6.3.7 F. Hoffmann-La Roche Ltd.
- 6.3.8 Fujirebio Holdings, Inc.
- 6.3.9 Hologic, Inc.
- 6.3.10 Ortho Clinical Diagnostics Holdings plc
- 6.3.11 QIAGEN N.V.
- 6.3.12 Quest Diagnostics Incorporated
- 6.3.13 Randox Laboratories Ltd.
- 6.3.14 Sekisui Diagnostics LLC
- 6.3.15 Shenzhen New Industries Biomedical Engineering Co., Ltd.
- 6.3.16 Siemens Healthineers AG
- 6.3.17 Sysmex Corporation
- 6.3.18 Thermo Fisher Scientific Inc.
- 6.3.19 Tosoh Corporation
- 6.3.20 Werfen S.A.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

