PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154474

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154474
Dental Polishing Machine - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
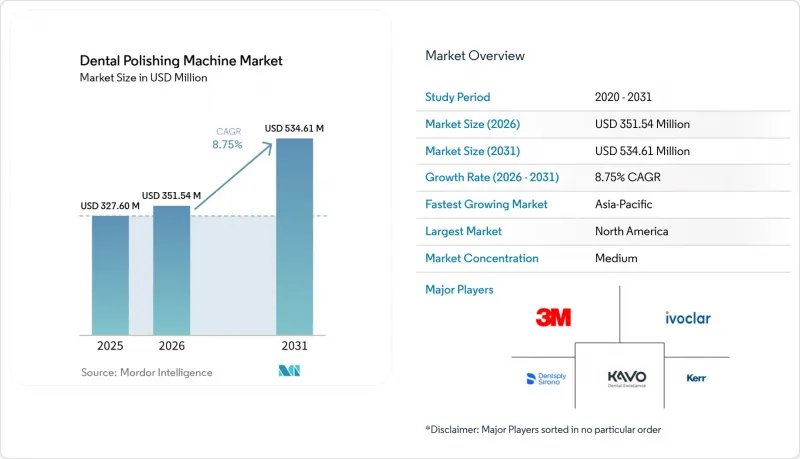
According to Mordor Intelligence, the dental polishing machine market size is projected to expand from USD 327.60 million in 2025 and USD 351.54 million in 2026 to USD 534.61 million by 2031, registering a CAGR of 8.75% between 2026 to 2031.
Global Dental Polishing Machine Market Trends and Insights
Preventive, Periodontal, and Biofilm-Management Procedure Growth
Biofilm management is becoming a first-line part of periodontal maintenance and implant care rather than an added hygiene service. A 2025 network meta-analysis found that erythritol powder ranked highest among 3 subgingival powder agents for probing pocket-depth reduction, with a SUCRA value of 84.1. A 2026 clinical trial found that endoscope-assisted scaling and root planing combined with glycine air polishing resulted in 89.2% of sites reaching a pocket depth of 4 mm or less after 6 months, compared with 55.2% for scaling alone. These findings support more standardized use of air polishing in periodontal protocols. The dental polishing machine market, therefore, benefits when clinics add repeat maintenance visits and implant-support programs. The World Health Organization continues to emphasize prevention and early oral care, which can strengthen demand for hygiene services across public and private settings.
Rising Cosmetic and Aesthetic Dentistry Demand
Cosmetic procedures create additional polishing needs after veneer placement, crown adjustment, cement removal, and whitening-related care. A 2024 Journal of Dental Sciences study reported a 43% increase in elective dental inquiries associated with video-call use. The same study reported a 42% increase in teeth-whitening demand and a 36% increase in veneer consultations among frequent video users. Ceramic veneers and CAD/CAM crowns need controlled finishing after intraoral adjustment. A 2026 study found that chairside zirconia polishing produced a mean surface roughness of 0.180 µm, while furnace glazing produced 0.637 µm. The result supports material-specific polishing as restorative practices use more zirconia restorations.
Equipment Costs and Reimbursement Constraints
High equipment, service, consumable, and training costs can delay adoption by independent practices. Premium air-polishing platforms require continued spending on powders, handpieces, servicing, and staff training after the initial purchase. Public and private reimbursement often does not fully cover polishing and periodontal maintenance procedures, particularly in price-sensitive markets. Practices that depend on out-of-pocket payment can struggle to recover the premium of air polishing over conventional rubber-cup methods. The dental polishing machine market can consequently split between well-funded DSOs and hospital-affiliated clinics that buy premium systems and smaller operators that choose lower-cost alternatives. Device clearance and conformity requirements can also increase development costs for manufacturers and limit the number of affordable options.
Other drivers and restraints analyzed in the detailed report include:
- Dental Clinic, DSO, and Consumable Ecosystem Expansion
- Digital Workflow, Chairside Integration, and Laboratory Automation
- Aerosol Control and Process Variability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Air-polishing machines held 39.4% of 2025 machine-type revenue. Their leadership reflects use in supragingival prophylaxis, subgingival periodontal maintenance, and implant care. Non-contact biofilm removal supports their use on surfaces where clinicians seek to limit mechanical damage. Recurring powder sales also encourage suppliers to maintain installed systems and provide clinical training. Rotary and electric polishing machines remain important in laboratory workflows for metal frameworks and composite restorations. Other machines include combination modalities that bring together more than 1 hygiene function.
Integrated dental polishing systems are forecast to grow at a 9.8% CAGR through 2031. These platforms combine scaling, air polishing, and subgingival therapy in 1 console. EMS introduced its GBT Machine at IDS 2025 with powder delivery, piezo scaling, and digital monitoring features. EMS-The combined configuration can reduce equipment footprint in a hygiene room. It can also simplify the handoff between scaling and polishing during the same appointment. The dental polishing machine market is moving toward systems that combine device sales with servicing and data functions.
Portable units held 44.8% of 2025 product-configuration revenue. Their position reflects lower entry costs and flexibility across different operatory layouts. Mobile dental programs and satellite clinics can also move portable equipment where it is needed. This format remains useful in markets where practices share equipment between chairs. Benchtop and stationary units are established in laboratories that require repeatable speeds and material settings. These units support finishing work on metallic and ceramic restorations.
Integrated dental-unit systems are projected to grow at a 10.4% CAGR through 2031. Embedded modules can reduce clutter and support more consistent operator positioning. The 2026 zirconia study showed that controlled chairside polishing achieved surface roughness below the 0.2 µm clinical threshold. This need for consistent, material-specific treatment supports systems that can store defined operating settings. ISO 20608:2018 covers powder jet handpieces and powders used in dentistry. Institutional buyers may favor systems that support documented safety and performance requirements.
Complete Report Scope:
- By Machine Type
- Air-Polishing Machines
- Rotary/Electric Polishing Machines
- Integrated Dental Polishing Systems
- Other Machines
- By Product Configuration
- Portable Units
- Benchtop & Stationary Units
- Integrated Dental-Unit Systems
- By Application
- Prophylaxis & Stain Removal
- Plaque & Biofilm Removal
- Periodontal Therapy
- Orthodontic & Implant Maintenance
- Restorative & Prosthetic Finishing
- By End User
- Dental Clinics
- Hospitals
- Dental Laboratories
- Academic & Research Institutes
- By Technology
- Air Polishing
- Rotary Mechanical Polishing
- Electropolishing
- Hybrid & Automated Systems
- By Material Processed
- Natural Teeth (Enamel)
- Metals (Titanium, Stainless Steel, Co-Cr)
- Ceramics & Zirconia
- Composites & Acrylics
- By Geography, Value
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 38.7% of 2025 global revenue. High preventive-visit frequency and private coverage for prophylaxis support the region's use of advanced hygiene equipment. The growth of multi-site dental organizations also supports network-level purchasing and standardized protocols. Connected dentistry workflows extend demand into restorative departments that use scanning, chairside milling, and finishing. The Centers for Disease Control and Prevention continues to shape dental infection-control practices in the United States. Canada and Mexico contribute secondary demand, while Mexico benefits from dental tourism and cross-border patient flows.
Europe is the second-largest regional market in the dental polishing machine market. Germany, France, the United Kingdom, Italy, and Spain combine mature dental infrastructure with established preventive-care practices. The EU Medical Device Regulation raises traceability and post-market surveillance expectations for device suppliers. Germany remained a major launch venue when suppliers presented new prophylaxis platforms at IDS 2025 in Cologne. EMS presented the GBT Machine, NSK presented the Varios Combi Pro2, and ACTEON presented OPUS at the event. Western European markets tend to adopt advanced hygiene technology earlier, while other regional markets provide additional room for prevention-focused equipment.
Asia-Pacific is forecast to grow at a 9.5% CAGR through 2031, making it the fastest-growing geography in the dental polishing machine market. China is shifting from extraction-focused care toward more preventive procedures in tier-2 cities. India continues to add dental professionals, which expands capacity for hygiene and restorative workflows. South Korea, Japan, and Australia contribute demand for advanced clinical equipment. South America gains support from private dental networks and dental tourism, particularly in Brazil and Argentina. Middle East and Africa remains smaller but is supported by dental-facility modernization in GCC countries and private clinic growth in South Africa.
List of Companies Covered in this Report:
- 3M
- Acteon Group
- A-dec
- Bien Air
- Danaher
- Dentsply Sirona
- D-RR DENTAL SE
- EMS Electro Medical Systems
- GC Corporation
- Henry Schein
- HuFriedyGroup
- Ivoclar Vivadent
- Kavo Dental
- Kerr
- Mectron S.p.A.
- NSK Nakanishi Inc.
- Planmeca
- SHOFU INC.
- Ultradent Products, Inc.
- W&H Dentalwerk B-rmoos GmbH
- Young Innovations, Inc.
- GPAINNOVA
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Preventive, Periodontal, and Biofilm-Management Procedure Growth
- 4.2.2 Rising Cosmetic and Aesthetic Dentistry Demand
- 4.2.3 Dental Clinic and Dental Service Organization Expansion
- 4.2.4 Digital Workflow and Chairside Laboratory Integration
- 4.2.5 Compact Automation for Dental Laboratories
- 4.2.6 Proprietary Powder and Consumable Ecosystems
- 4.3 Market Restraints
- 4.3.1 High Equipment, Service, and Training Costs
- 4.3.2 Reimbursement Gaps and Small-Practice Capital Constraints
- 4.3.3 Aerosol, Particulate, and Infection-Control Compliance
- 4.3.4 Material-Specific Process Validation and Operator Variability
- 4.4 Value and Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Machine Type
- 5.1.1 Air-Polishing Machines
- 5.1.2 Rotary/Electric Polishing Machines
- 5.1.3 Integrated Dental Polishing Systems
- 5.1.4 Other Machines
- 5.2 By Product Configuration
- 5.2.1 Portable Units
- 5.2.2 Benchtop & Stationary Units
- 5.2.3 Integrated Dental-Unit Systems
- 5.3 By Application
- 5.3.1 Prophylaxis & Stain Removal
- 5.3.2 Plaque & Biofilm Removal
- 5.3.3 Periodontal Therapy
- 5.3.4 Orthodontic & Implant Maintenance
- 5.3.5 Restorative & Prosthetic Finishing
- 5.4 By End User
- 5.4.1 Dental Clinics
- 5.4.2 Hospitals
- 5.4.3 Dental Laboratories
- 5.4.4 Academic & Research Institutes
- 5.5 By Technology
- 5.5.1 Air Polishing
- 5.5.2 Rotary Mechanical Polishing
- 5.5.3 Electropolishing
- 5.5.4 Hybrid & Automated Systems
- 5.6 By Material Processed
- 5.6.1 Natural Teeth (Enamel)
- 5.6.2 Metals (Titanium, Stainless Steel, Co-Cr)
- 5.6.3 Ceramics & Zirconia
- 5.6.4 Composites & Acrylics
- 5.7 By Geography, Value
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 South Korea
- 5.7.3.5 Australia
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East and africa
- 5.7.4.1 GCC
- 5.7.4.2 South Africa
- 5.7.4.3 Rest of Middle East and Africa
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 3M
- 6.3.2 ACTEON Group
- 6.3.3 A-dec Inc.
- 6.3.4 Bien-Air Dental
- 6.3.5 Danaher Corporation
- 6.3.6 Dentsply Sirona
- 6.3.7 D-RR DENTAL SE
- 6.3.8 EMS Electro Medical Systems
- 6.3.9 GC Corporation
- 6.3.10 Henry Schein, Inc.
- 6.3.11 HuFriedyGroup
- 6.3.12 Ivoclar Vivadent AG
- 6.3.13 KaVo Dental
- 6.3.14 Kerr Corporation
- 6.3.15 Mectron S.p.A.
- 6.3.16 NSK Nakanishi Inc.
- 6.3.17 Planmeca Oy
- 6.3.18 SHOFU INC.
- 6.3.19 Ultradent Products, Inc.
- 6.3.20 W&H Dentalwerk B-rmoos GmbH
- 6.3.21 Young Innovations, Inc.
- 6.3.22 GPAINNOVA
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
- 7.1.1 Affordable Modular Polishing for Small and Mid-Sized Clinics
- 7.1.2 Low-Aerosol and Closed-Loop Powder Management
- 7.1.3 Material-Specific Presets for Digital Dental Restorations
- 7.1.4 Automated Finishing for High-Volume Dental Laboratories
- 7.1.5 Consumable-Open Platforms and Interoperable Fixtures
- 7.1.6 Predictive Maintenance and Usage-Based Service Models
- 7.2 Future Outlook and Strategic Imperatives

