PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154485

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154485
Disposable Laparoscopic Instruments - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the disposable laparoscopic instruments market size is expected to increase from USD 6.56 billion in 2025 to USD 6.92 billion in 2026 and reach USD 9.04 billion by 2031, growing at a CAGR of 5.5% over 2026-2031.
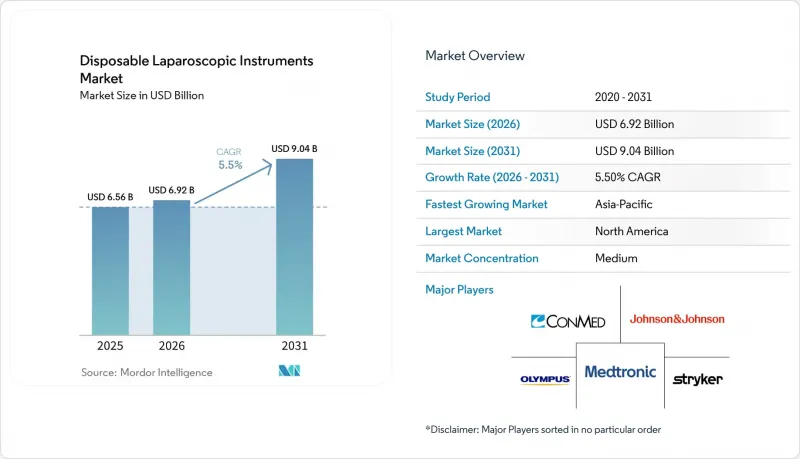
Global Disposable Laparoscopic Instruments Market Trends and Insights
Rising Minimally Invasive Surgery Volumes
Minimally invasive procedures remain a key demand driver for the disposable laparoscopic instruments market. Laparoscopic hernia repair, cholecystectomy, and oncology procedures support shorter recovery periods and lower bed-day requirements, helping hospitals optimize operating room capacity. Robotic surgery has expanded the use of compatible single-use clip appliers, stapler reloads, and vessel-sealing tips. Higher procedure volumes therefore continue to support recurring demand despite pricing pressure on basic instruments.
Infection-Control Preference for Sterile Single-Use Tools
Infection prevention remains a key factor driving the adoption of sterile single-use tools in the disposable laparoscopic instruments market. A 2025 study found visible soil or debris on all inspected reusable lumened surgical instruments after standard cleaning, while 95% had rust patches. A separate 2025 investigation linked two consecutive Serratia marcescens surgical outbreaks to inadequate reprocessing of reusable LigaSure devices. These findings support the evaluation of disposable alternatives for complex, high-risk instruments.
Higher Lifecycle Cost of Fully Disposable Trocar Systems
Sustainability requirements are increasing pressure on the disposable laparoscopic instruments market, particularly in European tenders. A 2026 systematic review found that single-use instruments had higher environmental footprints than multi-use alternatives, although methodological differences limited definitive conclusions. A separate lifecycle study calculated emissions of 1.13 kgCO2e per laparoscopic cholecystectomy for disposable trocars, compared with 0.236 kgCO2e for reusable trocars. The study found that reusable trocars reduced per-procedure emissions by 21%, increasing the need for manufacturers to address waste, packaging, disposal, and lifecycle performance in procurement assessments and tender specifications.
Other drivers and restraints analyzed in the detailed report include:
- Operating-Room Turnover and Reprocessing Labor Avoidance
- Growth of Ambulatory Laparoscopic Procedures
- Sustainability and Sharps-Waste Scrutiny
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Trocars held 18.54% of revenue in 2025, making them the largest product category. Their use as access points across laparoscopic procedures supports consistent demand, as each case requires access ports. Bladeless and optical-entry products command higher prices than legacy bladed models. Electrosurgical devices are forecast to grow at a 7.22% CAGR through 2031, driven by demand for integrated vessel sealing, ultrasonic cutting, and smoke-management capabilities. Olympus launched THUNDERBEAT II in Europe in October 2025, while Medtronic announced a limited launch of the Signia Circular Stapler with Tri-Staple technology in November 2025.
Graspers, scissors, forceps, dissectors, clip appliers, and retrieval instruments represent a stable middle segment within the product mix. Demand for these products follows procedure volumes in general surgery, gynecology, and colorectal surgery. Staplers remain strategically important because robotic-compatible reloads are used once per engagement and sell at a premium to standard laparoscopic alternatives. Ethicon received a CE mark for the Ethicon 4000 stapler, based on the Echelon 3000 with 3D staple technology.
Access and port-creation instruments held 27.66% of revenue in 2025, representing the largest functional share of the disposable laparoscopic instruments market. Each laparoscopic procedure requires two to four access ports, supporting stable demand. Bladeless and optical-entry trocars increase average unit values without requiring higher procedure volumes. FDA 510(k) submissions for disposable trocars typically address biocompatibility, sterilization validation, and shelf-life testing, favoring suppliers with established regulatory documentation.
Dissection and cutting instruments are forecast to expand at a 7.56% CAGR through 2031, the fastest rate among functional categories. Ultrasonic, bipolar, and hybrid tools cut and seal tissue in a single step while reducing lateral thermal spread compared with conventional monopolar scissors. Laparoscopic and robotic platforms favor multifunctional energy instruments over mechanical scissors. Stapling, tissue-sealing, suction, irrigation, smoke-management, closure, and specimen-retrieval products benefit from complex oncology procedures and longer operating times.
Complete Report Scope:
- By Product Type
- Trocars
- Graspers
- Scissors
- Forceps and Dissectors
- Staplers
- Electrosurgical Devices
- Suction and Irrigation Devices
- Clip Appliers
- Retrieval and Closure Instruments
- Other Instruments
- By Instrument Function
- Access and Port Creation
- Dissection and Cutting
- Grasping and Tissue Handling
- Stapling and Tissue Sealing
- Suction, Irrigation, and Smoke Management
- Closure and Specimen Retrieval
- Others
- By Procedure Type
- Diagnostic Laparoscopy
- Operative Laparoscopy
- Advanced Therapeutic Laparoscopy
- Oncology-Linked Laparoscopy
- By Application
- General and Gastrointestinal Surgery
- Gynecological Surgery
- Urological Surgery
- Bariatric Surgery
- Thoracic and Pediatric Laparoscopy
- Others
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 39.56% of revenue in 2025, supported by high laparoscopic procedure volumes, documented sterility requirements, and established ambulatory reimbursement. The CMS 2026 rule added 547 surgical procedures to the Ambulatory Surgical Center Covered Procedures List and removed 285 inpatient-only services, supporting outpatient facility demand. Canada followed a similar adoption pattern, while private hospitals and medical tourism supported procedure growth in major Mexican cities. However, group purchasing organizations continued to pressure supplier margins by prioritizing lower-cost trocar alternatives.
Asia-Pacific is forecast to grow at a CAGR of 6.90% through 2031, the fastest regional rate in the disposable laparoscopic instruments market. China had the largest regional procedure base, although its volume-based procurement program reduced average selling prices for international suppliers and extended to minimally invasive staplers in 2025 and 2026. Japan, South Korea, and Australia remained key premium markets for advanced-energy and robotics-compatible devices, while India expanded domestic medical-device capacity through its Production-Linked Incentive program. China's Medical Device Registration Holder system, implemented in 2025, streamlined approval pathways for locally developed devices.
Europe and the remaining regions accounted for the balance of revenue. Article 17 of Regulation (EU) 2017/745 restricted single-use device reprocessing to nationally authorized settings, and the European Commission's November 2024 review found that 10 of 27 member states permitted some form of reprocessing. This framework supported demand for new sterile devices, although lifecycle costs, waste concerns, and pricing pressures remained important in tenders. The Middle East and Africa benefited from new tertiary surgical centers, while private hospitals in Brazil and Argentina adopted disposable kits despite public-sector budget constraints.
- Applied Medical Resources
- B. Braun
- BOWA electronic GmbH & Co. KG
- Conmed
- Cook Group
- The Cooper Companies
- Hangzhou Kangji Medical Instruments Co., Ltd.
- Johnson & Johnson
- Karl Storz
- KLS Martin Group
- LaproSurge Ltd
- Medtronic
- Olympus
- Peters Surgical
- Purple Surgical Holdings Limited
- Richard Wolf
- Smiths Group
- Stryker
- Surgical Innovations Group plc
- Teleflex
- Trokamed GmbH
- Victor Medical Instruments Co., Ltd.
- Zhejiang Geyi Medical Instrument Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Minimally Invasive Surgery Volumes
- 4.2.2 Infection-Control Preference for Sterile Single-Use Tools
- 4.2.3 Operating-Room Turnover and Reprocessing Labor Avoidance
- 4.2.4 Growth of Ambulatory Laparoscopic Procedures
- 4.2.5 Optical and Advanced-Energy Instrument Migration
- 4.2.6 Procedure-Kit Standardization in Emerging Surgical Systems
- 4.3 Market Restraints
- 4.3.1 Higher Lifecycle Cost of Fully Disposable Trocar Systems
- 4.3.2 Sustainability and Sharps-Waste Scrutiny
- 4.3.3 Surgeon and Hospital Preference for Reusable Platforms
- 4.3.4 Sterility, Supply Continuity, and Device-Approval Complexity
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Competitive Rivalry Analysis
- 4.7.2 Threat of New Entrants Analysis
- 4.7.3 Bargaining Power of Suppliers Analysis
- 4.7.4 Bargaining Power of Buyers Analysis
- 4.7.5 Threat of Substitutes Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Product Type
- 5.1.1 Trocars
- 5.1.2 Graspers
- 5.1.3 Scissors
- 5.1.4 Forceps and Dissectors
- 5.1.5 Staplers
- 5.1.6 Electrosurgical Devices
- 5.1.7 Suction and Irrigation Devices
- 5.1.8 Clip Appliers
- 5.1.9 Retrieval and Closure Instruments
- 5.1.10 Other Instruments
- 5.2 By Instrument Function
- 5.2.1 Access and Port Creation
- 5.2.2 Dissection and Cutting
- 5.2.3 Grasping and Tissue Handling
- 5.2.4 Stapling and Tissue Sealing
- 5.2.5 Suction, Irrigation, and Smoke Management
- 5.2.6 Closure and Specimen Retrieval
- 5.2.7 Others
- 5.3 By Procedure Type
- 5.3.1 Diagnostic Laparoscopy
- 5.3.2 Operative Laparoscopy
- 5.3.3 Advanced Therapeutic Laparoscopy
- 5.3.4 Oncology-Linked Laparoscopy
- 5.4 By Application
- 5.4.1 General and Gastrointestinal Surgery
- 5.4.2 Gynecological Surgery
- 5.4.3 Urological Surgery
- 5.4.4 Bariatric Surgery
- 5.4.5 Thoracic and Pediatric Laparoscopy
- 5.4.6 Others
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Ambulatory Surgical Centers
- 5.5.3 Specialty Clinics
- 5.5.4 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Applied Medical Resources Corporation
- 6.3.2 B. Braun Melsungen AG
- 6.3.3 BOWA electronic GmbH & Co. KG
- 6.3.4 CONMED Corporation
- 6.3.5 Cook Group Incorporated
- 6.3.6 CooperSurgical, Inc.
- 6.3.7 Hangzhou Kangji Medical Instruments Co., Ltd.
- 6.3.8 Johnson & Johnson (Ethicon, Inc.)
- 6.3.9 Karl Storz SE & Co. KG
- 6.3.10 KLS Martin Group
- 6.3.11 LaproSurge Ltd
- 6.3.12 Medtronic plc
- 6.3.13 Olympus Corporation
- 6.3.14 Peters Surgical
- 6.3.15 Purple Surgical Holdings Limited
- 6.3.16 Richard Wolf GmbH
- 6.3.17 Smith & Nephew plc
- 6.3.18 Stryker Corporation
- 6.3.19 Surgical Innovations Group plc
- 6.3.20 Teleflex Incorporated
- 6.3.21 Trokamed GmbH
- 6.3.22 Victor Medical Instruments Co., Ltd.
- 6.3.23 Zhejiang Geyi Medical Instrument Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

