PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154486

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154486
Embolization Coils - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
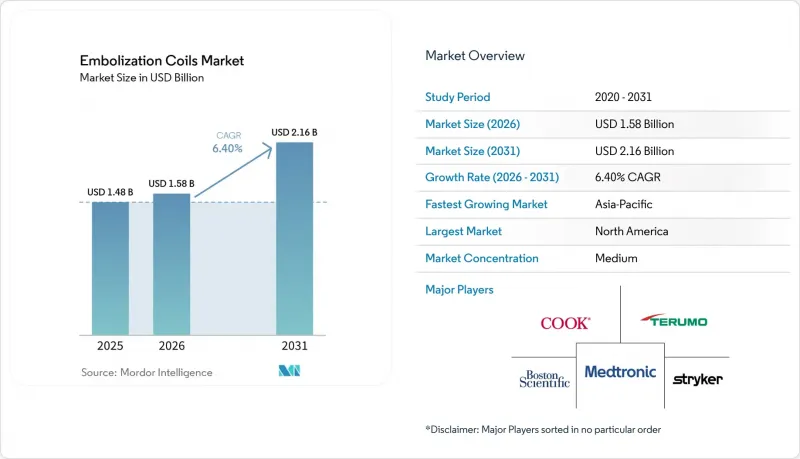
According to Mordor Intelligence, the embolization coils market size is expected to increase from USD 1.48 billion in 2025 to USD 1.58 billion in 2026 and reach USD 2.16 billion by 2031, growing at a CAGR of 6.40% over 2026-2031.
Global Embolization Coils Market Trends and Insights
Rising Neurovascular Aneurysm and AVM Treatment Volumes
Intracranial aneurysm embolization remained a key demand driver for the Embolization coils market. Wider access to computed tomography angiography and magnetic resonance angiography increased aneurysm detection among patients without emergency presentations. This expanded the pool of patients eligible for planned neurovascular intervention. The World Health Organization's 2025 report identified stroke as the leading neurological contributor to global health loss, while the Stroke Alliance reported that the direct cost of 24 brain disorders exceeded USD 1.7 trillion.
The expansion of stroke centers across Asia-Pacific, the Middle East, and Africa strengthened the clinical infrastructure for aneurysm and arteriovenous malformation procedures. The American Heart Association reported continued growth in endovascular therapy use for acute ischemic stroke during a six-year national analysis. This trend showed that catheter-based neurovascular care had become more established within hospital treatment pathways.
Preference for Minimally Invasive Endovascular Procedures
Endovascular embolization was often preferred over surgical ligation or craniotomy because it reduced hospitalization and recovery time. In suitable patients, it also reduced intensive care resource utilization. These clinical and operational benefits supported catheter-based procedures as healthcare systems managed capacity and costs. The Embolization coils market benefited as coils remained integral to aneurysm and vessel occlusion procedures.
Training also reinforced the shift toward endovascular care. As hospitals established interventional radiology and interventional neurology fellowship programs, the number of qualified operators increased. A larger trained workforce reduced the concentration of complex coiling procedures in a limited number of tertiary hospitals. OECD data showed that ischemic stroke case-fatality rates declined across member countries between 2013 and 2019 as improvements in reperfusion therapy delivery coincided with wider endovascular use.
High Device and Procedure Costs
Premium detachable systems, including hydrogel-enhanced and platinum-tungsten designs, can cost several thousand USD per procedure. In many middle-income healthcare systems, these costs can exceed available reimbursement. The gap between device costs and reimbursement can limit adoption, even when clinical need is high. Consequently, coil uptake remains uneven across countries with varying payment systems and is concentrated in locations with stronger reimbursement frameworks and established referral pathways.
Cost is not the only barrier to premium coil adoption. A prospective, multicenter, randomized trial, with follow-up completed in February 2025, found that operators rated bare platinum coils easier to manipulate than second-generation hydrogel designs, with scores of 8.8 and 6.3, respectively, on a 10-point scale. Higher-priced systems must therefore demonstrate clear procedural or clinical benefits. Group purchasing arrangements also increase price pressure, limiting pricing flexibility for manufacturers and new entrants. Vendors must support premium pricing through clinical evidence, workflow advantages, or differentiated clinical applications.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Interventional Radiology and Stroke-Care Infrastructure
- Increased Use of Coils in Peripheral Hemorrhage and Oncology Embolization
- Requirements for Highly Specialized Operators and Infrastructure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Detachable coils held a 61.45% share of the embolization coils market in 2025. Their ability to reposition coils and confirm stability before electrolytic or mechanical detachment supports precise vessel occlusion in wide-neck aneurysms and high-flow arteriovenous fistulae. This capability enables physicians to adjust placement before final release in anatomically complex cases.
Suppliers must offer a range of diameters, softness levels, and delivery options to address the segment's large installed base. Product breadth can support standardized purchasing across framing, filling, and finishing stages. Pushable coils are the fastest-growing deployment type, with a projected CAGR of 7.22% from 2026 to 2031, driven by oncology and gastrointestinal hemorrhage procedures that prioritize speed and cost efficiency.
Bare platinum coils held a 41.67% revenue share in 2025, supported by extensive clinical use, documented safety, and compatibility with existing microcatheter inventories. Physician familiarity and established procurement relationships further reinforce demand. Bare platinum remains the standard benchmark for evaluating newer coil technologies.
Platinum-tungsten alloy coils are forecast to grow at a CAGR of 7.56% through 2031. Higher radiopacity, thinner wire gauges, improved packing density, and three-dimensional conformability support detailed visualization and controlled filling in complex anatomy. This design approach has been commercialized in more than 30 countries, supporting adoption in neurovascular and peripheral procedures.
Complete Report Scope:
- By Deployment Type
- Detachable Coils
- Pushable Coils
- By Material
- Bare Platinum Coils
- Platinum-Tungsten Alloy Coils
- Platinum and Hydrogel Coils
- Fibered Polymer-Enhanced Coils
- Nitinol and Reduced-Artifact Coils
- Bioabsorbable Polymer Coils
- By Application
- Neurovascular Applications
- Peripheral Vascular Disease
- Oncology
- Gastrointestinal Bleeding
- Cardiology and Structural Heart Procedures
- Urology
- Trauma and Emergency Hemorrhage Control
- Others
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Cardiology Centers
- Specialty Interventional Radiology Centers
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 40.40% of the embolization coils market share in 2025, supported by comprehensive stroke centers, third-party reimbursement, and an established interventional radiology workforce. A six-year national assessment reported 103,355 endovascular therapy procedures among 867,335 acute ischemic stroke hospitalizations in the United States, representing an 11.9% utilization rate. Canada standardizes aneurysm care through provincial stroke networks, while Mexico is expanding neurovascular capacity through public and private hospital modernization.
Germany, the United Kingdom, France, Italy, and Spain support the European market through the integration of coil embolization into national stroke care pathways. The EU Medical Device Regulation creates entry barriers for smaller companies, while established suppliers with CE certification are better positioned to retain market access. Japan remains a premium market and regulatory reference point, with Terumo Neuro receiving PMDA approval for WovenEndoBridge 17 in November 2025 and launching it commercially in May 2026.
Asia-Pacific is projected to record the fastest regional CAGR of 7.90% from 2026 to 2031, driven by mature interventional radiology systems in Japan and South Korea and increasing procedure volumes in China. India is strengthening institutional capacity, with equipment availability, training, and pricing remaining key adoption factors. MicroPort NeuroScientific launched the NUMEN Coil Embolization System in Egypt in August 2025 through its partnership with PentaMed, expanding access to Middle East and Africa markets.
- Acandis GmbH & Co. KG
- Artio Medical, Inc.
- Asahi Intecc
- B. Braun
- BALT Extrusion SAS
- Boston Scientific
- Cook Group
- Integer Holdings
- Johnson & Johnson
- KANEKA CORPORATION
- Lepu Medical Technology (Beijing) Co., Ltd.
- Medtronic
- Merit Medical Systems
- MicroPort NeuroTech Co., Ltd.
- MicroVention
- Penumbra
- Phenox
- Q'Apel Medical, Inc.
- Rapid Medical Ltd.
- Route 92 Medical, Inc.
- Shape Memory Medical, Inc.
- Sirtex Medical Pty Ltd
- Stryker
- Terumo
- Wallaby Medical, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Neurovascular Aneurysm and AVM Treatment Volumes
- 4.2.2 Preference for Minimally Invasive Endovascular Procedures
- 4.2.3 Expansion of Interventional Radiology and Stroke-Care Infrastructure
- 4.2.4 Increased Use of Coils in Peripheral Hemorrhage and Oncology Embolization
- 4.2.5 Improving Coil Conformability and Packing-Density Performance
- 4.2.6 Increasing Demand for Bioabsorbable and Artifact-Reducing Coil Technologies
- 4.3 Market Restraints
- 4.3.1 High Device and Procedure Costs
- 4.3.2 Requirements for Highly Specialized Operators and Infrastructure
- 4.3.3 Polymer Particulate Shedding and Long-Term Safety Concerns
- 4.3.4 Limited Comparative Evidence Across Coil Designs and Manufacturers
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Deployment Type
- 5.1.1 Detachable Coils
- 5.1.2 Pushable Coils
- 5.2 By Material
- 5.2.1 Bare Platinum Coils
- 5.2.2 Platinum-Tungsten Alloy Coils
- 5.2.3 Platinum and Hydrogel Coils
- 5.2.4 Fibered Polymer-Enhanced Coils
- 5.2.5 Nitinol and Reduced-Artifact Coils
- 5.2.6 Bioabsorbable Polymer Coils
- 5.3 By Application
- 5.3.1 Neurovascular Applications
- 5.3.2 Peripheral Vascular Disease
- 5.3.3 Oncology
- 5.3.4 Gastrointestinal Bleeding
- 5.3.5 Cardiology and Structural Heart Procedures
- 5.3.6 Urology
- 5.3.7 Trauma and Emergency Hemorrhage Control
- 5.3.8 Others
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Ambulatory Surgical Centers
- 5.4.3 Cardiology Centers
- 5.4.4 Specialty Interventional Radiology Centers
- 5.4.5 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Acandis GmbH & Co. KG
- 6.3.2 Artio Medical, Inc.
- 6.3.3 ASAHI INTECC CO., LTD.
- 6.3.4 B. Braun SE
- 6.3.5 BALT Extrusion SAS
- 6.3.6 Boston Scientific Corporation
- 6.3.7 Cook Medical LLC
- 6.3.8 Integer Holdings Corporation
- 6.3.9 Johnson & Johnson
- 6.3.10 KANEKA CORPORATION
- 6.3.11 Lepu Medical Technology (Beijing) Co., Ltd.
- 6.3.12 Medtronic plc
- 6.3.13 Merit Medical Systems, Inc.
- 6.3.14 MicroPort NeuroTech Co., Ltd.
- 6.3.15 MicroVention, Inc.
- 6.3.16 Penumbra, Inc.
- 6.3.17 phenox GmbH
- 6.3.18 Q'Apel Medical, Inc.
- 6.3.19 Rapid Medical Ltd.
- 6.3.20 Route 92 Medical, Inc.
- 6.3.21 Shape Memory Medical, Inc.
- 6.3.22 Sirtex Medical Pty Ltd
- 6.3.23 Stryker Corporation
- 6.3.24 Terumo Corporation
- 6.3.25 Wallaby Medical, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

