PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154737

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154737
Thermal Insulation Material - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
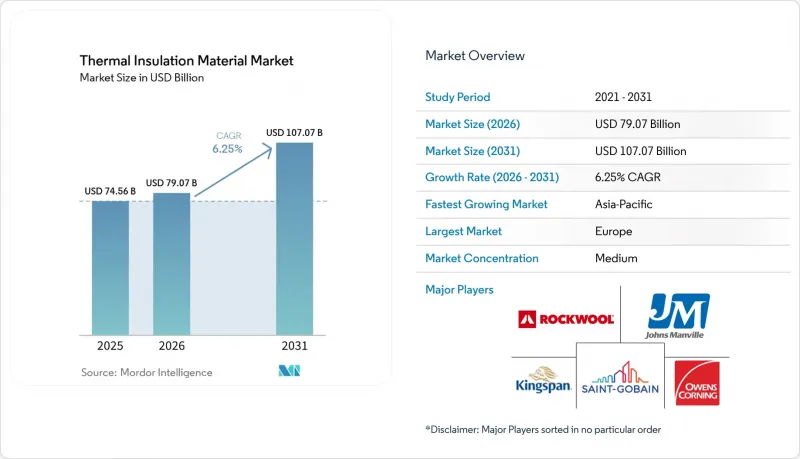
According to Mordor Intelligence, the thermal insulation material market size was estimated at USD 74.56 billion in 2025 and is estimated to grow from USD 79.07 billion in 2026 to USD 107.07 billion by 2031, at a CAGR of 6.25% during the forecast period (2026-2031).
Global Thermal Insulation Material Market Trends and Insights
Tightening Building Energy-Performance Standards
Building codes are driving demand in the thermal insulation material market. The recast Energy Performance of Buildings Directive (EU) 2024/1275 entered into force in 2024, and member states must transpose it into national law by May 2026. The directive requires national authorities to establish minimum energy-performance thresholds, requiring higher-specification insulation for compliance. Commission Delegated Regulation (EU) 2026/52 introduces a Union framework for calculating building life-cycle global warming potential using EN 15978:2011. The framework shifts procurement criteria from standalone U-values to verified environmental performance. Suppliers with third-party Environmental Product Declarations can meet life-cycle data requirements in product selection.
Energy-Efficient Building Retrofits and Renovation Incentives
Renovation programs support demand for the thermal insulation material market beyond new-construction cycles. Germany's Federal Office for Economic Affairs and Export Control (BAFA) supports building-envelope insulation through the Federal Funding for Efficient Buildings - Individual Measures (BEG EM) program. A Worst-Performing Building bonus is expected to begin in Q1 2027 for eligible households using an Individual Refurbishment Roadmap. The program links support to a certified whole-house plan rather than a single improvement measure. Tokyo's FY2026 program for insulation and renewable energy in rental housing has a JPY 21.8 billion (~USD 0.13 billion) budget and accepts applications from May 2026 through February 2027. Germany's energy renovation rate declined to 0.67% in 2025, while sales of thermal composite insulation systems fell by 15% to 30.5 million m2 in 2024. These trends indicate that program discontinuity can affect contractor planning and inventory investment. Consistent incentives remain relevant to policy implementation.
Volatility in Polymer, Mineral Fiber, and Energy Input Costs
Input cost volatility remains a margin risk for the thermal insulation materials market. Mineral wool production requires melting basalt and slag at temperatures above 1,200°C, exposing producers to fluctuations in electricity and natural gas prices. Energy represents 20-35% of mineral wool production costs. The U.S. Producer Price Index for mineral wool stood at 275.3 in June 2026, largely unchanged from February 2026, as broader energy conditions continued to influence costs. Foam suppliers also depend on the availability of methylene diphenyl diisocyanate (MDI) and related feedstocks. Manufacturers with vertical integration or long-term, energy-indexed contracts have greater capacity to manage cost fluctuations than smaller regional producers.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Electric Vehicles and Battery Thermal Management
- Industrial Decarbonization and Process-Energy Optimization
- High Installation Costs and Skilled-Installer Shortages
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fiberglass held a 36.67% share of the thermal insulation material market in 2025, supported by its cost position and established manufacturing and distribution base in North American and European residential construction. Stone wool is expected to record the fastest growth, at a CAGR of 6.79% through 2031. It provides fire performance and acoustic control in a single product layer and can meet Euroclass A1 non-combustibility requirements under EN 13501-1. These characteristics are relevant for European multifamily buildings and commercial high-rise projects, where A2 or higher fire ratings are increasingly required.
Foam products, including polyurethane, polyiso, and EPS, remain important for below-grade and roof-deck applications. End-of-life constraints for composite systems and feedstock price exposure affect their outlook. Research published in IOP Conference Series: Earth and Environmental Science projects that annual EPS waste from External Thermal Insulation Composite Systems will increase fourfold by 2050. Wood fiber remains a smaller material category but is gaining attention in DACH and Nordic projects that prioritize biogenic carbon accounting. Research published in Resources reported that polymeric foams accounted for 48% of Germany's insulation demand in 2019, mineral wools for 43%, and bio-based materials for 9%. Wood fiber represented 58% of the bio-based share. It serves projects where material origin and lifecycle documentation are part of the project brief. Its use remains selective because fiberglass, stone wool, and foam supply chains are well established. Circular-economy product policies may become more relevant in selected projects.
ROCKWOOL broke ground in 2026 on a USD 175 million plant in Wallula, Washington, its fifth North American facility. The plant will address stone wool supply requirements on the Pacific Coast as energy code requirements tighten. Knauf Insulation has also planned a new rock mineral wool plant in Shotton, United Kingdom, using submerged arc furnace electric melting technology. These investments direct capacity toward products that provide thermal, acoustic, fire, and environmental performance. Suppliers that document lower manufacturing emissions may be considered in projects where lifecycle reporting guides material selection.
Complete Report Scope:
- By Material Type
- Fiberglass
- Stone Wool
- Foam
- Wood Fiber
- Other Materials
- By Temperature Range
- 0-100°C
- 100-500°C
- 500°C and Above
- By End-User Industry
- Construction
- Automotive
- HVAC
- Industrial
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Europe held a 36.56% share of the thermal insulation material market in 2025. Germany, France, the United Kingdom, and the Nordic countries drove regional demand. The recast Energy Performance of Buildings Directive (EPBD) requires new buildings to be zero-emission by 2030 and sets energy-performance requirements for major renovations. Europe's large building stock continues to support demand for insulation. Nordic building codes require low U-values for new exterior walls, increasing demand for high-performance products. This regulatory environment supports specification-led demand and the use of products with technical and environmental documentation.
Germany reflects the impact of policy continuity on installation activity. Sales of thermal composite insulation systems declined by 15% to 30.5 million m2 in 2024. The energy renovation rate fell to 0.67% in 2025, primarily due to uncertainty around subsidy planning rather than underlying demand. Changes in program conditions reduce contractors' investment in training and inventory. This limits the conversion of long-term targets into completed projects and may delay the adoption of products requiring specialized installation skills.
Asia-Pacific is forecast to grow at a CAGR of 7.03% through 2031, the highest rate among regions. China, India, and ASEAN drive growth through increased construction activity and stricter energy-performance requirements. Japan's Mirai Eco Housing 2026 program provides JPY 13,000 to JPY 62,000 per m3 for structural insulation upgrades, based on thermal performance class. These programs support demand for higher-specification materials in new construction and renovation projects.
North America is the second-largest regional contributor. In the United States, residential retrofits, new commercial construction, data centers, and electrification-related facilities support demand despite softer single-family housing starts. South America, the Middle East, and Africa account for smaller shares. Saudi Arabia's Vision 2030 infrastructure program includes thermal-performance criteria in public-building tenders. Brazil's Minha Casa Minha Vida program supports demand for fiberglass and expanded polystyrene (EPS) in lower-cost housing. Limited installer availability and supply chain capacity may delay project completion despite active construction programs.
- ARMACELL
- Asahi Kasei Corporation
- BASF
- Covestro AG
- Dow
- GAF Materials LLC
- Huntsman International LLC
- Johns Manville
- Kingspan
- Knauf Insulation
- Owens Corning
- Recticel NV/SA
- ROCKWOOL A/S
- Saint-Gobain
- Sika AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Tightening Building Energy-Performance Standards
- 4.2.2 Energy-Efficient Building Retrofits and Renovation Incentives
- 4.2.3 Expansion of Energy-Efficient Construction in Asia-Pacific
- 4.2.4 Growth of Electric Vehicles and Battery Thermal Management
- 4.2.5 Industrial Decarbonization and Process-Energy Optimization
- 4.3 Market Restraints
- 4.3.1 Volatility in Polymer, Mineral Fiber, and Energy Input Costs
- 4.3.2 High Installation Costs and Skilled-Installer Shortages
- 4.3.3 End-of-Life and Recycling Constraints for Composite Insulation Systems
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Material Type
- 5.1.1 Fiberglass
- 5.1.2 Stone Wool
- 5.1.3 Foam
- 5.1.4 Wood Fiber
- 5.1.5 Other Materials
- 5.2 By Temperature Range
- 5.2.1 0-100°C
- 5.2.2 100-500°C
- 5.2.3 500°C and Above
- 5.3 By End-User Industry
- 5.3.1 Construction
- 5.3.2 Automotive
- 5.3.3 HVAC
- 5.3.4 Industrial
- 5.3.5 Others
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 ARMACELL
- 6.4.2 Asahi Kasei Corporation
- 6.4.3 BASF
- 6.4.4 Covestro AG
- 6.4.5 Dow
- 6.4.6 GAF Materials LLC
- 6.4.7 Huntsman International LLC
- 6.4.8 Johns Manville
- 6.4.9 Kingspan
- 6.4.10 Knauf Insulation
- 6.4.11 Owens Corning
- 6.4.12 Recticel NV/SA
- 6.4.13 ROCKWOOL A/S
- 6.4.14 Saint-Gobain
- 6.4.15 Sika AG
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

