PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154739

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154739
Finishing Chemicals - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
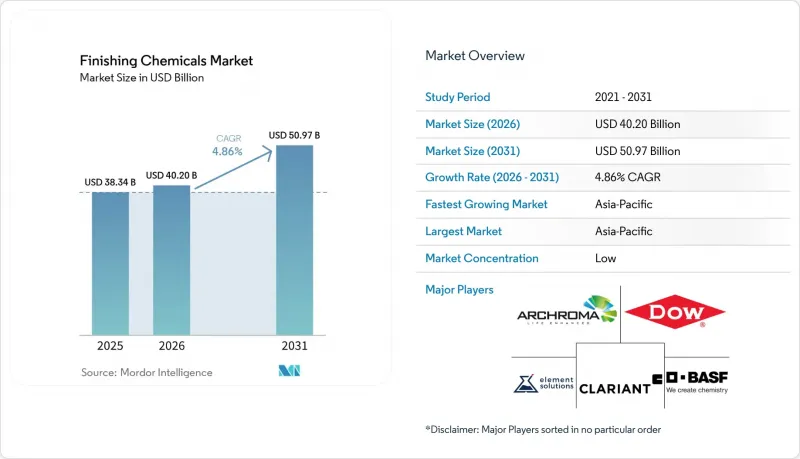
According to Mordor Intelligence, the finishing chemicals market size was valued at USD 38.34 billion in 2025 and is estimated to grow from USD 40.20 billion in 2026 to reach USD 50.97 billion by 2031, at a CAGR of 4.86% during the forecast period (2026-2031).
Global Finishing Chemicals Market Trends and Insights
Growth of Technical and Performance Textiles
Technical and performance textiles are expanding the finishing chemicals market because they need functions that standard softeners cannot provide. Flame retardancy, ultraviolet protection, antimicrobial performance, and moisture management require specialized formulations. Automotive, healthcare, filtration, and construction fabrics use these functions in demanding operating conditions. When automotive manufacturers specify interior textiles, leather, and connector coatings, suppliers can qualify products across several substrates. Archroma presented its SUPER SYSTEMS+ platform for technical textile manufacturers at Techtextil 2026, with applications in antimicrobial, odor-control, and performance finishing. Archroma also received the International Textile Manufacturers Federation 2025 Sustainability & Innovation Award for its DENIM HALO process, showing how performance and process improvements can support differentiation.
PFAS-Free and ZDHC-Compliant Formulation Demand
The phaseout of per- and polyfluoroalkyl substances (PFAS) is driving a major reformulation cycle in the finishing chemicals market. From January 2025, bluesign extended its PFAS ban to short-chain C6 chemistry for bluesign APPROVED and bluesign PRODUCT items. The European standard EN 17681-1:2025, published in April 2025, introduced an alkaline hydrolysis extraction process for targeted PFAS analysis. California Assembly Bill 1817 prohibited PFAS in new textile articles, while Washington State restricted intentionally added PFAS in leather and textile furniture from January 2026. The Registration, Evaluation, Authorisation and Restriction of Chemicals (REACH), Bluesign, Zero Discharge of Hazardous Chemicals (ZDHC) Manufacturing Restricted Substances List (MRSL), and OEKO-TEX requirements increase the value of pre-certified formulations. ZDHC plans to publish updated PFAS guidance in October 2026, and mills adopting alternatives must validate wash durability and end-use performance before conversion.
Wastewater, Toxicity, and Substance-Restriction Compliance Costs
Compliance costs are constraining margins across the finishing chemicals market, especially where discharge and substance restrictions are stringent. The United States Environmental Protection Agency has indicated that it will proceed with effluent limitation guidelines addressing PFAS discharges from metal finishers. These requirements add to National Pollutant Discharge Elimination System permit obligations for affected facilities. A 2025 review examined the economic effects of PFAS regulations in the United States pulp and paper sector. Germany's 2025 environmental barometer found that nearly 50% of chemical and manufacturing companies viewed expanding chemical regulations as complex and time-consuming. Smaller formulators face a greater burden because they must fund compliance work while developing PFAS-free products.
Other drivers and restraints analyzed in the detailed report include:
- Packaging, Furniture, Electric Vehicle, and Electronics Demand
- Mill and Tannery Qualification Lock-In
- Petrochemical Feedstock and Energy Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Textile finishing chemicals held 27.56% of the finishing chemicals market share in 2025 and are projected to advance at a 5.81% CAGR through 2031. The segment combines conventional softeners and repellents with antimicrobial, ultraviolet-protective, and flame-retardant finishes. Functional products are becoming more important as technical textiles are adopted in automotive interiors, healthcare products, and protective apparel. In February 2025, Archroma and BW Converting demonstrated a digital spray finishing unit at Monforts' Advanced Technology Center in Monchengladbach, Germany. The system can reduce water, chemistry, and energy use by up to 50% compared with conventional pad application. These process changes encourage the use of more concentrated, high-value formulations.
Metal finishing chemicals benefit from automotive, electric vehicle, and electronics requirements. Wood finishing chemicals serve residential construction and furniture applications. Leather finishing chemicals are supported by use in luxury goods, automotive interiors, and lifestyle accessories. Paper finishing chemicals are seeing new qualification activity as food packaging shifts away from PFAS-based barrier coatings. The finishing chemicals market size for these categories is supported by water-based silicone and bio-based barrier alternatives, although their adoption depends on mill testing and certification. OEKO-TEX Standard 100, bluesign, and ZDHC MRSL are being applied across more substrate types, which favors suppliers that can provide certified products for several uses.
Complete Report Scope:
- By Product Type
- Textile Finishing Chemicals
- Metal Finishing Chemicals
- Wood Finishing Chemicals
- Leather Finishing Chemicals
- Paper Finishing Chemicals
- By Application
- Textile and Apparel Processing
- Automotive and Transportation
- Construction and Building Materials
- Electronics and Electrical
- Furniture and Home Furnishings
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 35.18% of the finishing chemicals market share in 2025 and is projected to advance at a 5.34% CAGR through 2031. The region has large textile-processing, automotive, electronics, and furniture manufacturing bases. China's Petrochemical Industry Stable Growth Action Plan for 2025-2026 targeted chemical-industry value-added growth of more than 5% annually. India's textile exports reached USD 37.75 billion in fiscal year 2024-25, and PM MITRA parks support the adoption of ZDHC-compliant chemistry. In June 2026, Quaker Houghton opened a manufacturing site in Zhangjiagang and expanded its Shanghai laboratory, reflecting the need for local metal-finishing supply and technical support.
North America represents a major demand center for metal finishing products used in automotive, aerospace, and electric vehicle battery components. The United States Environmental Protection Agency guidelines for PFAS discharges are prompting reformulation of fluorine-free bath chemistries. National Pollutant Discharge Elimination System permits, and California PFAS restrictions are increasing compliance spending throughout the value chain. Mexico is receiving additional demand from automotive parts and electronics assembly capacity linked to nearshoring. The finishing chemicals market in the region benefits from high-value applications but faces significant qualification and environmental compliance requirements.
Europe is marked by intensive compliance-driven reformulation across textiles, leather, coatings, and metal treatment. The European Commission published its Chemicals Industry Action Plan in July 2025, combining REACH simplification with support for bio-based and circular chemical substitutes. Germany retains formulation research and development capabilities despite rising energy costs. South America has a smaller but growing demand base, with Brazil supporting textile chemicals and Mexico supported by garment and automotive parts exports. The Middle East and Africa also have emerging demand from Saudi Arabian industrial investment, alongside leather and textile activity in South Africa. These regions extend the finishing chemicals market beyond its largest manufacturing centers.
- Archroma
- BASF
- CLARIANT
- Covestro AG
- Dow
- DyStar Group
- Element Solutions Inc
- Evonik Industries AG
- Henkel AG & Co. KGaA
- Quaker Houghton
- RUDOLF Holding SE & Co. KG
- Stahl Holdings B.V.
- Tanatex Chemicals B.V.
- Wacker Chemie AG
- Zschimmer & Schwarz Chemie GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth of Technical and Performance Textiles
- 4.2.2 PFAS-Free and ZDHC-Compliant Formulation Demand
- 4.2.3 Packaging, Furniture, Electric Vehicle, and Electronics Demand
- 4.2.4 Mill and Tannery Qualification Lock-In
- 4.2.5 Digital Dosing and Closed-Loop Processing Economics
- 4.3 Market Restraints
- 4.3.1 Wastewater, Toxicity, and Substance-Restriction Compliance Costs
- 4.3.2 Petrochemical Feedstock and Energy Price Volatility
- 4.3.3 Reformulation, Requalification, and Conversion Downtime
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Textile Finishing Chemicals
- 5.1.2 Metal Finishing Chemicals
- 5.1.3 Wood Finishing Chemicals
- 5.1.4 Leather Finishing Chemicals
- 5.1.5 Paper Finishing Chemicals
- 5.2 By Application
- 5.2.1 Textile and Apparel Processing
- 5.2.2 Automotive and Transportation
- 5.2.3 Construction and Building Materials
- 5.2.4 Electronics and Electrical
- 5.2.5 Furniture and Home Furnishings
- 5.2.6 Other Applications
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Archroma
- 6.4.2 BASF
- 6.4.3 CLARIANT
- 6.4.4 Covestro AG
- 6.4.5 Dow
- 6.4.6 DyStar Group
- 6.4.7 Element Solutions Inc
- 6.4.8 Evonik Industries AG
- 6.4.9 Henkel AG & Co. KGaA
- 6.4.10 Quaker Houghton
- 6.4.11 RUDOLF Holding SE & Co. KG
- 6.4.12 Stahl Holdings B.V.
- 6.4.13 Tanatex Chemicals B.V.
- 6.4.14 Wacker Chemie AG
- 6.4.15 Zschimmer & Schwarz Chemie GmbH
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

