PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154878

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154878
South America Pharmaceutical Glass Vials and Ampoules - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
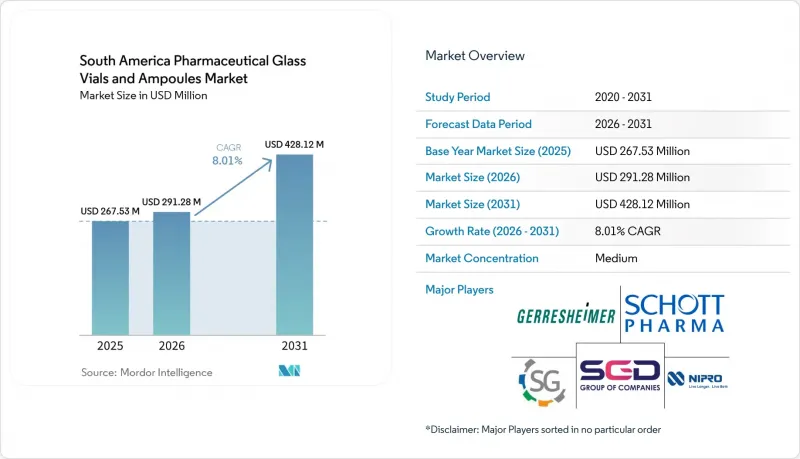
According to Mordor Intelligence, the South America pharmaceutical glass vials and Ampoules Market size was valued at USD 267.53 million in 2025 and estimated to grow from USD 291.28 million in 2026 to reach USD 428.12 million by 2031, at a CAGR of 8.01% during the forecast period (2026-2031).
South America Pharmaceutical Glass Vials and Ampoules Market Trends and Insights
Expansion of Injectable Drug Manufacturing
Injectable medicine projects are increasing demand for qualified vials and ampoules in the South America Pharmaceutical Glass Vials and Ampoules Market. Novo Nordisk committed DKK 8 billion (USD 1.10 billion) in April 2025 to expand injectable treatment production in Montes Claros, Brazil, with completion expected in 2028. The project includes aseptic lines, cold storage, and a quality-control laboratory, while each fill-finish line needs a validated container system before medicines can be released. Hipolabor announced BRL 330 million (USD 58.9 million) in phased investment for 2026 to 2028, and Ache began operating a 40 million-unit injectable and ophthalmic facility in Pernambuco in February 2026. These projects create demand near manufacturing clusters and make fast supplier substitution difficult. Suppliers that meet delivery and validation requirements are better placed to serve this demand.
Growth of Vaccine and Biosimilar Production
Vaccine and biosimilar production supports the South America Pharmaceutical Glass Vials and Ampoules Market because these medicines are commonly administered by injection. Brazil and India formalized 3 Productive Development Partnerships in February 2026 to support local production of biosimilars for nivolumab and pertuzumab, while Blau Farmaceutica completed domestic development of a pembrolizumab biosimilar in January 2026. These products need containers that protect sensitive formulations, with Type I borosilicate glass relevant for protein stability and extractables control. Fiocruz's Novo Centro de Processamento Final is designed to produce 120 million vials annually once operational. Patent expiries for pembrolizumab in 2028 and semaglutide in 2026 are encouraging biosimilar preparation. This activity shifts procurement toward recurring supply agreements established early in the production plan.
High Energy Intensity of Pharmaceutical Glass Melting
Glass furnaces for pharmaceutical products operate above 1,500°C, exposing the South America Pharmaceutical Glass Vials and Ampoules Market to fluctuations in energy costs. Energy accounted for 25% to 35% of tubular-glass conversion costs in the supplied research, while Brazilian natural-gas prices can reflect import parity and exchange-rate movements. These conditions pressure converters when pharmaceutical customers cannot accept higher packaging prices. Parglass plans to invest USD 85 million in a 100% electric glass furnace at Villa Hayes, Paraguay. Smaller converters may struggle to fund comparable programs and face greater cost and sustainability pressure. This can favor established suppliers with diversified furnace networks and energy arrangements.
Other drivers and restraints analyzed in the detailed report include:
- Rising Demand for Type I Glass Containers
- Increasing Regional Pharmaceutical Self-Sufficiency
- Stringent Container-Closure and Extractables Qualification
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Vials held 70.12% of the South America Pharmaceutical Glass Vials and Ampoules Market share in 2025 and are forecast to grow at an 8.57% CAGR through 2031. Vaccines, hospital injectables, and biologics all rely on vial formats across the region. Vials are compatible with lyophilization, which supports the stability of some biologics and biosimilars. This makes the format important as the therapeutic mix becomes more complex. Public vaccination programs also use single-dose and multi-dose vial configurations.
Ampoules continue to play an important role in single-dose medicines and emergency treatments. Their hermetic seal and tamper-evident form suit analgesics, contrast agents, and critical-care medicines. Demand is especially relevant in Argentine hospital formularies and other South American hospital systems. SGD Pharma returned to FCE Pharma 2026 in Sao Paulo with its tubular glass ampoule portfolio. The South America Pharmaceutical Glass Vials and Ampoules Market will continue to require both formats because their clinical uses remain distinct.
Type I borosilicate glass accounted for 61.45% of revenue in 2025 and is forecast to grow at an 8.78% CAGR through 2031. Its resistance to hydrolytic attack is important for parenteral medicines that are sensitive to pH changes or alkali leachables. Biologics and protein-based therapies have increased the need for these container properties. The South America Pharmaceutical Glass Vials and Ampoules Market size for Type I formats is supported by local biosimilar and specialty-injectable projects. Suppliers with consistent tubing quality can be better positioned in regulated applications.
Type II-treated soda-lime glass remains relevant for aqueous small-molecule injectables, where chemical sensitivity is lower. Type III soda-lime glass continues to be used for dry powders and some non-parenteral applications. SCHOTT Pharma's FIOLAX(R) Pro roadmap shows how suppliers are emphasizing Type I glass for higher-value uses. Changing from Type II to Type I requires a full qualification cycle at a fill-finish facility. This can encourage early adoption of Type I formats when new biologic capacity is planned.
Complete Report Scope:
- By Product Type
- Vials
- Ampoules
- By Glass Type
- Type I Borosilicate Glass
- Type II Treated Soda-Lime Glass
- Type III Soda-Lime Glass
- By Manufacturing Process
- Tubular Glass Forming
- Molded Glass Forming
- Ready-to-Use Sterile Conversion
- By Application
- Vaccines
- Biologics and Biosimilars
- Small-Molecule Injectables
- Insulin and Other Peptide Therapies
- Diagnostic Reagents
- By Geography
- Brazil
- Chile
- Argentina
- Rest of South America
List of Companies Covered in this Report:
- Gerresheimer AG
- SCHOTT Pharma AG & Co. KGaA
- Stevanato Group S.p.A.
- SGD S.A.
- Nipro Corporation
- DWK Life Sciences GmbH
- Stoelzle Oberglas GmbH
- Shandong Pharmaceutical Glass Co., Ltd.
- Chongqing Zhengchuan Pharmaceutical Packaging Co., Ltd.
- Cangzhou Four Stars Glass Co., Ltd.
- Piramida d.o.o.
- Alphial S.r.l.
- Nuova Ompi S.r.l.
- Arab Pharmaceutical Glass Company S.A.E.
- Namicos Corporation
- Kapoor Glass India Pvt. Ltd.
- Jinan Munan Pharm Glass Co., Ltd.
- Pacific Vial Manufacturing Inc.
- Borosil Limited
- Adelphi Manufacturing Ltd.
- Manaksia Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Injectable Drug Manufacturing
- 4.2.2 Growth of Vaccine and Biosimilar Production
- 4.2.3 Mainstream, Rising Demand for Type I Glass Containers
- 4.2.4 Increasing Regional Pharmaceutical Self-Sufficiency
- 4.2.5 Qualification of Local Fill-and-Finish Capacity
- 4.2.6 Container Availability as a Continuity-of-Supply Differentiator
- 4.3 Market Restraints
- 4.3.1 High Energy Intensity of Pharmaceutical Glass Melting
- 4.3.2 Stringent Container-Closure and Extractables Qualification
- 4.3.3 Import Exposure to Specialized Tubular Glass and RTU Formats
- 4.3.4 Breakage and Reject Costs on Long Multimodal Routes
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Supply Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Vials
- 5.1.2 Ampoules
- 5.2 By Glass Type
- 5.2.1 Type I Borosilicate Glass
- 5.2.2 Type II Treated Soda-Lime Glass
- 5.2.3 Type III Soda-Lime Glass
- 5.3 By Manufacturing Process
- 5.3.1 Tubular Glass Forming
- 5.3.2 Molded Glass Forming
- 5.3.3 Ready-to-Use Sterile Conversion
- 5.4 By Application
- 5.4.1 Vaccines
- 5.4.2 Biologics and Biosimilars
- 5.4.3 Small-Molecule Injectables
- 5.4.4 Insulin and Other Peptide Therapies
- 5.4.5 Diagnostic Reagents
- 5.5 By Geography
- 5.5.1 Brazil
- 5.5.2 Chile
- 5.5.3 Argentina
- 5.5.4 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Gerresheimer AG
- 6.4.2 SCHOTT Pharma AG & Co. KGaA
- 6.4.3 Stevanato Group S.p.A.
- 6.4.4 SGD S.A.
- 6.4.5 Nipro Corporation
- 6.4.6 DWK Life Sciences GmbH
- 6.4.7 Stoelzle Oberglas GmbH
- 6.4.8 Shandong Pharmaceutical Glass Co., Ltd.
- 6.4.9 Chongqing Zhengchuan Pharmaceutical Packaging Co., Ltd.
- 6.4.10 Cangzhou Four Stars Glass Co., Ltd.
- 6.4.11 Piramida d.o.o.
- 6.4.12 Alphial S.r.l.
- 6.4.13 Nuova Ompi S.r.l.
- 6.4.14 Arab Pharmaceutical Glass Company S.A.E.
- 6.4.15 Namicos Corporation
- 6.4.16 Kapoor Glass India Pvt. Ltd.
- 6.4.17 Jinan Munan Pharm Glass Co., Ltd.
- 6.4.18 Pacific Vial Manufacturing Inc.
- 6.4.19 Borosil Limited
- 6.4.20 Adelphi Manufacturing Ltd.
- 6.4.21 Manaksia Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

