PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154927

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154927
South America Conveyors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
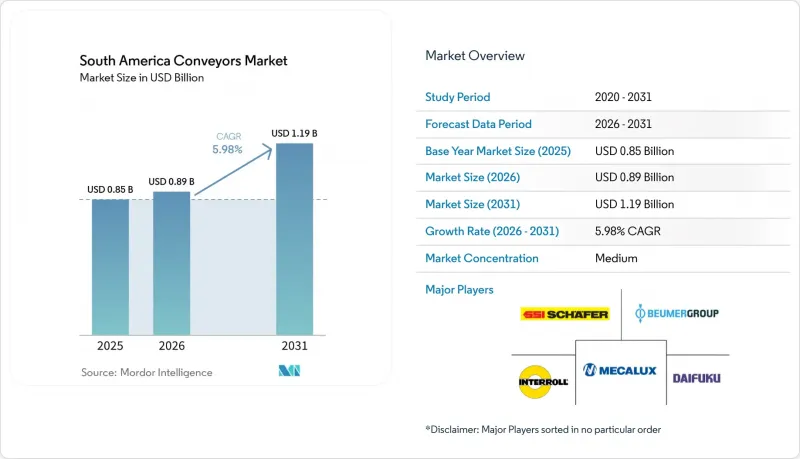
According to Mordor Intelligence, the South America conveyors market size was valued at USD 0.85 billion in 2025 and is estimated to grow from USD 0.89 billion in 2026 to reach USD 1.19 billion by 2031, at a CAGR of 5.98% during the forecast period (2026-2031).
South America Conveyors Market Trends and Insights
Mining CAPEX And Pit-To-Plant Conveyor Retrofits
Mining investment supports demand for long-distance and high-capacity equipment in the South America conveyors market, particularly in operations involving copper, iron ore, and lithium, where material must be moved through difficult terrain from extraction sites to crushers and processing plants. The draft projected mining CAPEX across 32 active regional companies at USD 81.9 billion in 2026, up from USD 75.5 billion in 2025, reflecting only 2% growth in 2025. Mine operators are prioritizing electrified pit-to-plant systems to reduce reliance on diesel haul trucks, manage energy costs, and maintain continuous movement between operating stages. TAKRAF received a January 2025 order for 3 conveyors at Minera Collahuasi's Ujina growth project in Chile, connecting a relocated crushing station to the existing ore network at 4,535 meters above sea level. New installations increasingly include condition monitoring, automated inspection tools, and predictive maintenance platforms, which can extend supplier activity beyond the initial equipment sale into maintenance, analytics, and support services.
E-Commerce Fulfillment And Warehouse Automation
E-commerce fulfillment investment is strengthening demand for unit-handling equipment in the South America conveyors market, as operators build faster and more controlled flows for parcels, orders, returns, and inventory within distribution facilities. Mercado Libre deployed 125 robotic separators at its Cajamar distribution center near Sao Paulo, with a capacity to process 105,000 items per day, as part of its fulfillment modernization. Correo Argentino opened a robotic package-sorting system in December 2025, featuring 240 autonomous robots and a conveyor sorter processing 9,000 parcels per hour. Roller and modular lines can generate recurring upgrades as throughput, fulfillment layouts, robot deployments, and product assortments change, providing suppliers with a source of activity less dependent on mining investment cycles. Warehouse operators also require equipment that can work with sorting software, picking processes, packaging stations, and delivery cutoffs, making controls and integration services important alongside the physical conveyor line.
High Initial Capital Investment
Initial costs remain a restraint for the South America conveyors market, especially for overland mining systems longer than 10 km that require specialized engineering, structural works, power systems, and extensive installation activity. Full installations can require investments from tens of millions to more than USD 100 million, placing them outside the immediate capital plans of many smaller operators. High interest rates in Brazil and persistent inflation in Argentina can extend project payback assessments and increase the appeal of keeping older assets in service. Smaller manufacturers and retailers may retain existing equipment, add maintenance work, or phase in smaller purchases instead of approving a full line replacement. Brazilian ABNT safety requirements, environmental documentation, and lender ESG covenants can add specification, testing, reporting, and financing work before procurement, placing a greater burden on operators with limited internal engineering capacity.
Other drivers and restraints analyzed in the detailed report include:
- Manufacturing Modernization In Brazil
- Infrastructure And Port Development
- Economic Volatility and Project-Approval Delays
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Belt conveyors held 34.72% of the South America conveyors market share in 2025, supported by continuous ore hauling across long distances and changing elevations. Fabric and steel-cord belt designs are suited to high tonnage and extended operating periods at mining sites. TAKRAF's January 2025 Collahuasi order covered 3 overland conveyors for a copper mine growth project in Chile. Heavy belt systems also serve processing plants, stockyards, agricultural operations, and port terminals. Their installed base creates demand for belts, idlers, pulleys, controls, inspection, and service. Continental introduced its VersaFlex single-ply belt in Brazil during May 2026 for surface and open-pit mining applications. The product used High-Performance Polyester to reduce belt weight and associated carbon impact. These product changes show that lifecycle cost and energy performance are increasingly considered with throughput capacity. Mining buyers also consider replacement intervals, local service availability, safety performance, and the ability to incorporate monitoring devices when assessing a belt solution for a major project.
Roller conveyors are projected to expand at a 6.43% CAGR through 2031 in the South America conveyors market. Fulfillment centers use them for accumulation, sorting, transfers, and order handling. Zone-controlled roller systems can operate alongside autonomous mobile robots in automated warehouse layouts. The Correo Argentino sorting system combined robots with a sorter conveyor capable of processing 9,000 parcels each hour. Pallet conveyors support repeatable movement of loaded goods in factories and distribution centers. Overhead conveyors serve assembly operations where floor space must remain available. Slat, chain, screw, and pneumatic systems address automotive, airport, food, powder, and specialized bulk-handling applications. These categories broaden suppliers' exposure beyond mining-related projects. Their varied design requirements also allow suppliers to serve assembly, sorting, storage, handling, and processing tasks across a wider group of industrial and logistics customers.
Bulk handling accounted for 56.34% of the South America conveyors market size by load type in 2025. Mining, agriculture, and export logistics rely on the continuous movement of ore, grain, pulp, and other high-volume materials. Conveyor lines help link extraction, crushing, storage, rail, and port operations. Fixed bulk systems are commonly designed around site-specific tonnage, terrain, and operating conditions. Their scale supports demand for structural equipment, belts, pulleys, drives, controls, and maintenance. Port modernization and mining-processing projects keep this demand connected to export infrastructure. Large operators also evaluate energy use and reliability because unscheduled downtime can disrupt wider production systems. This operating need favors suppliers with relevant engineering and service capabilities. It also makes project design important because conveyor routes, transfer points, dust-control needs, and maintenance access must be tailored to each mine, terminal, or processing operation.
Unit handling is projected to expand at a 6.52% CAGR through 2031 in the South America conveyors market. Parcel growth supports investment in sortation conveyors, tilt-tray systems, and high-speed belt curves at fulfillment hubs. Brazil, Colombia, and Argentina are important locations for these projects. Operators are adding unit-handling subsystems to improve stock keeping unit traceability without disrupting bulk operations. This requirement supports modular layouts that can change with product mixes and throughput needs. Interroll's 2025 performance in the Americas reflected investment by courier, express, parcel, and fashion customers. Pharmaceutical and food distribution centers may also specify ISO 9001 quality-management practices in tenders. Compliance requirements can favor established suppliers with documented system performance. Buyers may assess equipment reliability, cleaning requirements, traceability needs, and integration with warehouse management processes before they select a unit-handling solution.
Complete Report Scope:
- By Product Type
- Belt Conveyors
- Roller Conveyors
- Pallet Conveyors
- Overhead Conveyors
- Slat/Chain Conveyors
- Screw and Pneumatic Conveyors
- By Load Type
- Unit Handling
- Bulk Handling
- By End-User Industry
- Airports
- Retail and E-commerce
- Automotive
- Food and Beverage
- Pharmaceuticals
- Mining and Quarrying
- Manufacturing (Discrete and Process)
- Other End-User Industries
- By System Configuration
- Fixed/Linear
- Modular/Flexible
- By Component
- Conveying Equipment
- Drives and Controls
- Software and Analytics
- By Geography
- Brazil
- Argentina
- Chile
- Colombia
- Rest of South America
List of Companies Covered in this Report:
- BEUMER Group GmbH & Co. KG
- Interroll Holding AG
- Daifuku Co., Ltd.
- Mecalux, S.A.
- SSI SCHAFER AG
- Dorner Mfg. Corp.
- Hytrol Conveyor Company, Inc.
- TAKRAF GmbH
- PROK Pty Ltd
- Dos Santos International, LLC
- RULMECA S.p.A.
- The Flexible Steel Lacing Company
- Conveyor Dynamics, Inc.
- Martin Engineering Company
- Ashworth Bros., Inc.
- Cambelt International LLC
- Nitta Corporation
- Habasit AG
- Forbo International SA
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Mining CAPEX and Pit-to-Plant Conveyor Retrofits
- 4.2.2 E-Commerce Fulfillment and Warehouse Automation
- 4.2.3 Manufacturing Modernization in Brazil
- 4.2.4 Infrastructure and Port Development
- 4.2.5 Battery-Metal and Critical-Mineral Processing Expansion
- 4.2.6 Localized Conveyor Manufacturing and Service Capacity
- 4.3 Market Restraints
- 4.3.1 High Initial Capital Investment
- 4.3.2 Economic Volatility and Project-Approval Delays
- 4.3.3 Imported Component Dependence and Long Lead Times
- 4.3.4 Legacy-System Integration and Skilled-Maintenance Constraints
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Belt Conveyors
- 5.1.2 Roller Conveyors
- 5.1.3 Pallet Conveyors
- 5.1.4 Overhead Conveyors
- 5.1.5 Slat/Chain Conveyors
- 5.1.6 Screw and Pneumatic Conveyors
- 5.2 By Load Type
- 5.2.1 Unit Handling
- 5.2.2 Bulk Handling
- 5.3 By End-User Industry
- 5.3.1 Airports
- 5.3.2 Retail and E-commerce
- 5.3.3 Automotive
- 5.3.4 Food and Beverage
- 5.3.5 Pharmaceuticals
- 5.3.6 Mining and Quarrying
- 5.3.7 Manufacturing (Discrete and Process)
- 5.3.8 Other End-User Industries
- 5.4 By System Configuration
- 5.4.1 Fixed/Linear
- 5.4.2 Modular/Flexible
- 5.5 By Component
- 5.5.1 Conveying Equipment
- 5.5.2 Drives and Controls
- 5.5.3 Software and Analytics
- 5.6 By Geography
- 5.6.1 Brazil
- 5.6.2 Argentina
- 5.6.3 Chile
- 5.6.4 Colombia
- 5.6.5 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 BEUMER Group GmbH & Co. KG
- 6.4.2 Interroll Holding AG
- 6.4.3 Daifuku Co., Ltd.
- 6.4.4 Mecalux, S.A.
- 6.4.5 SSI SCHAFER AG
- 6.4.6 Dorner Mfg. Corp.
- 6.4.7 Hytrol Conveyor Company, Inc.
- 6.4.8 TAKRAF GmbH
- 6.4.9 PROK Pty Ltd
- 6.4.10 Dos Santos International, LLC
- 6.4.11 RULMECA S.p.A.
- 6.4.12 The Flexible Steel Lacing Company
- 6.4.13 Conveyor Dynamics, Inc.
- 6.4.14 Martin Engineering Company
- 6.4.15 Ashworth Bros., Inc.
- 6.4.16 Cambelt International LLC
- 6.4.17 Nitta Corporation
- 6.4.18 Habasit AG
- 6.4.19 Forbo International SA
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

