PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154957

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2154957
South America Optical Imaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the South America optical imaging market size was valued at USD 127.39 million in 2025 and is estimated to expand from USD 141.07 million in 2026 to reach USD 245.42 million by 2031, at a CAGR of 11.71% during the forecast period (2026-2031).
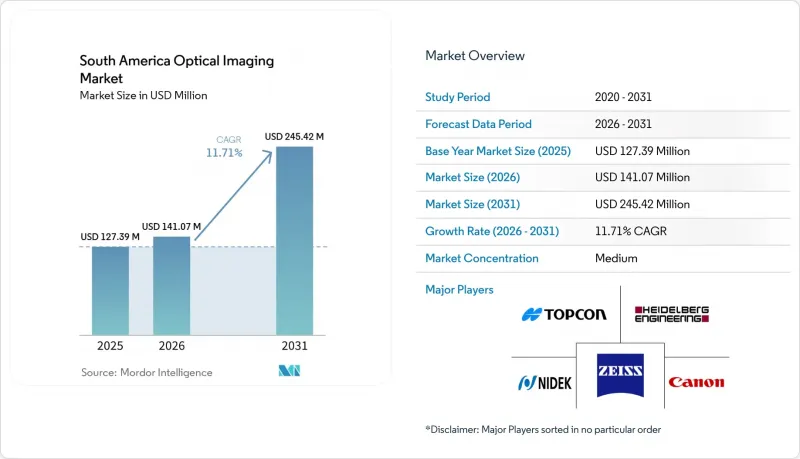
South America Optical Imaging Market Trends and Insights
Rising Prevalence of Retinal Disorders and Diabetes
Diabetes creates a direct demand for ophthalmic imaging because diabetic retinopathy requires regular retinal examination. A 2025 Sao Paulo primary-care study reported a 28.3% prevalence of diabetic retinopathy, with 65.1% of cases classified as mild nonproliferative disease. A 2025 study by the Brazilian Council of Ophthalmology, in northeastern Brazil, found that 78.1% of diabetic patients had difficulty scheduling an ophthalmology appointment, while 76.3% lacked a local public-sector ophthalmologist. Retinal imaging allows primary-care teams to assess patients before specialist referral and focus scarce specialist time on urgent cases. The South America optical imaging market gains when health systems reach people who have not received routine retinal screening. This favors devices and image-management tools that trained nonphysician staff can use reliably.
Expansion of Public Eye-Screening Programs
Public eye-screening programs are becoming a more regular source of procurement across South America. Mato Grosso acquired 250 Eyer2 portable retinographs in December 2025, distributed 70 devices to 69 municipalities, and trained 100 primary-care professionals. Brazil's public health system expanded retinograph procurement in June 2026 to support diabetic retinopathy screening in primary care centers. Portable devices create demand from facilities without space, electrical infrastructure, or budgets for complete imaging suites. ANVISA safety and performance requirements influence product specifications and favor suppliers with established registrations. The South America optical imaging market benefits when retinal imaging becomes part of population-level prevention rather than only hospital capital spending.
High Acquisition and Total Cost of Ownership
Premium platforms, including swept-source optical coherence tomography, hyperspectral imaging, and multimodal retinal systems, cost USD 50,000 to more than USD 150,000 per unit. These prices can exceed the authority of district-level hospitals and extend public procurement cycles. Factory service, calibration, software licensing, and operator training add material costs over a 5-7 year device life. These costs can reach 1.5-2.0 times the original purchase price. The burden concentrates high-acuity equipment in referral centers and private hospital groups. Smaller facilities may opt for portable systems with lower upfront costs, thereby reducing revenue per unit for premium equipment suppliers.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of AI-Enabled and Multimodal Imaging
- Growth of Tele-Ophthalmology and Remote Diagnostics
- Import Dependence, Tariffs, and Currency Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Imaging systems commanded 35.82% of the South America optical imaging market share in 2025. The South America optical imaging market includes optical coherence tomography, confocal scanning laser ophthalmoscopes, tabletop fundus cameras, and spectral imaging platforms. Hospitals, oncology centers, and universities use these systems for specialist clinical and research work. Their clinical breadth supports demand across ophthalmology, cardiology, and laboratory applications. Their higher cost makes service coverage, trained staff, and stable budgets important purchasing conditions.
Cameras are projected to expand at a 12.71% CAGR through 2031 within the South America optical imaging market. Mato Grosso's 2025 purchase of 250 Eyer2 retinographs shows the role of public tele-ophthalmology procurement. Portable formats serve sites with limited space, electrical infrastructure, and capital budgets. Software supports recurring revenue through diabetic retinopathy grading and glaucoma monitoring. Suppliers with existing registrations and distributor networks have an advantage in government tenders.
Ophthalmology accounted for 33.14% of the South America optical imaging market in 2025. Optical coherence tomography and fundus imaging are established tools for eye care and diabetic retinopathy screening. Dentistry and dermatology are secondary applications for near-infrared spectroscopy and optical coherence tomography. Cardiology uses coronary optical coherence tomography during interventional procedures, with Abbott Laboratories offering the Ilumien PCI platform. Neurology remains more research-focused because reimbursement pathways are limited.
Oncology is projected to expand at a 13.29% CAGR through 2031. Photoacoustic tomography and hyperspectral imaging support noninvasive tumor characterization and intraoperative margin assessment. In the South America optical imaging market, these methods can map angiogenesis, hypoxia gradients, and oxygen saturation without ionizing radiation or contrast agents. University infrastructure funded through FAPESP and CONICET supports biotechnology and research demand. Petrobras and Unicamp also use hyperspectral scanning for pre-salt core analysis, adding nonmedical demand.
Complete Report Scope:
- By Product
- Imaging Systems
- Optical Imaging Systems
- Spectral Imaging Systems
- Cameras
- Illumination Systems
- Lenses
- Software
- Imaging Systems
- By Application
- Ophthalmology
- Dentistry
- Dermatology
- Cardiology
- Neurology
- Oncology
- Biotechnology and Research
- Other Applications
- By Technique
- Optical Coherence Tomography
- Near-Infrared Spectroscopy
- Hyperspectral Imaging
- Photoacoustic Tomography
- By End-User
- Hospitals and Clinics
- Diagnostic Imaging Centres
- Research and Diagnostic Laboratories
- Other End-Users
- By Geography
- Brazil
- Argentina
- Colombia
- Rest of South America
List of Companies Covered in this Report:
- Carl Zeiss Meditec AG
- Topcon Corporation
- Heidelberg Engineering GmbH
- NIDEK CO., LTD.
- Canon Inc.
- Leica Microsystems GmbH
- Bruker Corporation
- CytoViva, Inc.
- PerkinElmer, Inc.
- Headwall Photonics, Inc.
- Olympus Corporation
- Nikon Corporation
- Eyenuk, Inc.
- Revenio Group Oyj
- Agfa-Gevaert N.V.
- Abbott Laboratories
- Koninklijke Philips N.V.
- Bausch + Lomb Incorporated
- Kowa Company, Ltd.
- Tomey Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Market Drivers
- 4.3.1 Rising Prevalence of Retinal Disorders and Diabetes
- 4.3.2 Expansion of Public Eye-Screening Programs
- 4.3.3 Adoption of AI-Enabled and Multimodal Imaging
- 4.3.4 Growth of Tele-Ophthalmology and Remote Diagnostics
- 4.3.5 Demand for Portable Imaging in Underserved Areas
- 4.3.6 Expansion of Biotechnology and Translational Research
- 4.4 Market Restraints
- 4.4.1 High Acquisition and Total Cost of Ownership
- 4.4.2 Import Dependence, Tariffs, and Currency Volatility
- 4.4.3 Uneven Service, Calibration, and Training Coverage
- 4.4.4 Long Replacement Cycles in Public Hospitals
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS, VALUE AND VOLUME
- 5.1 By Product
- 5.1.1 Imaging Systems
- 5.1.1.1 Optical Imaging Systems
- 5.1.1.2 Spectral Imaging Systems
- 5.1.2 Cameras
- 5.1.3 Illumination Systems
- 5.1.4 Lenses
- 5.1.5 Software
- 5.1.1 Imaging Systems
- 5.2 By Application
- 5.2.1 Ophthalmology
- 5.2.2 Dentistry
- 5.2.3 Dermatology
- 5.2.4 Cardiology
- 5.2.5 Neurology
- 5.2.6 Oncology
- 5.2.7 Biotechnology and Research
- 5.2.8 Other Applications
- 5.3 By Technique
- 5.3.1 Optical Coherence Tomography
- 5.3.2 Near-Infrared Spectroscopy
- 5.3.3 Hyperspectral Imaging
- 5.3.4 Photoacoustic Tomography
- 5.4 By End-User
- 5.4.1 Hospitals and Clinics
- 5.4.2 Diagnostic Imaging Centres
- 5.4.3 Research and Diagnostic Laboratories
- 5.4.4 Other End-Users
- 5.5 By Geography
- 5.5.1 Brazil
- 5.5.2 Argentina
- 5.5.3 Colombia
- 5.5.4 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Carl Zeiss Meditec AG
- 6.4.2 Topcon Corporation
- 6.4.3 Heidelberg Engineering GmbH
- 6.4.4 NIDEK CO., LTD.
- 6.4.5 Canon Inc.
- 6.4.6 Leica Microsystems GmbH
- 6.4.7 Bruker Corporation
- 6.4.8 CytoViva, Inc.
- 6.4.9 PerkinElmer, Inc.
- 6.4.10 Headwall Photonics, Inc.
- 6.4.11 Olympus Corporation
- 6.4.12 Nikon Corporation
- 6.4.13 Eyenuk, Inc.
- 6.4.14 Revenio Group Oyj
- 6.4.15 Agfa-Gevaert N.V.
- 6.4.16 Abbott Laboratories
- 6.4.17 Koninklijke Philips N.V.
- 6.4.18 Bausch + Lomb Incorporated
- 6.4.19 Kowa Company, Ltd.
- 6.4.20 Tomey Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

