PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155001

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155001
South America Gas Sensors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
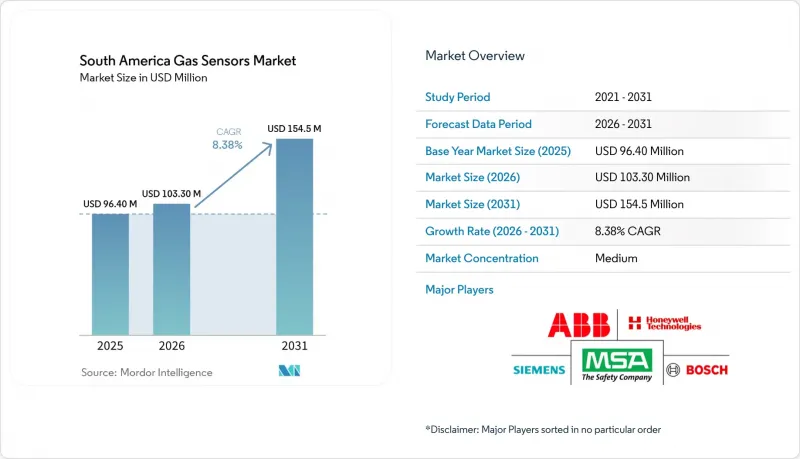
According to Mordor Intelligence, the South America gas sensors market size is projected to expand from USD 96.40 million in 2025 and USD 103.30 million in 2026 to USD 154.5 million by 2031, registering a CAGR of 8.38% between 2026 to 2031.
South America Gas Sensors Market Trends and Insights
Stricter Industrial Safety and Emissions Regulations
Brazil maintains a structured occupational safety framework through NR-15, NR-20, NR-33, and NR-35. These rules cover unhealthy activities, flammables, confined spaces, work at height, gas detector calibration, and protection in explosive atmospheres. ABNT revised ABNT NBR IEC 60079-29-2 in December 2024, strengthening requirements for selecting, installing, using, and maintaining flammable-gas and oxygen detectors. The revision increases documentation and calibration record requirements, which can bring replacement demand for legacy equipment that lacks the required records or cannot demonstrate continued performance against the updated requirements. Peru published its 2026 mining safety and health regulation in March 2026, extending formal gas-monitoring obligations to more mid-tier mining operations that had previously been less consistently covered by formal compliance requirements. A potential revision to Brazil's NR-15 could increase the use of continuous monitoring in sectors that still rely on periodic sampling.
Expansion of Oil and Gas, Mining, and Chemical Operations
BP announced a major oil and gas discovery at the Bumerangue block in Brazil's Santos Basin in August 2025. Future deepwater development would require fixed gas sensors for process safety, emergency shutdown systems, and operational integrity requirements. In Argentina, Vaca Muerta production plans by Vista Energy and YPF support demand for hydrocarbon and CO2 monitoring under provincial emissions reporting requirements. New petrochemical infrastructure near Anelo and Neuquen City also requires VOC and toxic-gas monitoring in confined spaces and loading areas. Electrochemical multi-gas instruments remain the normal specification for those applications, where workers may face a mix of hydrocarbon, carbon dioxide, and toxic-gas exposures during routine operations. Recovered industrial CO2 used in food-grade supply chains creates another use for purity sensors that is linked to petrochemical output rather than oil price movements.
High Installation and Lifecycle Costs
Fixed multi-point gas detection networks require certified wiring, commissioning, annual calibration, and sensor element replacement. In South American industrial facilities, those lifecycle requirements can cost 2 to 4 times the listed hardware price. Brazil's import duties on sensor components add 10-20% to landed costs compared with global benchmarks. This cost structure can delay refresh cycles and helps explain the continued use of older wired systems, even where newer architectures could reduce the amount of cable, scaffolding, and site work required. A Brazilian systematic review found that low-cost air-quality sensor nodes in South America ranged from USD 71 to USD 1,573 before calibration services. Remote operators are giving more attention to NDIR and MEMS designs with service intervals of 3 years or more, rather than electrochemical cells that may require replacement after 12-24 months.
Other drivers and restraints analyzed in the detailed report include:
- Methane-Leak Detection for Remote Production Assets
- Growth in Smart-City and Indoor-Air-Quality Monitoring
- Sensor Interference, Drift, and Calibration Burden
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Gas type selection remains closely tied to the source of exposure and the monitoring purpose at each facility, including worker protection, leak identification, process control, air-quality oversight, and food storage integrity. This keeps multi-gas configurations important, where flammable, toxic, and oxygen-deficient conditions can occur together.
Hydrocarbons (VOC/CH4) held 26.10% of the South America gas sensors market share in 2025. The segment reflects flammable-gas exposure in upstream oil and gas, steel, and chemical operations across Brazil, Argentina, and Colombia. Catalytic bead instruments and multi-gas electrochemical devices configured for lower-explosive-limit monitoring remain standard equipment in refineries and industrial plants. Their broad installed base supports replacement demand where operators must maintain coverage in hazardous locations, particularly where refineries, production facilities, and chemical plants cannot safely operate without continuous monitoring.
CO2 is the fastest-expanding gas type through 2031. Building automation, HVAC optimization, food and beverage cold chains, and offshore monitoring needs at high-CO2 pre-salt reservoirs support this demand. BP's Bumerangue discovery contains elevated CO2 in associated gas, creating a further need for CO2 sensing if the block moves into development. O2 sensors retain a stable role in confined-space verification, while H2S and SO2 devices support sour-gas processing and sulfuric acid operations in Chilean and Peruvian mining. NOx monitoring is also extending through urban programs in Sao Paulo, Bogota, and Santiago as ambient air standards tighten.
The category therefore serves both heavy industrial safety needs and a wider set of commercial and civic applications, allowing suppliers to address exposure risks in production environments as well as ventilation, storage, and ambient monitoring needs. That range reduces reliance on any single industrial purchasing cycle.
MEMS semiconductor optical devices are forecast to expand at a CAGR of 10.15% through 2031, the highest rate across technology types. Their smaller size and lower power use suit battery-powered equipment, IoT wearables, and LoRaWAN nodes. A 2026 study described an integrated NDIR CO2 sensor built on a single silicon substrate with improved optical coupling and rapid gas exchange. These technical characteristics are relevant to industrial and civic deployments that operate in humid or thermally variable conditions, where sensor footprint, power draw, and the ability to exchange gas rapidly affect installation choices.
Electrochemical technology retains the deepest installed base in the South America gas sensors industry. It remains widely specified for CO, H2S, and O2 monitoring where parts-per-million sensitivity and established calibration procedures are important. PID sensors support VOC monitoring for petrochemical hygiene and industrial exposure assessments. NDIR devices are expanding from process safety into building systems as CO2 requirements become more common in offices, schools, and hospitals. Catalytic bead products remain a cost-effective option for fixed combustible-gas monitoring when NDIR's higher unit cost is not justified, especially at sites that already have mature hard-wired detection systems and established maintenance practices.
Technology choice also depends on service intervals, available power, operating conditions, and the type of gas that requires detection. These considerations preserve demand for several established sensing methods.
Complete Report Scope:
- By Gas Type
- Oxygen
- Carbon Monoxide (CO)
- Carbon Dioxide ( CO2)
- Nitrogen Oxides (NOx)
- Hydrocarbons (VOC/CH4)
- Other Gases ( SO2, H2S)
- By Technology
- Electrochemical
- Photo-Ionization (PID)
- Solid-State / MOS
- Catalytic Bead
- Non-Dispersive Infrared (NDIR)
- MEMS-Semiconductor Optical
- By Form Factor
- Fixed / In-Situ Modules
- Portable / Hand-Held Devices
- Wearable Badges / Patches
- By Connectivity
- Wired (4-20 mA, CAN, RS-485)
- Wireless (BLE, NB-IoT, LoRaWAN)
- By End-Use Industry
- Industrial Safety and Process (Oil and Gas, Chemicals)
- Automotive Powertrain and HVAC
- Building Automation / Smart Homes
- Medical and Life-Science Equipment
- Food, Beverage, and Cold-Chain Logistics
- Environmental Monitoring and Smart City Nodes
- Other End-Use Industries
- By Country
- Brazil
- Argentina
- Colombia
- Rest of South America
List of Companies Covered in this Report:
- ABB Ltd.
- Honeywell International Inc.
- MSA Safety Incorporated
- Dragerwerk AG & Co. KGaA
- Siemens AG
- Robert Bosch GmbH
- Amphenol Corporation
- Industrial Scientific Corporation
- Blackline Safety Corporation
- Crowcon Detection Instruments Limited
- RIKEN KEIKI CO., LTD.
- Figaro Engineering Inc.
- Nemoto & Co., Ltd.
- Dynament Ltd.
- MEMBRAPOR AG
- Trolex Ltd.
- Sensirion AG
- Process Sensing Technologies
- GfG Gesellschaft fur Geratebau mbH
- SENKO CO., LTD.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Market Drivers
- 4.3.1 Stricter Industrial Safety and Emissions Regulations
- 4.3.2 Expansion of Oil and Gas, Mining, and Chemical Operations
- 4.3.3 Growth in Smart-City and Indoor-Air-Quality Monitoring
- 4.3.4 Connected-Worker and Wireless Sensor Deployments
- 4.3.5 Lithium and Copper Project Monitoring Requirements
- 4.3.6 Methane-Leak Detection for Remote Production Assets
- 4.4 Market Restraints
- 4.4.1 High Installation and Lifecycle Costs
- 4.4.2 Sensor Interference, Drift, and Calibration Burden
- 4.4.3 Limited Local Service and Calibration Infrastructure
- 4.4.4 Fragmented Procurement Across Small Industrial Operators
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Gas Type
- 5.1.1 Oxygen
- 5.1.2 Carbon Monoxide (CO)
- 5.1.3 Carbon Dioxide ( CO2)
- 5.1.4 Nitrogen Oxides (NOx)
- 5.1.5 Hydrocarbons (VOC/CH4)
- 5.1.6 Other Gases ( SO2, H2S)
- 5.2 By Technology
- 5.2.1 Electrochemical
- 5.2.2 Photo-Ionization (PID)
- 5.2.3 Solid-State / MOS
- 5.2.4 Catalytic Bead
- 5.2.5 Non-Dispersive Infrared (NDIR)
- 5.2.6 MEMS-Semiconductor Optical
- 5.3 By Form Factor
- 5.3.1 Fixed / In-Situ Modules
- 5.3.2 Portable / Hand-Held Devices
- 5.3.3 Wearable Badges / Patches
- 5.4 By Connectivity
- 5.4.1 Wired (4-20 mA, CAN, RS-485)
- 5.4.2 Wireless (BLE, NB-IoT, LoRaWAN)
- 5.5 By End-Use Industry
- 5.5.1 Industrial Safety and Process (Oil and Gas, Chemicals)
- 5.5.2 Automotive Powertrain and HVAC
- 5.5.3 Building Automation / Smart Homes
- 5.5.4 Medical and Life-Science Equipment
- 5.5.5 Food, Beverage, and Cold-Chain Logistics
- 5.5.6 Environmental Monitoring and Smart City Nodes
- 5.5.7 Other End-Use Industries
- 5.6 By Country
- 5.6.1 Brazil
- 5.6.2 Argentina
- 5.6.3 Colombia
- 5.6.4 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Honeywell International Inc.
- 6.4.3 MSA Safety Incorporated
- 6.4.4 Dragerwerk AG & Co. KGaA
- 6.4.5 Siemens AG
- 6.4.6 Robert Bosch GmbH
- 6.4.7 Amphenol Corporation
- 6.4.8 Industrial Scientific Corporation
- 6.4.9 Blackline Safety Corporation
- 6.4.10 Crowcon Detection Instruments Limited
- 6.4.11 RIKEN KEIKI CO., LTD.
- 6.4.12 Figaro Engineering Inc.
- 6.4.13 Nemoto & Co., Ltd.
- 6.4.14 Dynament Ltd.
- 6.4.15 MEMBRAPOR AG
- 6.4.16 Trolex Ltd.
- 6.4.17 Sensirion AG
- 6.4.18 Process Sensing Technologies
- 6.4.19 GfG Gesellschaft fur Geratebau mbH
- 6.4.20 SENKO CO., LTD.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

