PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155008

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155008
Modular Machine Vision Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
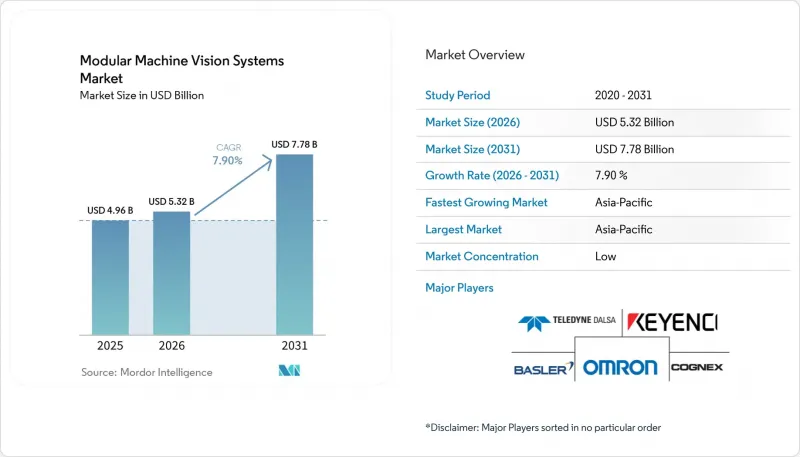
According to Mordor Intelligence, the modular machine vision systems market size was valued at USD 4.96 billion in 2025 and is estimated to grow from USD 5.32 billion in 2026 to reach USD 7.78 billion by 2031, at a CAGR of 7.90% during the forecast period (2026-2031).
Global Modular Machine Vision Systems Market Trends and Insights
Factory Automation and Industry 4.0 Adoption
Smart manufacturing investment is a major force behind the modular machine vision systems market. Manufacturers need inspection systems that can be adjusted as product designs and production volumes change. Open communication standards make it easier to link cameras, lighting, processors, and plant controls. This requirement supports modular systems with compatible input and output modules. Japan, Germany, and China are important manufacturing centers where modernization programs are influencing procurement decisions. In these locations, compliance requirements can affect the timing of upgrades as much as the expected financial return.
AI-Enabled Defect Detection and Process Optimization
AI-based defect detection is moving from pilot projects into production use across the modular machine vision systems market. NVIDIA reported 98.51% accuracy for die-level semiconductor defect classification using a vision foundation model and self-supervised learning. The approach also reduced the labeled data needed for specialized inspection tasks. This matters where defects occur rarely and labeled images are limited. A 2025 review found that deep learning outperformed classical machine learning in several industrial inspection settings when datasets included more than 10,000 samples. Processing modules that support these models can reduce annotation and retraining work over the system life cycle.
High System Integration and Lifecycle Costs
Total ownership costs can be higher than buyers expect in the modular machine vision systems market. Hardware can represent 40-60% of a project cost, while integration engineering, licenses, calibration, and lighting design make up the balance. Multi-vendor configurations can need custom middleware to ensure compatibility between component layers. Lens and lighting modules also have different replacement schedules. This makes maintenance more complicated than it is for a monolithic smart camera. Standard interfaces and certification programs can reduce this burden, but adoption remains uneven across the vendor base.
Other drivers and restraints analyzed in the detailed report include:
- Electronics, Semiconductor, and Battery Inspection Complexity
- Vision-Guided Robotics and Autonomous Material Handling
- Shortage of Machine Vision Integration Skills
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Camera and Imaging Modules held 31.56% of the modular machine vision systems market share in 2025. Camera selection drives choices for resolution, sensor format, shutter type, and interface protocol. It therefore affects many later decisions within a modular system. Optics and Lens Modules, Lighting Modules, and Image Acquisition and Interface Modules make up the next group of hardware spending. Tunable LED lighting is gaining attention where surface texture or material composition must be distinguished. Processing and Computing Modules have also changed as edge-capable AI accelerators become part of higher-performance systems.
Cognex introduced its In-Sight 6900 Vision Controller in April 2026 with NVIDIA Jetson technology and up to 157 TOPS of AI performance. Vision Software and AI Modules are projected to record the fastest component CAGR at 9.11% through 2031. Software creates a closer customer relationship because it can support training, refinement, and deployment across several sites. Cognex made OneVision generally available in May 2026 after a beta involving more than 100 enterprise customers. I/O and Communication Modules remain relatively standardized, but demand for OPC-UA-ready interfaces is improving where digital manufacturing programs specify compatible data connections.
2D Vision Systems accounted for 68.76% of the modular machine vision systems market size in 2025. Their large installed base reflects familiar integration methods, established software support, and a lower cost per inspection point. Packaging, electronics assembly, and logistics code-reading commonly use high-speed global-shutter cameras. LMI Technologies launched Gocator 2D Smart Cameras in January 2026 with edge-native AI, IP67 enclosures, and support for up to 84 frames per second. These capabilities can extend 2D deployment into settings that previously needed a more costly 3D configuration.
3D Vision Systems are used in bin picking, solder-joint inspection, and automotive body-gap measurement, where depth information is necessary. Basler and Orbbec announced an industrial 3D vision partnership in March 2026, including the Basler Stereo mini for autonomous mobile robot and automated guided vehicle navigation. Hyperspectral and Multispectral Imaging Systems are projected to expand at a 9.88% CAGR through 2031. Lower detector costs and on-chip neural networks have reduced inference latency to less than 10 milliseconds on snapshot cameras. Food sorting, pharmaceutical inspection, battery-cathode verification, and incoming material authentication need spectral information that RGB systems cannot provide.
Complete Report Scope:
- By Modular Component
- Camera and Imaging Modules
- Optics and Lens Modules
- Lighting Modules
- Image Acquisition and Interface Modules
- Processing and Computing Modules
- Vision Software and AI Modules
- I/O and Communication Modules
- By Imaging Type
- 2D Vision Systems
- 3D Vision Systems
- Hyperspectral and Multispectral Imaging Systems
- By Application
- Inspection and Defect Detection
- Measurement and Metrology
- Identification and Code Reading
- Guidance and Positioning
- Other Applications
- By End-User Industry
- Automotive
- Electronics and Semiconductors
- Food and Beverage
- Healthcare and Pharmaceuticals
- Logistics and Retail
- Packaging
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of the Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific held 38.76% of the modular machine vision systems market share in 2025 and is projected to expand at an 8.32% CAGR through 2031. China has the largest national demand in the region, with semiconductor automated optical inspection, AI-enabled vision systems, and robot vision attracting investment. Japan is upgrading older inspection lines as manufacturers adopt interoperable factory systems. South Korea needs high-speed line-scan and metrology-grade sensors for semiconductor memory and display panels. Basler acquired a 76% stake in Alpha TechSys Automation in October 2025 and rebranded it as Basler India, strengthening its sales and service presence in India.
North America and Europe together form the second-largest combined demand area in the modular machine vision systems market. The United States has a strong demand for AI vision software and semiconductor capital equipment integration. Defense and national security programs also favor on-device systems that keep inference data local. Germany anchors European demand through automotive suppliers and precision engineering companies. The United Kingdom, France, Italy, and Spain focus more on packaging machinery and food and beverage inspection. Canada and Mexico benefit from semiconductor and automotive supply-chain investment, though their volumes are lower than those of the United States.
The Middle East and Africa are at earlier stages of adoption, but manufacturing investment is creating new opportunities. Saudi Arabia and the United Arab Emirates are building domestic manufacturing capacity, which supports vision-guided inspection in new pharmaceutical, food processing, and electronics plants. Greenfield projects can reduce integration barriers because modular standards are included in line design from the start. South Africa has the most established machine vision demand in Africa, driven by automotive assembly and food processing. Brazil leads South America, where automotive and food processing support structured investment. Argentina and other South American countries remain smaller opportunities as capital equipment becomes more affordable.
- Cognex Corporation
- KEYENCE CORPORATION
- Basler AG
- Teledyne Technologies Incorporated
- OMRON Corporation
- Allied Vision Technologies GmbH
- IDS Imaging Development Systems GmbH
- MVTec Software GmbH
- LMI Technologies Inc.
- Matrox Imaging Inc.
- Euresys S.A.
- Chromasens GmbH
- JAI A/S
- Vieworks Co., Ltd.
- Tordivel AS
- Opto Engineering S.p.A.
- A&B Software LLC
- Advanced Illumination, Inc.
- CCS Inc.
- Smart Vision Lights, Inc.
- Edmund Optics Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Factory Automation and Industry 4.0 Adoption
- 4.2.2 AI-Enabled Defect Detection and Process Optimization
- 4.2.3 Rising Electronics, Semiconductor, and Battery Inspection Complexity
- 4.2.4 Vision-Guided Robotics and Autonomous Material Handling
- 4.2.5 Edge AI Inference in Space-Constrained Machines
- 4.2.6 Machine-Readable Product Identity Requirements
- 4.3 Market Restraints
- 4.3.1 High System Integration and Lifecycle Costs
- 4.3.2 Shortage of Machine Vision Integration Skills
- 4.3.3 Dataset Drift Across Product and Lighting Variants
- 4.3.4 Industrial Cybersecurity and Data-Ownership Concerns
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Modular Component
- 5.1.1 Camera and Imaging Modules
- 5.1.2 Optics and Lens Modules
- 5.1.3 Lighting Modules
- 5.1.4 Image Acquisition and Interface Modules
- 5.1.5 Processing and Computing Modules
- 5.1.6 Vision Software and AI Modules
- 5.1.7 I/O and Communication Modules
- 5.2 By Imaging Type
- 5.2.1 2D Vision Systems
- 5.2.2 3D Vision Systems
- 5.2.3 Hyperspectral and Multispectral Imaging Systems
- 5.3 By Application
- 5.3.1 Inspection and Defect Detection
- 5.3.2 Measurement and Metrology
- 5.3.3 Identification and Code Reading
- 5.3.4 Guidance and Positioning
- 5.3.5 Other Applications
- 5.4 By End-User Industry
- 5.4.1 Automotive
- 5.4.2 Electronics and Semiconductors
- 5.4.3 Food and Beverage
- 5.4.4 Healthcare and Pharmaceuticals
- 5.4.5 Logistics and Retail
- 5.4.6 Packaging
- 5.4.7 Other End-User Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Rest of the Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Cognex Corporation
- 6.4.2 KEYENCE CORPORATION
- 6.4.3 Basler AG
- 6.4.4 Teledyne Technologies Incorporated
- 6.4.5 OMRON Corporation
- 6.4.6 Allied Vision Technologies GmbH
- 6.4.7 IDS Imaging Development Systems GmbH
- 6.4.8 MVTec Software GmbH
- 6.4.9 LMI Technologies Inc.
- 6.4.10 Matrox Imaging Inc.
- 6.4.11 Euresys S.A.
- 6.4.12 Chromasens GmbH
- 6.4.13 JAI A/S
- 6.4.14 Vieworks Co., Ltd.
- 6.4.15 Tordivel AS
- 6.4.16 Opto Engineering S.p.A.
- 6.4.17 A&B Software LLC
- 6.4.18 Advanced Illumination, Inc.
- 6.4.19 CCS Inc.
- 6.4.20 Smart Vision Lights, Inc.
- 6.4.21 Edmund Optics Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

