PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155013

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155013
High Acuity Information Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the high acuity information systems market size is projected to be USD 10.52 billion in 2025, USD 11.58 billion in 2026, and reach USD 18.76 billion by 2031, growing at a CAGR of 10.12% from 2026 to 2031.
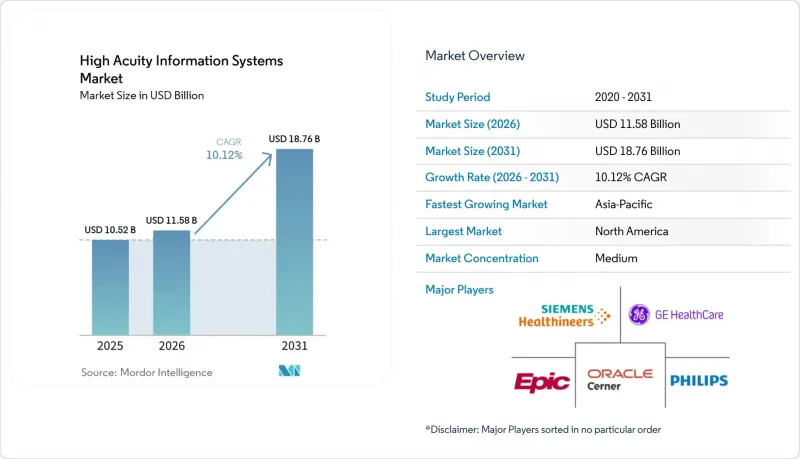
Global High Acuity Information Systems Market Trends and Insights
Rising Critical-Care Admissions Are Redefining Platform Requirements
Critical-care demand is changing the requirements placed on the high acuity information systems market. The Society of Critical Care Medicine reports 5 million ICU admissions each year in the United States. ICU patient-days to rise 14% by 2035, compared with 5% growth in overall inpatient volume. Higher acuity requires systems that can bring together continuous waveforms, laboratory results, medication data, and bedside-device information for many patients at once. This raises the value of information systems on a per-bed basis, even where providers cannot expand physical ICU capacity. China's T/CHIA 47-2024 smart ICU standard supports this direction by calling for multimodal data integration and real-time clinical decision support in public-hospital procurement.
Tele-ICU Deployment Creates An Information Systems Pull Cycle
Tele-ICU programs require a data and alerting layer that remote clinicians can use across facilities. That requirement links virtual-care growth directly to demand in the high acuity information systems market. West Tennessee Healthcare expanded its eICU program to 127 ICU beds and 17 mobile emergency department carts with Philips eCareManager and hellocare.ai in June 2026. Remote teams need access to vital signs, waveforms, laboratory data, and medication records without separate local workflows. A centralized command center also encourages health systems to standardize on one platform across affiliated sites. This can reduce vendor fragmentation within a system and make enterprise contracts more important for suppliers.
Integration Complexity Suppresses Deployment Velocity
Legacy hospital architecture can slow deployment in the high acuity information systems market. Large health systems often rely on customized interfaces across laboratory, pharmacy, radiology, billing, bed management, and medical-device systems. Each connection may need rebuilding and validation during a platform migration. A 2026 hospital migration study reported a 3-month assessment of more than 20 TB of legacy Oracle data before planning began. These requirements can extend implementation schedules to 1-3 years for enterprise platforms. The burden is especially difficult for community hospitals without dedicated clinical informatics teams.
Other drivers and restraints analyzed in the detailed report include:
- Predictive Sepsis And Deterioration Algorithms Are Setting A New Procurement Baseline
- Intensivist Shortages Are Accelerating Platform Adoption
- Alert Fatigue Is Eroding The Business Case For AI-Driven Monitoring
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Intensive Care Unit Information Systems captured 42.31% of revenue in 2025. The segment serves the hospital environment with the greatest density of waveform feeds, multi-device telemetry, and medication records. This clinical workload supports the use of systems designed for continuous data collection and coordinated decisions. A large installed base also creates longitudinal information that can support future algorithm development. That accumulated data can increase switching costs for established providers. Anesthesia Information Management Systems and Perinatal Information Systems remain mature categories with stable use in developed healthcare systems. Surgical Information Systems benefit from the movement toward minimally invasive and robot-assisted procedures. Mindray's Ruizhi Critical Care Decision Support System, deployed in Chinese tertiary hospitals in 2026, shows the shift from documentation tools toward AI-supported clinical recommendations.
Emergency Department Information Systems are forecast to grow at a CAGR of 13.25% through 2031. This high acuity information systems market size opportunity reflects emergency department crowding and the need for faster triage and patient-flow decisions. Sepsis identification requirements under the CMS SEP-1 bundle also support demand for timely decision support. Payer pressure to avoid unnecessary admissions gives hospitals another reason to improve early clinical assessment. 76% of ambulatory surgical centers had adopted an EHR in 2025. This increases the digital readiness of settings that need effective triage and discharge processes. Other product types that bridge multiple care environments are attracting investment from vendors seeking to replace fragmented point solutions. Health systems are also moving toward fewer and deeper vendor relationships across acute-care workflows.
Software and Services held 60.24% of revenue in 2025, making it the leading component of the high acuity information systems market. The share reflects the move from hardware-led purchasing toward subscriptions and platform-based contracts. Software delivery can allow vendors to provide new clinical modules, regulatory patches, and algorithm updates without on-site intervention. Cloud-native formats also support access across multi-site care networks. Philips was selected by University Health in San Antonio for its Enterprise Monitoring as a Service model in June 2026. The contract combined monitoring hardware, decision support, alarm management, and lifecycle services under a multi-year subscription. Such contracts simplify vendor management for hospitals and make recurring service revenue more important for suppliers.
Hardware has a smaller relative role, but it remains necessary for bedside care and clinical connectivity. Edge AI processing can support alerts that cannot wait for a cloud query. GE HealthCare and NXP presented work on on-device AI for anesthesia and neonatal care in January 2026. This approach can reduce dependence on centralized computing for latency-sensitive tasks. It also supports a new cycle of investment in intelligent bedside nodes. The hardware cycle, therefore, operates alongside software subscriptions rather than replacing them. Vendors in the high acuity information systems industry need both reliable device connectivity and scalable software delivery. Their product design must also allow hospitals to update clinical tools without disrupting established care processes.
Complete Report Scope:
- By Product Type
- Intensive Care Unit Information Systems
- Anesthesia Information Management Systems
- Emergency Department Information Systems
- Perinatal Information Systems
- Surgical Information Systems
- Other Product Types
- By Component
- Software and Services
- Hardware
- By Deployment
- On-Premise
- Cloud-Based
- Edge and Local Deployment
- By End User
- Hospitals
- Academic Medical Centers
- Ambulatory Surgical Centers
- Nursing Care Facilities
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 45.61% of revenue in 2025 and remains the largest revenue region. The United States drives regional demand through health-system consolidation and enterprise procurement. Large systems that acquire community hospitals often replace local clinical systems with a unified platform. This creates demand for interoperable information tools across many sites. The CMS Interoperability Framework enrolled its first general-availability cohort of Qualified Health Information Networks in July 2026. This milestone supports FHIR-based exchange between critical-care platforms and payers. Canada and Mexico provide additional growth through clinical information modernization. Hamilton Health Sciences integrated Philips Capsule Medical Device Integration with its Epic EMR for critical-care devices in August 2025.
Europe accounted for a significant share in 2025, with Germany holding the strongest country-level position. Hospital digitalization funding supports modernization across critical-care workflows. In France, BOW Medical reported that its Diane platform covered more than 450 healthcare institutions in 2025. The platform managed 5 million anesthesia consultations each year and supported more than 1,200 ICU beds. The United Kingdom's June 2025 post-market surveillance reforms increased scrutiny of connected clinical systems after launch. This raises compliance expectations for suppliers seeking to operate in the region. France's Alliance SIH is developing an open and data-centered hospital architecture to address fragmented software environments. These initiatives can strengthen interoperability requirements across clinical departments.
Asia-Pacific is forecast to grow at a CAGR of 12.25% through 2031, the fastest rate among geographic regions. China leads regional adoption through policy support, domestic technology suppliers, and hospital construction. Mindray's Ruizhi system uses multimodal bedside data to support clinical recommendations in tertiary hospitals. Tianjin Haihe Hospital, Wining Health, and the National Supercomputing Center Tianjin launched a Ruizhi critical-care model and ICU AI innovation base in August 2026. Japan, South Korea, and Australia add demand through national and regional hospital modernization programs. India's tertiary hospitals and private healthcare chains are also investing in purpose-built clinical information systems. Qatar launched a digital health interoperability plan in March 2026 for patient-data exchange across public and private care settings. Brazil and Colombia are developing interoperable care infrastructure, although South America remains fragmented.
- Altera Digital Health
- Baxter
- CLEW Medical Ltd.
- Dragerwerk AG and Co. KGaA
- Epic Systems
- Etiometry Inc.
- GE HealthCare Technologies Inc.
- Getinge
- Intersystems
- Koninklijke Philips
- Masimo
- Medhost
- Meditech
- Merative
- Nihon Kohden
- Oracle
- Picis Clinical Solutions, Inc.
- Siemens Healthineers
- Surgical Information Systems, LLC
- Wolters Kluwer
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Critical-Care Admissions and Patient Acuity
- 4.2.2 Expansion of Tele-ICU and Virtual-Care Models
- 4.2.3 Demand for Predictive Deterioration and Sepsis Detection
- 4.2.4 Intensivist and Critical-Care Workforce Shortages
- 4.2.5 Hospital Investment in Interoperable Digital Infrastructure
- 4.2.6 Device-Derived Data Monetization and Longitudinal Waveform Archives
- 4.3 Market Restraints
- 4.3.1 Integration Complexity Across Legacy Hospital Systems
- 4.3.2 Alert Fatigue and Declining Clinician Trust
- 4.3.3 Cybersecurity, Privacy and Algorithmic-Liability Exposure
- 4.3.4 Uneven Budgets and Limited Local Implementation Capacity
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Intensive Care Unit Information Systems
- 5.1.2 Anesthesia Information Management Systems
- 5.1.3 Emergency Department Information Systems
- 5.1.4 Perinatal Information Systems
- 5.1.5 Surgical Information Systems
- 5.1.6 Other Product Types
- 5.2 By Component
- 5.2.1 Software and Services
- 5.2.2 Hardware
- 5.3 By Deployment
- 5.3.1 On-Premise
- 5.3.2 Cloud-Based
- 5.3.3 Edge and Local Deployment
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Academic Medical Centers
- 5.4.3 Ambulatory Surgical Centers
- 5.4.4 Nursing Care Facilities
- 5.4.5 Other End Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Altera Digital Health
- 6.3.2 Baxter International Inc.
- 6.3.3 CLEW Medical Ltd.
- 6.3.4 Dragerwerk AG and Co. KGaA
- 6.3.5 Epic Systems Corporation
- 6.3.6 Etiometry Inc.
- 6.3.7 GE HealthCare Technologies Inc.
- 6.3.8 Getinge AB
- 6.3.9 InterSystems Corporation
- 6.3.10 Koninklijke Philips N.V.
- 6.3.11 Masimo Corporation
- 6.3.12 MEDHOST
- 6.3.13 MEDITECH
- 6.3.14 Merative
- 6.3.15 Nihon Kohden Corporation
- 6.3.16 Oracle Corporation
- 6.3.17 Picis Clinical Solutions, Inc.
- 6.3.18 Siemens Healthineers AG
- 6.3.19 Surgical Information Systems, LLC
- 6.3.20 Wolters Kluwer N.V.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

