PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155229

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155229
Asphalt Additives - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
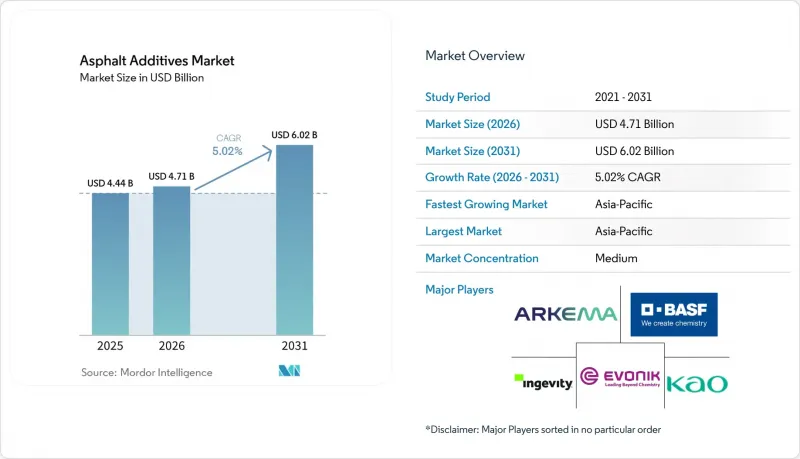
According to Mordor Intelligence, the asphalt additives market size was valued at USD 4.44 billion in 2025 and is estimated to grow from USD 4.71 billion in 2026 to reach USD 6.02 billion by 2031, at a CAGR of 5.02% during the forecast period (2026-2031).
Global Asphalt Additives Market Trends and Insights
Infrastructure Modernization and Pavement Rehabilitation
Road capital expenditure is a direct demand signal for the asphalt additives market, as each paving project requires binder systems suited to local traffic and climate conditions. India allocated USD 34.4 billion to the Ministry of Road Transport and Highways for 2026-27, a 7.9% increase over the preceding fiscal year, supporting road programs in areas with challenging high-altitude, freeze-thaw, and wet subgrade conditions. China approved major infrastructure projects worth CNY 295 billion (USD 42.2 billion) for 2026, sustaining pavement work in provinces where harsh conditions require higher polymer dosages. Maintenance budgets are becoming increasingly important in road authority spending, as aging networks require cold-mix emulsifiers, rapid-setting agents, and rejuvenators. These purchases follow shorter procurement cycles than large new-build contracts and can help sustain demand when construction schedules change. The asphalt additives market benefits when authorities treat pavement upkeep as an asset-management need rather than a deferred expense.
Performance-Based Binder Specifications and Heavy Axle Loads
Performance-graded binder specifications increase polymer additive requirements on freight corridors and heavily used highways. A Performance Grade (PG) 76-22 or PG 82-22 binder typically uses a Styrene-Butadiene-Styrene (SBS) content of 5-7% of the binder mass and requires compatible processing stabilizers and dispersants. A 2025 study reported that SBS-modified binders improved tensile strength ratio and resilient modulus by 30-35%, while rut depth declined by 42% in controlled wheel-tracking tests. These results support specifications that prioritize service life and maintenance outcomes. The asphalt additives market benefits when highway agencies adopt higher-performance grades, as unmodified binder systems no longer meet the required pavement design standards. Adoption in Pakistan, Southeast Asia, and other ASEAN road systems can raise additive intensity rather than merely add asphalt output.
Volatile Polymer, Bitumen, and Bio-Feedstock Costs
Styrene-Butadiene-Styrene (SBS) polymer, base bitumen, and aromatic extender oils account for a large share of the cost of polymeric modifiers and rejuvenating agents. SBS pricing moves with butadiene feedstock and naphtha cracking margins, making it sensitive to petrochemical capacity utilization. High butadiene costs can reduce supplier margins and delay specification upgrades where public contract prices are set annually. Bio-based inputs face separate supply risks because tall oil depends on kraft pulp output, vegetable oil responds to weather and biofuel policy, and lignin availability follows paper production. These dynamics can constrain supply as environmental procurement increases demand for bio-based rejuvenators. The asphalt additives market may see greater consolidation if smaller specialty formulators cannot manage feedstock volatility as effectively as integrated chemical suppliers.
Other drivers and restraints analyzed in the detailed report include:
- Reclaimed Asphalt Pavement Adoption and Binder Rejuvenation
- Warm-Mix Asphalt, Lower-Carbon Construction, and Circular Formulations
- High Initial Cost, Limited Contractor Capability, and Municipal Testing Gaps
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polymeric modifiers accounted for 41.56% of the asphalt additives market share in 2025, supported by the broad use of Styrene-Butadiene-Styrene (SBS) block copolymers and Styrene-Butadiene Rubber (SBR) in performance-graded binders. SBS content commonly ranges from 4% to 7% of binder mass in demanding applications. Highway systems in Asia, North America, and the Middle East use these modifiers where traffic, temperature, and design-life requirements exceed the capability of unmodified binders. Once an agency adopts a performance grade, removing the modifier can compromise the pavement design basis. Anti-strip and adhesion promoters serve a related role in tropical and high-rainfall locations where aggregate-binder separation is a common failure mode. Emulsifiers support cold-mix and maintenance work, where ambient-temperature repair methods eliminate the need for heated mixing plants. The asphalt additives market continues to rely on these established product families because they meet routine highway and maintenance specifications.
Rejuvenators and recycling agents are projected to grow at a 5.45% CAGR through 2031, the highest rate within the product segment. Their use increases with reclaimed asphalt pavement (RAP) content because the aged binder requires restoration before it can perform comparably to virgin material. A 2024 review found that optimized rejuvenator dosing in mixtures containing 45% RAP restored low-temperature cracking resistance and mid-temperature fatigue life to levels comparable with virgin binder. European recycled-content requirements and China's expanding maintenance work both support demand for these products. Chemical modifiers, including Fischer-Tropsch waxes, reactive modifiers, and specialty stabilizers, address specific performance needs. Other products include additives for low-noise porous pavements, anti-icing surface treatments, and airport surfaces exposed to contamination. These applications represent smaller quantities but carry higher value due to their specific performance requirements.
Complete Report Scope:
- By Product Type
- Polymeric Modifiers
- Anti-Strip and Adhesion Promoters
- Emulsifiers
- Chemical Modifiers
- Rejuvenators and Recycling Agents
- Others
- By Technology
- Hot-Mix Asphalt
- Warm-Mix Asphalt
- Cold-Mix Asphalt
- Others
- By Application
- Road Construction and Paving
- Airport Runways and Airfield Pavements
- Parking Lots
- Roofing
- Industrial
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 38.78% of the asphalt additives market share in 2025 and is projected to grow at a 5.94% CAGR through 2031. China is shifting from construction-led demand toward maintenance-led demand as its expressway network exceeds 160,000 km, bringing more pavement sections into their first major rehabilitation cycle. This transition is increasing the use of rejuvenators, emulsifiers, and rapid-repair additives, as maintenance programs must restore performance in existing pavements rather than specify materials only for new roadbeds. India remains more focused on new road construction, with its National Infrastructure Pipeline covering 3,906 road and bridge projects and Fiscal Year 2026 (FY26) infrastructure capital expenditure estimated at USD 121.3 billion. These contrasting demand profiles require suppliers to offer both high-dosage polymer modifier packages for new corridors and practical repair systems for established networks. Japan and South Korea support demand through preventive maintenance programs, in which road agencies seek durable treatments to avoid the need for more extensive rehabilitation later. Harima Chemical Group's 2025 biomass-derived recycling additive project with the Public Works Research Institute (PWRI) and Nihon University reflects Japan's focus on lower-carbon pavement renewal chemistry and repeated binder restoration. Vietnam, Thailand, and Indonesia also require moisture-resistant modifiers and anti-strip agents for paving in humid conditions, making aggregate-binder adhesion a regional product requirement.
North America and Europe are high-value demand areas due to performance-grade specifications and procurement criteria tied to lower emissions. The United States supports warm-mix adoption through Federal Highway Administration technical guidance, which has influenced state transportation specifications and encourages consistent evaluation of lower-temperature paving methods. Canada requires low-temperature cracking resistance, anti-icing performance, and freeze-thaw durability, supporting specialized regional additive packages suited to long seasonal temperature changes. Europe is shifting toward country-specific warm-mix requirements, which is significant for suppliers with approved formulations, verified performance, and the ability to meet public procurement conditions. Germany's transition to reduced-temperature production by December 2026 and Italy's warm-mix rule near residential areas are making compliance a contractual requirement. France, Norway, and the United Kingdom have also expanded warm-mix use through combinations of procurement incentives, health requirements, and voluntary commitments. In these regions, the asphalt additives market rewards product validation as much as basic material availability, as approval and test evidence can determine whether a supplier is eligible for a project.
South America, the Middle East, and Africa contribute meaningful demand but have distinct demand patterns. Brazil's road network spans 2 million km, and concession-funded rehabilitation and urban expressway upgrades support regional demand for products that extend pavement life on heavily used routes. Bitumen price volatility and constrained municipal budgets limit the use of higher-specification additives on secondary routes, creating a clear difference between major corridors and local paving work. Argentina's fiscal constraints reduce specification intensity outside major agricultural export corridors, where heavy axle loads provide a stronger cost case for polymeric modification. Saudi Arabia's Vision 2030 programs and logistics corridors support the use of high-temperature, rutting-resistant, polymer-modified binders, particularly where severe heat places additional stress on road surfaces. Sasobit-type warm-mix additives can also improve workability during hot summer paving periods, when traditional production conditions become more difficult to manage. South Africa serves as a regional center for specialty additive formulation and distribution, while Egypt, Ethiopia, and Gulf countries represent longer-term opportunities as primary road corridors adopt performance specifications and maintenance standards.
- Arkema
- BASF
- Cargill
- Dow
- Dynasol Group
- Evonik Industries AG
- Honeywell International Inc.
- Ingevity Corporation
- Iterchimica S.p.A.
- Kao Corporation
- LCY Chemical Corp.
- LUCOBIT Aktiengesellschaft
- McAsphalt Industries Limited
- Nouryon
- Sripath Technologies, LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Infrastructure Modernization and Pavement Rehabilitation
- 4.2.2 Performance-Based Binder Specifications and Heavy Axle Loads
- 4.2.3 Reclaimed Asphalt Pavement Adoption and Binder Rejuvenation
- 4.2.4 Warm-Mix Asphalt and Lower-Carbon Construction Requirements
- 4.2.5 Specification-Ready Circular Formulations Using Recycled Plastics, Tires, and Bio-Based Feedstocks
- 4.3 Market Restraints
- 4.3.1 Volatile Polymer, Bitumen, and Bio-Feedstock Costs
- 4.3.2 High Initial Cost and Limited Contractor Technical Capability
- 4.3.3 Municipal Specification Inertia and Inconsistent Testing Infrastructure
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Polymeric Modifiers
- 5.1.2 Anti-Strip and Adhesion Promoters
- 5.1.3 Emulsifiers
- 5.1.4 Chemical Modifiers
- 5.1.5 Rejuvenators and Recycling Agents
- 5.1.6 Others
- 5.2 By Technology
- 5.2.1 Hot-Mix Asphalt
- 5.2.2 Warm-Mix Asphalt
- 5.2.3 Cold-Mix Asphalt
- 5.2.4 Others
- 5.3 By Application
- 5.3.1 Road Construction and Paving
- 5.3.2 Airport Runways and Airfield Pavements
- 5.3.3 Parking Lots
- 5.3.4 Roofing
- 5.3.5 Industrial
- 5.3.6 Others
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Arkema
- 6.4.2 BASF
- 6.4.3 Cargill
- 6.4.4 Dow
- 6.4.5 Dynasol Group
- 6.4.6 Evonik Industries AG
- 6.4.7 Honeywell International Inc.
- 6.4.8 Ingevity Corporation
- 6.4.9 Iterchimica S.p.A.
- 6.4.10 Kao Corporation
- 6.4.11 LCY Chemical Corp.
- 6.4.12 LUCOBIT Aktiengesellschaft
- 6.4.13 McAsphalt Industries Limited
- 6.4.14 Nouryon
- 6.4.15 Sripath Technologies, LLC
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

