PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155260

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155260
Germany Electric Vehicle CNC Turning - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
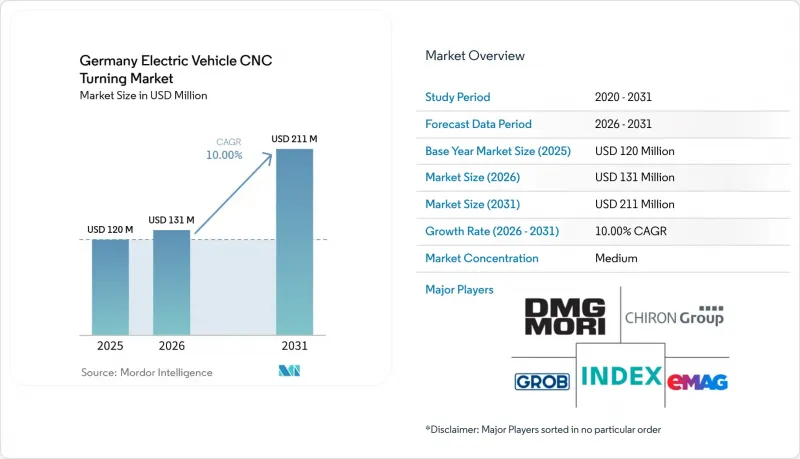
According to Mordor Intelligence, the Germany electric vehicle CNC turning market size is projected to expand from USD 120 million in 2025 and USD 131 million in 2026 to USD 211 million by 2031, registering a CAGR of 10% between 2026 and 2031.
Germany Electric Vehicle CNC Turning Market Trends and Insights
Premium EV Manufacturing Accelerates Demand for Ultra-Precision Turning Centers
Germany's premium vehicle manufacturing base supports demand for turning centers capable of meeting strict geometry and surface-finish requirements. Mercedes-Benz began series production of its axial-flux electric motor at Berlin-Marienfelde in June 2026, using 98 precision manufacturing steps, including 35 processes newly developed worldwide. The assembly process maintains stator positioning within 0.1 mm through real-time quality controls, which raises the need for accurate machining of related components. The German electric-vehicle CNC turning market benefits from suppliers' need for direct-drive spindles and thermal control to manufacture motor shafts, housings, and other precision parts. BMW Plant Munich entered pre-series production for the Neue Klasse in 2026 and plans full series production in the second half of 2026, creating a new procurement cycle for drivetrain equipment and production systems. BMW expects the redesigned production approach to reduce manufacturing costs per vehicle by 10%, which increases the value of machines that combine multiple processes in fewer setups.
Automotive Electrification Strengthens Investment in High-Performance Machining
Automotive electrification is changing the component mix processed by German machining facilities. Germany produced 1.22 million battery electric vehicles in 2025, while electrified vehicle production is expected to reach 1.76 million units in 2026. E-axle housings require controlled machining of thin-wall aluminum structures, and rotor shafts require several hard-turning steps. The Germany electric vehicle CNC turning market therefore serves requirements that cannot be met through simple reuse of many internal-combustion machining lines. ZF started series production of electric axle-drive variants at its expanded Saarbrucken facility in 2025, thereby increasing demand for e-axle housings and reduction gear shafts. EU fleet-emissions rules continue to direct OEM product plans toward lower-emission vehicles, supporting continued investment in electric drivetrain capacity.
High Energy and Operating Costs Increase Manufacturing Expenses
Energy costs limit smaller manufacturers' willingness to add CNC capacity. A June 2026 DIHK survey found that rising electricity and gas prices were a direct competitiveness concern for nearly 40% of German industrial enterprises. The same survey found that 1 in 3 industrial enterprises had deferred investment in core production processes. High-speed CNC turning centers can require substantial power during operation, making energy efficiency a material part of the investment case. The Germany electric vehicle CNC turning market faces a divided buyer base because large OEMs can continue strategic electrification programs while smaller contract manufacturers review capital plans more carefully. Energy audits and efficiency requirements also add planning and compliance work for larger industrial users under the EU Energy Efficiency Directive.
Other drivers and restraints analyzed in the detailed report include:
- Industry 4.0 and Smart Factory Adoption Enhance CNC Automation
- Growing Production of Electric Drivetrain Components Expands Turning Operations
- Shortage of Skilled CNC Operators and Automation Engineers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Horizontal CNC turning centers held 38.3% of the Germany electric vehicle CNC turning market share in 2025. Their position reflects their suitability for high-volume production of motor shafts, bearing races, and rotor rings. German Tier-1 suppliers often operate these machines in automated, multi-shift configurations. Vertical CNC turning centers are well-suited to large-bore housings and disk-shaped parts, including thin-walled aluminum e-axle housings, where stable workpiece positioning can influence the final geometry.
Swiss-type CNC turning centers serve small-diameter parts, including connectors, fasteners, and pin-type components used in battery-management and power-electronics assemblies. These parts can require tolerances below 0.005 mm, increasing the importance of controlled machining conditions. The Germany electric vehicle CNC turning market size for multi-tasking turn-mill centers is projected to grow at a 12% CAGR between 2026 and 2031. A single setup can complete turning, milling, drilling, and thread grinding for integrated e-axle housings, reducing alignment errors between operations. INDEX-Werke introduced the G160 5-axis turn-mill center in March 2026 as a compact G-series model for mid-volume producers. DMG MORI introduced the NTX 3rd Generation in September 2025 and identified electric vehicle manufacturing as a target application.
Complete Report Scope:
- By Machine Type
- Horizontal CNC Turning Centers
- Vertical CNC Turning Centers
- Multi-Tasking Turn-Mill Centers
- Swiss-Type CNC Turning Centers
- Others
- By Component Application
- Electric Motor Components
- E-Axles & Transmission Components
- Battery System Components
- Others
- By End User
- EV OEM Manufacturing Plants
- Tier-1 Automotive Suppliers
- Tier-2 Component Manufacturers
- Precision Contract Manufacturers
List of Companies Covered in this Report:
- INDEX-Werke GmbH & Co. KG Hahn & Tessky
- EMAG GmbH & Co. KG
- DMG MORI AG
- CHIRON Group SE
- GROB-WERKE GmbH & Co. KG
- HELLER Maschinenfabrik GmbH
- SW Maschinen GmbH
- Spinner Werkzeugmaschinenfabrik GmbH
- TRAUB Werkzeugmaschinen GmbH
- NILES-SIMMONS Industrieanlagen GmbH
- MAG IAS GmbH
- Starrag GmbH
- Mazak Europe N.V.
- Okuma Europe GmbH
- Haas Automation Europe
- DN Solutions Europe GmbH
- Tsugami Europe GmbH
- Citizen Machinery Europe GmbH
- Star Micronics GmbH
- GF Machining Solutions GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
- 3.1 Market Snapshot (2025 vs. 2031)
- 3.2 Key Findings by Segment
- 3.3 Investment Hotspots & White Space
4 Market Landscape
- 4.1 Market Overview
- 4.1.1 Role of CNC Turning Centers in the EV Manufacturing Value Chain
- 4.1.2 Evolution from ICE Component Machining to EV-Specific Machining Requirements
- 4.2 Market Drivers
- 4.2.1 Premium EV Manufacturing Accelerates Demand for Ultra-Precision Turning Centers
- 4.2.2 Automotive Electrification Strengthens Investment in High-Performance Machining
- 4.2.3 Industry 4.0 and Smart Factory Adoption Enhance CNC Automation
- 4.2.4 Growing Production of Electric Drivetrain Components Expands Turning Operations
- 4.2.5 German Machine Tool Innovation Supports High-Speed Multi-Axis Manufacturing
- 4.2.6 Rising Export of Precision Automotive Components Drives Advanced CNC Deployment
- 4.3 Market Restraints
- 4.3.1 High Energy and Operating Costs Increase Manufacturing Expenses
- 4.3.2 Economic Uncertainty Delays Capital Investment in New Machine Tools
- 4.3.3 Shortage of Skilled CNC Operators and Automation Engineers
- 4.3.4 Lengthy Procurement Cycles for High-End Precision Equipment
- 4.4 Market Opportunities
- 4.4.1 Battery Cell and Power Electronics Manufacturing Creates New Machining Demand
- 4.4.2 AI-Based Process Optimization Improves CNC Productivity and Quality
- 4.4.3 Lightweight EV Component Manufacturing Expands High-Precision Turning Applications
- 4.4.4 Nearshoring of European Automotive Supply Chains Encourages CNC Capacity Expansion
- 4.5 EV Manufacturing Value Chain Analysis
- 4.5.1 Raw Material Suppliers
- 4.5.2 Machine Tool Manufacturers
- 4.5.3 EV Component Manufacturers
- 4.5.4 EV OEMs
- 4.6 Manufacturing Process Analysis
- 4.6.1 Machine Selection by Production Volume
- 4.6.2 Prototype vs. Mass Production Requirements
- 4.7 Trade Flow & Tariff Impact Analysis
- 4.7.1 Key Machine Tool Export & Import Corridors
- 4.7.2 Regional Sourcing Shifts & Localization Trends
- 4.8 Regulatory Landscape
- 4.8.1 Manufacturing Incentives for EV Production
- 4.8.2 Local Content Requirements
- 4.8.3 Smart Manufacturing Policies
- 4.8.4 Energy Efficiency Regulations for Machine Tools
- 4.9 Technology Landscape
- 4.9.1 Multi-Tasking Turn-Mill Centers
- 4.9.2 AI-Based Tool Wear Monitoring
- 4.9.3 Digital Twin Integration
- 4.9.4 Robot Automation
- 4.10 Impact of AI & Digital Manufacturing on CNC Turning
- 4.11 Geopolitical Impact on Market
5 Market Size & Growth Forecasts Value (USD)
- 5.1 By Machine Type
- 5.1.1 Horizontal CNC Turning Centers
- 5.1.2 Vertical CNC Turning Centers
- 5.1.3 Multi-Tasking Turn-Mill Centers
- 5.1.4 Swiss-Type CNC Turning Centers
- 5.1.5 Others
- 5.2 By Component Application
- 5.2.1 Electric Motor Components
- 5.2.2 E-Axles & Transmission Components
- 5.2.3 Battery System Components
- 5.2.4 Others
- 5.3 By End User
- 5.3.1 EV OEM Manufacturing Plants
- 5.3.2 Tier-1 Automotive Suppliers
- 5.3.3 Tier-2 Component Manufacturers
- 5.3.4 Precision Contract Manufacturers
6 Competitive Landscape
- 6.1 Market Structure
- 6.2 Strategic Developments (2022-2026)
- 6.2.1 New Product Launches
- 6.2.2 Automation Partnerships
- 6.2.3 EV Manufacturing Projects
- 6.2.4 Capacity Expansion
- 6.2.5 Acquisitions
- 6.2.6 Digital Manufacturing Collaborations
- 6.3 Market Share Analysis
- 6.4 Company Profiles
- 6.4.1 INDEX-Werke GmbH & Co. KG Hahn & Tessky
- 6.4.2 EMAG GmbH & Co. KG
- 6.4.3 DMG MORI AG
- 6.4.4 CHIRON Group SE
- 6.4.5 GROB-WERKE GmbH & Co. KG
- 6.4.6 HELLER Maschinenfabrik GmbH
- 6.4.7 SW Maschinen GmbH
- 6.4.8 Spinner Werkzeugmaschinenfabrik GmbH
- 6.4.9 TRAUB Werkzeugmaschinen GmbH
- 6.4.10 NILES-SIMMONS Industrieanlagen GmbH
- 6.4.11 MAG IAS GmbH
- 6.4.12 Starrag GmbH
- 6.4.13 Mazak Europe N.V.
- 6.4.14 Okuma Europe GmbH
- 6.4.15 Haas Automation Europe
- 6.4.16 DN Solutions Europe GmbH
- 6.4.17 Tsugami Europe GmbH
- 6.4.18 Citizen Machinery Europe GmbH
- 6.4.19 Star Micronics GmbH
- 6.4.20 GF Machining Solutions GmbH
7 Market Opportunities & Future Outlook
- 7.1 White-Space Assessment
- 7.1.1 Emerging EV Manufacturing Hubs
- 7.1.2 Tier-2 Suppliers
- 7.1.3 Precision Machining for Next-Generation E-Mobility
- 7.1.4 AI-Driven Autonomous Machining
- 7.2 Strategic Recommendations

