PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155331

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155331
Heart Closure Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
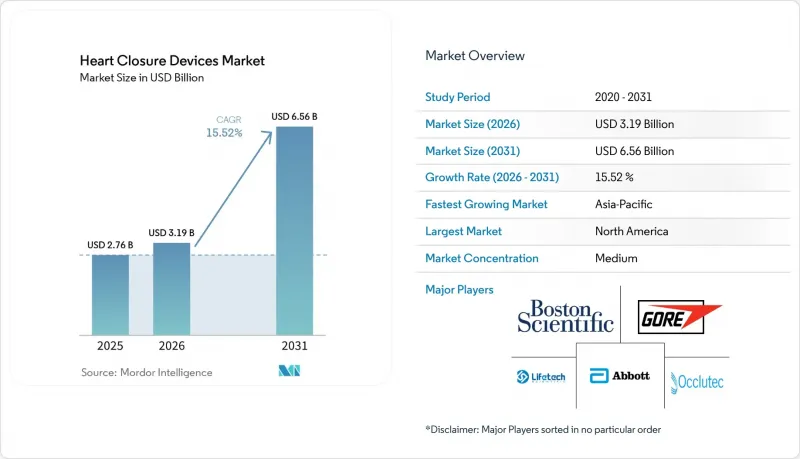
According to Mordor Intelligence, the heart closure devices market size is expected to grow from USD 2.76 billion in 2025 to USD 3.19 billion in 2026 and is forecast to reach USD 6.56 billion by 2031 at 15.52% CAGR over 2026-2031.
Global Heart Closure Devices Market Trends and Insights
Rising Structural Heart Disease and Atrial Fibrillation Burden
Atrial fibrillation remains the main clinical driver for left atrial appendage closure in the heart closure device market. The U.S. Centers for Disease Control and Prevention projects that 12.1 million people in the United States will have atrial fibrillation by 2050. Mortality associated with atrial fibrillation and ischemic heart disease rose at an annual percentage change of 1.6% from 2010 to 2023. Boston Scientific reported in March 2026 that 40% of patients prescribed blood thinners for stroke prevention do not take them consistently. On the congenital side, ventricular septal defects represent 30% to 40% of congenital heart disease cases, and atrial septal defects account for 7% to 10%. This combination gives the heart closure device market a demand base that is not tied to one clinical indication.
Shift Toward Minimally Invasive Transcatheter Treatment
Transcatheter procedures have become central to congenital heart defects, patent foramen ovale, and left atrial appendage closure. Multiple atrial septal defect devices have received U.S. Food and Drug Administration approval, and CPT code 93580 provides a standard reimbursement route for closure of congenital interatrial communications. Studies involving more than 5,000 patients reported closure success approaching 100% within 6 months for leading nitinol occluders. Japan had performed more than 10,000 left atrial appendage closure procedures by 2025 after introducing the procedure in 2019. The heart closure device market benefits when standardized procedures can be offered in a wider range of settings. This shift can reduce the hospital capacity limits that restrict procedure volumes.
High Upfront Device and Procedure Cost
The cost of a closure procedure can limit adoption outside North America and Western Europe. Device cost, catheterization laboratory time, imaging, specialist services, and inpatient care can take the cost of a left atrial appendage closure procedure above USD 25,000 in high-income settings. This level can strain reimbursement systems in middle-income countries where payment may be much lower. China's volume-based procurement program places pricing pressure on structural heart devices even as procedure volumes increase. Boston Scientific stated in its first-quarter 2026 update that standalone Watchman volumes softened because of hospital capacity constraints, procedure prioritization, and reimbursement dynamics. These factors can slow heart closure device market adoption in lower-income systems without preventing long-term demand.
Other drivers and restraints analyzed in the detailed report include:
- Stronger Clinical Evidence and Reimbursement Expansion
- Aging and Pediatric Congenital Heart Disease Populations
- Device-Related Thrombus, Embolization, Effusion, and Atrial Fibrillation Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Congenital heart defect closure accounted for 46.65% of the closure device category in 2025. Its position reflects the frequency of ventricular and atrial septal defects and the maturity of transcatheter repair pathways. Ventricular septal defects and atrial septal defects together account for 37% to 50% of congenital heart disease cases. The Amplatzer Septal Occluder and GORE CARDIOFORM devices are established options in this field. Occlutech's ASD Occluder also received FDA approval for the U.S. market. Published data from more than 5,000 patients support high closure success rates for leading devices.
Left atrial appendage closure is projected to expand at a 17.43% CAGR through 2031. This rate makes it the fastest-growing closure type in the heart closure device market. CHAMPION-AF supports a potential move from use in selected anticoagulation patients to a larger stroke prevention population. Abbott received CE Mark for Amulet 360 in August 2026 after the VERITAS study reported 99.8% implant success and 93.9% complete closure at 45 days. Patent foramen ovale closure remains a meaningful secondary category, supported by its established role in cryptogenic stroke prevention. The PerFOrm and PROTEA-PFO studies are assessing additional PFO device applications and device designs.
Nitinol-based devices held 51.87% share in 2025. Their position comes from shape-memory and superelastic properties that support self-expanding occluder designs. These devices can be compressed in a catheter and expand to match defect geometry at implantation. Nitinol occluders accounted for 79.8% of the worldwide atrial septal occluder category in 2025. Stainless steel devices remain in a narrower role as newer platforms offer stronger biocompatibility and MRI compatibility. Polymer composite and bioresorbable products have smaller current positions in the heart closure device industry.
Bioresorbable devices are a developing material option for patients who may benefit from avoiding a permanent metal implant. Lepu Medical's MemoSorb uses a PDO stent and PLA membrane that fully degrade within 12 to 24 months. A 2025 study reported 90.63% closure success for MemoSorb at 6 months, compared with 91.30% for metal occluders, and 99.8% material degradation at 2 years. The BioMetal trial is comparing a biodegradable occluder with a nitinol alloy device in 400 PFO patients with medication-refractory migraine. Nitinol supply concentration remains a risk because lead times had risen from 10 to 12 weeks to nearly 1 year. Confluent Medical Technologies committed more than USD 50 million to expand capacity 3 times by 2027 through an ATI partnership.
Complete Report Scope:
- By Closure Type
- Congenital Heart Defect Closure
- Patent Foramen Ovale Closure
- Left Atrial Appendage Closure
- By Material
- Nitinol-Based Devices
- Stainless Steel Devices
- Polymer Composite Devices
- Bioresorbable and Fully Degradable Materials
- By Mode of Delivery
- Transcatheter Delivery
- Minimally Invasive Surgical Delivery
- Open Surgical Delivery
- By End User
- Tertiary Care Hospitals
- Cardiac Catheterization Laboratories
- Ambulatory Surgical Centers
- Specialty Heart Clinics
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 44.28% of the heart closure device market share in 2025. The region benefits from established reimbursement, device approval systems, and a high density of structural heart centers. The United States accounts for most regional revenue through Watchman and Amplatzer procedures. CHAMPION-AF data reported in March 2026 can support future label expansion efforts in the region. CMS payment changes are also favorable for procedure economics.
Asia-Pacific is expected to grow at a 16.54% CAGR through 2031, the fastest regional rate in the heart closure device market. China has a large congenital heart disease patient population and a domestic manufacturing base for closure devices. Its volume-based procurement approach can lower average selling prices while volumes rise. India's National Health Mission identified more than 1.2 million new cardiovascular cases in FY2023-24 through district-level screening. Production-linked incentives also support domestic medical device manufacturing. Japan has performed more than 10,000 left atrial appendage closure procedures since 2019.
Europe holds the second-largest regional position, led by Germany, the United Kingdom, France, and Italy. The 2025 ESC and EACTS guidelines added 28 recommendations and emphasized specialized Heart Valve Centers with high procedural volumes. This infrastructure can support the heart closure device market through shared imaging and multidisciplinary capabilities. The CLOSURE-AF trial included 912 high-risk atrial fibrillation patients and found non-inferiority for left atrial appendage closure across composite outcomes. The Middle East, Africa, and South America have lower adoption because of budget limits, reimbursement gaps, and training needs. Investment in catheterization laboratories in Gulf Cooperation Council nations and Brazil can support later volume growth.
- Abbott Laboratories
- Baylis Medical Company Inc.
- BIOTRONIK SE and Co. KG
- Biosense Webster, Inc.
- Boston Scientific
- Cardia, Inc.
- Edward Lifesciences
- Lepu Medical Technology (Beijing) Co., Ltd.
- Lifetech Scientific
- Medtronic
- Meril Life Sciences India Private Limited
- MicroPort
- Occlutech Holding AG
- PFM Medical AG
- Sahajanand Medical Technologies
- Starway Medical Technology, Inc.
- Terumo
- W. L. Gore & Associates
- AtriCure
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope Of The Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Structural Heart Disease and Atrial Fibrillation Burden
- 4.2.2 Shift Toward Minimally Invasive Transcatheter Treatment
- 4.2.3 Stronger Clinical Evidence and Reimbursement Expansion
- 4.2.4 Aging and Pediatric Congenital Heart Disease Populations
- 4.2.5 Procedure Planning With Intracardiac Echocardiography and Computational Imaging
- 4.2.6 Biodegradable Occluders for Pediatric and Repeat-Intervention Use
- 4.3 Market Restraints
- 4.3.1 High Upfront Device and Procedure Cost
- 4.3.2 Device-Related Thrombus, Embolization, Effusion, and Atrial Fibrillation Risk
- 4.3.3 Operator Learning Curve and Imaging-Dependent Workflow
- 4.3.4 Nitinol and Specialized Component Supply Volatility
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat Of New Entrants
- 4.7.2 Bargaining Power Of Buyers
- 4.7.3 Bargaining Power Of Suppliers
- 4.7.4 Threat Of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Closure Type
- 5.1.1 Congenital Heart Defect Closure
- 5.1.2 Patent Foramen Ovale Closure
- 5.1.3 Left Atrial Appendage Closure
- 5.2 By Material
- 5.2.1 Nitinol-Based Devices
- 5.2.2 Stainless Steel Devices
- 5.2.3 Polymer Composite Devices
- 5.2.4 Bioresorbable and Fully Degradable Materials
- 5.3 By Mode of Delivery
- 5.3.1 Transcatheter Delivery
- 5.3.2 Minimally Invasive Surgical Delivery
- 5.3.3 Open Surgical Delivery
- 5.4 By End User
- 5.4.1 Tertiary Care Hospitals
- 5.4.2 Cardiac Catheterization Laboratories
- 5.4.3 Ambulatory Surgical Centers
- 5.4.4 Specialty Heart Clinics
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(Includes Global Level Overview, Market Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share For Key Companies, Products & Services, And Recent Developments)}
- 6.3.1 Abbott
- 6.3.2 Baylis Medical Company Inc.
- 6.3.3 BIOTRONIK SE and Co. KG
- 6.3.4 Biosense Webster, Inc.
- 6.3.5 Boston Scientific Corporation
- 6.3.6 Cardia, Inc.
- 6.3.7 Edwards Lifesciences Corporation
- 6.3.8 Lepu Medical Technology (Beijing) Co., Ltd.
- 6.3.9 Lifetech Scientific Corporation
- 6.3.10 Medtronic plc
- 6.3.11 Meril Life Sciences India Private Limited
- 6.3.12 MicroPort Scientific Corporation
- 6.3.13 Occlutech Holding AG
- 6.3.14 PFM Medical AG
- 6.3.15 Sahajanand Medical Technologies Limited
- 6.3.16 Starway Medical Technology, Inc.
- 6.3.17 Terumo Corporation
- 6.3.18 W. L. Gore & Associates, Inc.
- 6.3.19 Atricure, Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

