PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155562

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155562
Liquid Bandages - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the liquid bandages market size was valued at USD 1.61 billion in 2025 and is estimated to grow from USD 1.71 billion in 2026 to reach USD 2.32 billion by 2031, at a CAGR of 6.25% during the forecast period (2026-2031).
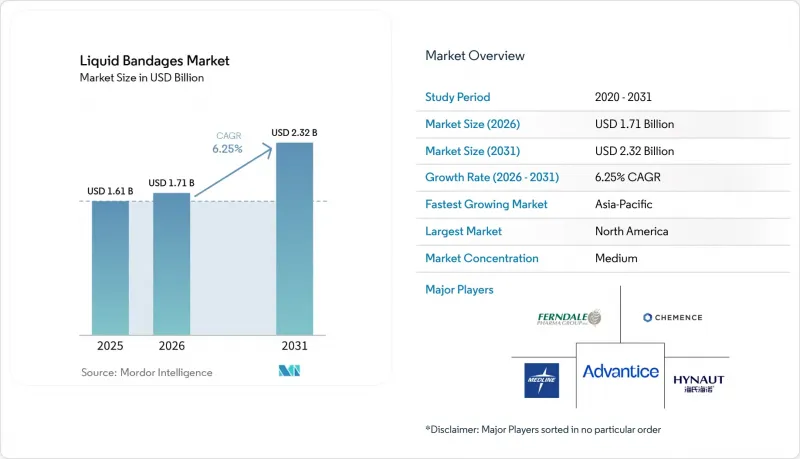
Global Liquid Bandages Market Trends and Insights
Growth in Minor-Wound Self-Care and Convenience-Led First Aid
Consumers increasingly manage minor wounds at home rather than making unplanned pharmacy visits. Spray and liquid-film formats supported this preference through quick application and compatibility with daily activities. In January 2026, Beiersdorf launched Second Skin Protection Spray Plaster and Liquid Plaster Concentrate under its Hansaplast, Elastoplast, and CURITAS brands. Research cited by the company showed that 58% of consumers avoided conventional plasters due to visibility, discomfort, or poor fit on difficult body areas. Beiersdorf's Health Care segment recorded 8.8% organic sales growth in the first nine months of 2025, supported by wound care and Second Skin Protection products. In the liquid bandages market, shelf visibility and established brand confidence remained key short-term purchase drivers.
Rising Chronic-Wound and Diabetic-Foot-Care Demand
Diabetic foot ulcers created a long-term demand base that was less dependent on discretionary consumer spending. A 2025 study reported 18.6 million new diabetic foot ulcer cases annually worldwide and estimated the lifetime risk among people with diabetes at 19% to 34%. Diabetes affected 11.11% of adults globally in 2024, representing 589 million people. Liquid films supported early-stage diabetic foot and peri-wound care by providing a water-resistant protective layer without requiring clinical application skills. The supplied analysis reported a 13% diabetic foot ulcer prevalence among diabetes patients in North America, while South and East Asia accounted for the fastest-growing disease burden. The liquid bandages market had a growing clinical opportunity as podiatry and wound-care centers added topical barriers alongside advanced dressings.
Skin Irritation, Stinging and Sensitization Risk
Tolerability can limit repeat use, particularly among the category's largest consumer segment. Legacy n-butyl cyanoacrylate and alcohol-solvent formulations may cause short-term stinging, while contact sensitization may prevent future product use among affected consumers. Although the FDA evaluates biocompatibility during premarket review, the supplied analysis noted that post-launch sensitization in real-world populations remained less clearly characterized. This risk drives demand for 2-octyl cyanoacrylate and silicone-based alternatives despite their higher material and manufacturing costs.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Surgical and Procedural Use of Topical Adhesives
- Expansion of Sports, Outdoor and Worksite Injury Prevention
- Clinical and Regulatory Claim Boundaries Across Skin Protectant and Tissue Adhesive Uses
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Skin Protectants accounted for 62.45% of the liquid bandages market share in 2025. Consumer familiarity, broad availability, and a long history of over-the-counter use supported the segment's leading position. The segment addressed minor cuts, blisters, abrasions, and cracked skin across household, workplace, and sports settings. Its high-volume sales base provided established brands with a strong retail foundation. Tissue Adhesives represented a smaller revenue segment but are forecast to grow at a CAGR of 7.26% from 2026 to 2031, driven by increasing institutional use in surgical procedures and emergency wound management.
Regulatory requirements created a barrier to entry for cleared tissue adhesive products. Optmed received clearance for TearRepair in September 2024, while Resivant Medical completed the first clinical use of Cutiva(TM) PLUS in June 2026. Skin Protectants used widely available polymer chemistries and faced higher supplier competition. Tissue Adhesives relied on specialty-grade cyanoacrylate monomers from a narrower supplier base, increasing exposure to supply disruptions and price volatility. Long-term supply agreements or backward integration can improve reliability for institutional buyers.
Liquid products held the largest form-level revenue share at 34.55% in 2025. Bottled and ampoule formats provided controlled application and bond strength for consumer and clinical use. Spray is forecast to be the fastest-growing format, registering a CAGR of 9.44% from 2026 to 2031. Its no-touch application and 30-second drying time support use on larger abrasions and uneven skin surfaces in active settings. Beiersdorf launched both spray and liquid products in January 2026 to address these varied use requirements.
Gel formulations served chronic wound and peri-surgical applications, as their higher viscosity enabled controlled placement on fragile skin without runoff. Foam formats represented the smallest share in the supplied assessment but gained attention in wound-care centers requiring exudate management and physical coverage. Propellant-free pump sprays also emerged as a product development opportunity. These designs can reduce flammability and storage concerns associated with aerosol-propellant over-the-counter formulations.
Complete Report Scope:
- By Product Type
- Skin Protectants
- Tissue Adhesives
- By Form
- Liquid
- Spray
- Gel
- Foam
- By Application
- Minor Cuts and Scrapes
- Abrasions and Blisters
- Chronic and Diabetic Wounds
- Surgical and Procedural Wound Closure
- Burns and Other Skin Openings
- By End User
- Households and Personal First Aid
- Hospitals
- Clinics and Physician Offices
- Ambulatory Surgery Centers
- Podiatry and Wound-Care Centers
- Others
- By Distribution Channel
- Retail Pharmacies
- Hospital Pharmacies
- Supermarkets and Mass Merchandisers
- Online Pharmacies
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held a 42.34% share of the liquid bandages market in 2025, supported by established over-the-counter purchasing behavior and robust pharmacy and e-commerce channels. The United States supported consumer and institutional demand, while CMS listed HCPCS codes A6250 and A6251 for liquid skin barriers in its January 2025 quarterly update, providing hospitals with a reimbursement reference for institutional-grade products. Canada's purchasing patterns closely followed those of the United States, while Mexico expanded through modern retail pharmacy chains.
Europe was the second-largest regional market in the assessment. Germany, the United Kingdom, and France supported institutional demand through specialized wound care centers and hospital formulary purchasing, supported by the regional manufacturing and distribution infrastructure of B. Braun Melsungen, Molnlycke Health Care, and Coloplast. Smith+Nephew introduced ALLEVYN COMPLETE CARE Foam Dressing in the United States in March 2026 and planned European availability later in 2026. Italy, Spain, and other European countries offered growth opportunities for convenience formats as pharmacy coverage improved.
Asia-Pacific is forecast to grow at a 9.53% CAGR from 2026 to 2031, the fastest regional growth rate. China and India have large and expanding diabetes populations, increasing demand for chronic and diabetic wound protection, while Japan has a mature category led by Kobayashi Pharmaceutical and Taisho Pharmaceutical. South Korea and Australia have advanced procurement channels for topical adhesives. The Middle East, Africa, and South America remain smaller markets, but GCC retail expansion and Brazil's high diabetes burden support demand across over-the-counter and institutional settings.
- Advantice Health, LLC
- Aleo BME, Inc.
- Chemence Medical, Inc.
- Ferndale Laboratories, Inc.
- Haishi Hainuo Group Co., Ltd.
- KeriCure, Inc.
- Kobayashi Pharmaceutical Co., Ltd.
- Medline Industries
- Optmed, Inc.
- Rochal Industries, LLC
- Smiths Group
- Solventum
- Taisho Pharmaceutical Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth in Minor-Wound Self-Care and Convenience-Led First Aid
- 4.2.2 Rising Chronic-Wound and Diabetic-Foot-Care Demand
- 4.2.3 Increasing Surgical and Procedural Use of Topical Adhesives
- 4.2.4 Expansion of Sports, Outdoor and Worksite Injury Prevention
- 4.2.5 Longer-Wear Cyanoacrylate Films Reducing Reapplication Burden
- 4.2.6 Liquid Application Solving Coverage on High-Flex and Irregular Skin Sites
- 4.3 Market Restraints
- 4.3.1 Skin Irritation, Stinging and Sensitization Risk
- 4.3.2 Clinical and Regulatory Claim Boundaries Across Skin Protectant and Tissue Adhesive Uses
- 4.3.3 Flammability, Solvent Odor and Storage Constraints in OTC Formulations
- 4.3.4 Applicator-Dose Variability and Film-Removal Friction in Home Use
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Product Type
- 5.1.1 Skin Protectants
- 5.1.2 Tissue Adhesives
- 5.2 By Form
- 5.2.1 Liquid
- 5.2.2 Spray
- 5.2.3 Gel
- 5.2.4 Foam
- 5.3 By Application
- 5.3.1 Minor Cuts and Scrapes
- 5.3.2 Abrasions and Blisters
- 5.3.3 Chronic and Diabetic Wounds
- 5.3.4 Surgical and Procedural Wound Closure
- 5.3.5 Burns and Other Skin Openings
- 5.4 By End User
- 5.4.1 Households and Personal First Aid
- 5.4.2 Hospitals
- 5.4.3 Clinics and Physician Offices
- 5.4.4 Ambulatory Surgery Centers
- 5.4.5 Podiatry and Wound-Care Centers
- 5.4.6 Others
- 5.5 By Distribution Channel
- 5.5.1 Retail Pharmacies
- 5.5.2 Hospital Pharmacies
- 5.5.3 Supermarkets and Mass Merchandisers
- 5.5.4 Online Pharmacies
- 5.5.5 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Advantice Health, LLC
- 6.3.2 Aleo BME, Inc.
- 6.3.3 Chemence Medical, Inc.
- 6.3.4 Ferndale Laboratories, Inc.
- 6.3.5 Haishi Hainuo Group Co., Ltd.
- 6.3.6 KeriCure, Inc.
- 6.3.7 Kobayashi Pharmaceutical Co., Ltd.
- 6.3.8 Medline Industries, LP
- 6.3.9 Optmed, Inc.
- 6.3.10 Rochal Industries, LLC
- 6.3.11 Smith & Nephew plc
- 6.3.12 Solventum
- 6.3.13 Taisho Pharmaceutical Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

