PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155647

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155647
Disposable Tweezers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
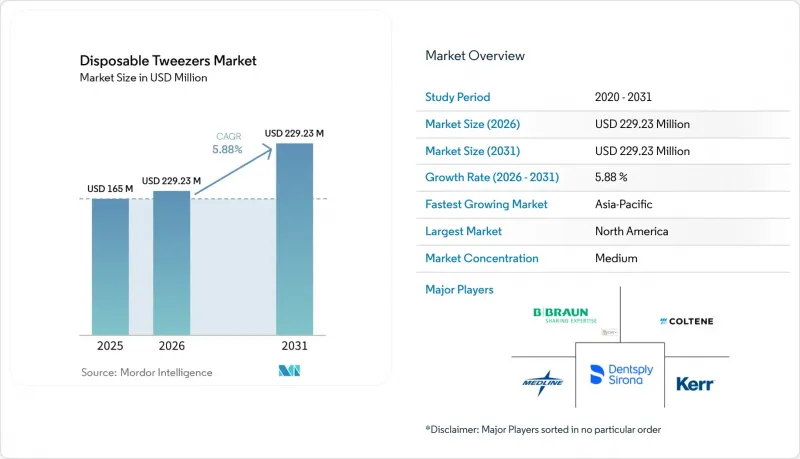
According to Mordor Intelligence, the disposable tweezers market size is expected to grow from USD 165 million in 2025 to USD 229.23 million in 2026 and is forecast to reach USD 229.23 million by 2031 at 5.88% CAGR over 2026-2031.
Global Disposable Tweezers Market Trends and Insights
Infection Prevention and Cross-Contamination Control
Healthcare-associated infections continue to create a direct need for reliable infection prevention in hospitals and clinics. The disposable tweezers market gains from this need because a single-use instrument avoids reuse-related contamination risk. Reprocessing requires cleaning, disinfection, sterilization, and inspection, and each step requires validated procedures. The Centers for Disease Control and Prevention identifies single-use devices as appropriate where reuse and cleaning reliability are uncertain. Facilities without validated reprocessing capacity can use prepackaged sterile products to support consistent clinical practice. This keeps demand strongest in settings with rapid patient turnover and limited instrument-processing resources.
Growth in Dental, Surgical, and Clinical Procedures
A higher number of procedures increases the consumption of instruments used for tissue handling, dressing, and specimen work. The International Society of Aesthetic Plastic Surgery reported nearly 38 million aesthetic procedures in its 2024 global survey, including more than 2.1 million eyelid surgeries. Each procedure can require a fresh set of instruments when clinical protocols require single-use products. Dental practices also use single-use devices where cleaning is difficult or where they cannot be heat sterilized. Growth in outpatient and minimally invasive care supports frequent replenishment of basic consumables. The disposable tweezers market, therefore, depends on procedure volumes as well as the required level of instrument control.
Medical-Waste Treatment and Disposal Costs
Disposables add waste handling requirements after clinical use, which can weaken their cost advantage in lower-volume settings. The U.S. Environmental Protection Agency sets requirements for hazardous waste generators, and healthcare facilities must manage regulated waste within applicable rules. Higher collection, treatment, and disposal charges affect the full cost of a single-use product. The effect can be more pronounced when facilities use high volumes of individually packaged sterile instruments. Compact packaging and material-efficient formats can reduce the waste burden associated with each unit. The disposable tweezers market faces greater pressure where facilities evaluate procurement and waste expenses together.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Laboratory Automation and High-Throughput Testing
- Growth of Online and Direct Procurement Channels
- Price Premium Versus Reusable Tweezers in Low-Volume Settings
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastic held 72.21% of disposable tweezers market share in 2025. Polypropylene supports cost-efficient production, color coding, and compatibility with gamma irradiation. Its light weight can also support repeated instrument exchanges during wound care and routine clinical work. The material remains the common choice for high-volume hospital purchasing. Stainless steel serves applications that need greater tip precision but do not require a premium titanium product. Dental procedures and general surgical wound closure remain relevant uses for disposable stainless-steel designs.
Titanium is forecast to grow at a 6.8% CAGR from 2026 to 2031. Its corrosion resistance and nonmagnetic properties support use in neurosurgery, ophthalmology, and advanced diagnostic work. AROSurgical introduced FDA-cleared disposable titanium spring microvascular clamps in October 2025 with a calibrated 15-120 g force range and radiopaque visibility. ISO 13402:2025 sets test methods for resistance to autoclaving, corrosion, and thermal exposure in surgical and dental hand instruments. Commodity plastic lines are likely to face stronger price competition in bulk tenders. Titanium and specialty-polymer lines can support higher pricing when users require demonstrated precision and material performance.
Straight-tip tweezers held 39.2% of the disposable tweezers market share in 2025. Their general-purpose design supports wound care, dental cotton placement, and routine specimen handling. Users value a firm grasp and consistent basic performance in these applications. Curved tips support access to recessed anatomy during ENT and ophthalmic procedures. Slanted designs can assist fine laboratory work and peripheral nonclinical uses. Straight-tip products therefore retain broad purchasing relevance across routine clinical settings.
Pointed-tip tweezers are forecast to grow at a 6.3% CAGR from 2026 to 2031. This geometry supports precise handling in laboratory diagnostics, histology, and forensic sample work. Fine-tipped instruments can also support tissue handling and specimen retrieval in minimally invasive procedures. Product developers are adding asymmetric tip designs, textured grips, and locking mechanisms to differentiated formats. These features move pointed-tip products beyond a basic commodity design. The disposable tweezers market can gain value where users require consistent handling of very small objects in confined work areas.
Complete Report Scope:
- By Material
- Plastic
- Stainless Steel
- Titanium
- By Tip Geometry
- Straight Tip
- Pointed Tip
- Curved Tip
- Slanted Tip
- By Sterility Status
- Sterile
- Non-Sterile
- By Application
- Surgical Procedures
- Wound Care & Dressing
- Diagnostic Procedures
- Dental Procedures
- Laboratory & Clinical Diagnostics
- By End User
- Hospitals
- Ambulatory Surgery Centers
- Specialty Clinics
- Others (Clinical Laboratories, Academic & Research Institutions)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 34.1% of the disposable tweezers market share in 2025. The United States has a dense network of hospitals, ambulatory surgery centers, and dental practices that use high volumes of clinical consumables. Infection-control guidance from the CDC supports the appropriate use of single-use devices. Henry Schein reported USD 13.2 billion in 2025 revenue, with 69% of net sales generated through U.S. operations. MedPAC reported continued ASC volume growth, which supports demand for sterile and precision-oriented formats. Canada and Mexico add incremental volume through hospital investment and expanding private care activity.
Europe remains a significant regional base, with Germany, the United Kingdom, and France as major volume markets. Regional demand is moderated by concerns about medical waste, packaging, and the use of single-use plastics. Regulation (EU) 2025/40 establishes packaging and packaging waste requirements that will affect medical product packaging, while specific healthcare provisions may apply. Article 17 of the EU Medical Device Regulation also creates different national conditions for reprocessing single-use devices. This variation makes country-level regulatory planning important for suppliers. The region offers stable procedure demand, but product designs must respond to environmental requirements and purchasing preferences.
Asia-Pacific is forecast to grow at a 6.7% CAGR from 2026 to 2031. China, India, and Southeast Asian countries are expanding hospital and outpatient capacity, which broadens the customer base for disposable supplies. Japan's medical device framework includes a registration category for disposable tweezers under code 35079001. India's tertiary hospital development and Southeast Asia's outpatient facilities add to regional demand. Middle East and Africa and South America remain smaller opportunities, supported by modernization programs and private hospital expansion. Long-distance distribution can make sterile shelf-life management more difficult in these regions.
- Rubis
- Dumont Tweezers
- Excelta Corporation
- Ideal-tek SA
- Robert Burkle GmbH
- Sampling Systems Ltd
- TIGA-MED Deutschland GmbH
- MECO Instruments Pvt. Ltd
- Arrowhead Forensics
- AmScope
- Avantor Inc.
- Heathrow Scientific LLC
- Henry Schein
- LABOAO
- Medline Industries
- Misumi Group Inc.
- B. Braun
- Hu-Friedy Mfg
- Ultradent Products, Inc.
- Dentsply Sirona
- Patterson Companies
- Kerr
- COLTENE Group
- GC Corporation
- Young Innovations
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Infection Prevention and Cross-Contamination Control
- 4.2.2 Growth in Dental, Surgical and Clinical Procedures
- 4.2.3 Expansion of Laboratory Automation and High-Throughput Testing
- 4.2.4 Growth of Online and Direct Procurement Channels
- 4.2.5 Demand for Cleanroom-Compatible, Ready-to-Use Instruments
- 4.2.6 Material Innovation Enabling Lower-Impact Disposable Designs
- 4.3 Market Restraints
- 4.3.1 Medical-Waste Treatment and Disposal Costs
- 4.3.2 Price Premium Versus Reusable Tweezers in Low-Volume Settings
- 4.3.3 Sterility-Shelf-Life Risk in Long-Distance Distribution
- 4.3.4 Plastic Restrictions and Procurement Preference for Reusable Instruments
- 4.4 Value and Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Material
- 5.1.1 Plastic
- 5.1.2 Stainless Steel
- 5.1.3 Titanium
- 5.2 By Tip Geometry
- 5.2.1 Straight Tip
- 5.2.2 Pointed Tip
- 5.2.3 Curved Tip
- 5.2.4 Slanted Tip
- 5.3 By Sterility Status
- 5.3.1 Sterile
- 5.3.2 Non-Sterile
- 5.4 By Application
- 5.4.1 Surgical Procedures
- 5.4.2 Wound Care & Dressing
- 5.4.3 Diagnostic Procedures
- 5.4.4 Dental Procedures
- 5.4.5 Laboratory & Clinical Diagnostics
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Ambulatory Surgery Centers
- 5.5.3 Specialty Clinics
- 5.5.4 Others (Clinical Laboratories, Academic & Research Institutions)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Rubis
- 6.3.2 Dumont Tweezers
- 6.3.3 Excelta Corporation
- 6.3.4 Ideal-tek SA
- 6.3.5 Robert Burkle GmbH
- 6.3.6 Sampling Systems Ltd
- 6.3.7 TIGA-MED Deutschland GmbH
- 6.3.8 MECO Instruments Pvt. Ltd
- 6.3.9 Arrowhead Forensics
- 6.3.10 AmScope
- 6.3.11 Avantor Inc.
- 6.3.12 Heathrow Scientific LLC
- 6.3.13 Henry Schein, Inc.
- 6.3.14 LABOAO
- 6.3.15 Medline Industries, LP
- 6.3.16 Misumi Group Inc.
- 6.3.17 B. Braun Melsungen AG
- 6.3.18 Hu-Friedy Mfg. Co., LLC
- 6.3.19 Ultradent Products, Inc.
- 6.3.20 Dentsply Sirona Inc.
- 6.3.21 Patterson Companies, Inc.
- 6.3.22 Kerr Corporation
- 6.3.23 COLTENE Group
- 6.3.24 GC Corporation
- 6.3.25 Young Innovations
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

