PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155679

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2155679
Mobile Operating Tables - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
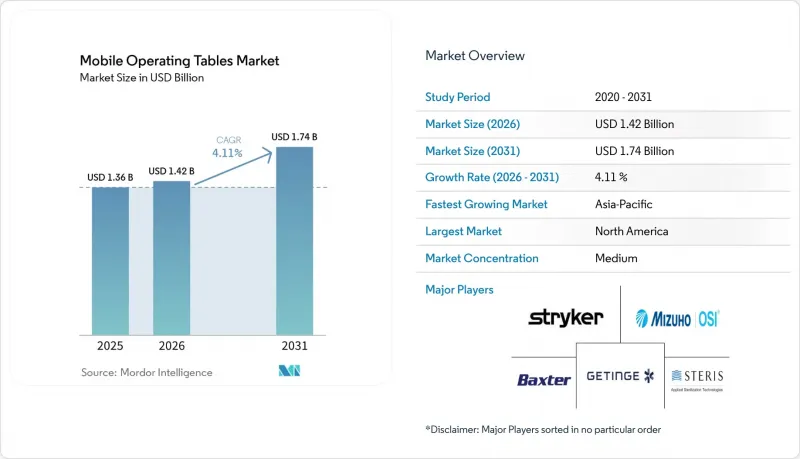
According to Mordor Intelligence, the mobile operating tables market size is expected to increase from USD 1.36 billion in 2025 to USD 1.42 billion in 2026 and reach USD 1.74 billion by 2031, growing at a CAGR of 4.11% over 2026-2031.
Global Mobile Operating Tables Market Trends and Insights
Rising Surgical Volumes and Unmet Surgical Demand
Surgical demand is increasing the need for adaptable operating-room capacity. Hospitals that manage several surgical specialties need equipment that can support different patient positions and clinical workflows. Mobile tables can be moved between rooms when scheduling priorities change. This supports more flexible use of installed surgical space. New capacity projects also create opportunities to replace equipment that is nearing the end of its useful life. The Mobile operating tables market benefits when providers seek to improve room availability without building separate specialty facilities.
Growth of Minimally Invasive, Image-Guided, and Robotic Surgery
Robotic and image-guided surgery is raising the functional requirements for operating tables. An international expert consensus published in 2025 identified operating-table motion knowledge and position optimization as important competencies for robotic surgical teams. A 2026 prospective hysterectomy study assessed da Vinci X, Versius, and Hugo robotic systems in minimally invasive procedures. These procedures require reliable access, stable positioning, and space for robotic docking. Product specifications, therefore, matter more when a hospital invests in a robotic platform. The mobile operating tables market gains from tables that can adapt to the positioning needs of minimally invasive and robotic surgery.
High Capital Cost of Advanced Mobile Operating Tables
Advanced tables require a higher capital commitment than basic hydraulic models. Imaging compatibility, powered movements, programmable positions, and connected functions add to product complexity. Providers with limited budgets may retain older equipment for longer periods. The pressure is stronger when buyers depend on imported equipment and lack financing options. This can preserve demand for established hydraulic and manual systems in lower-budget settings. The mobile operating tables market, therefore, has different upgrade rates across hospital tiers and geographic markets.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Ambulatory Surgical Centers
- Hospital Modernization and Replacement of Legacy Tables
- Shortage of Trained Operating-Room Personnel
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hydraulic tables held 44.65% of the mobile operating tables market share in 2025. Their position reflects reliability in high-load settings and a substantial installed base at established hospitals. These tables also have lower maintenance complexity than more advanced powered systems. Many facilities retain them because they remain appropriate for routine surgical procedures. Their continued use reflects replacement timing as well as clinical preference. This provides a stable base for the mobile operating tables industry.
Electro-hydraulic tables are forecast to expand at a 6.43% CAGR from 2026 to 2031. Their value proposition includes controlled powered movement and compatibility with advanced surgical workflows. Getinge describes the Maquet Corin as a guided mobile surgical table with simultaneous multidirectional adjustments and capacity for up to 30 personalized user sequences. The product offers a load capacity of up to 545 kg and can provide Trendelenburg or reverse Trendelenburg adjustment of up to 45 degrees. Electric tables are also relevant to ambulatory surgery centers that need compact powered positioning. Manual, pneumatic, and hybrid products remain useful where simplicity, budget, and power-resilience needs guide buying decisions.
Complete Report Scope:
- By Product Type
- Hydraulic Mobile Operating Tables
- Electric Mobile Operating Tables
- Electro-Hydraulic Mobile Operating Tables
- Manual Mobile Operating Tables
- Pneumatic Mobile Operating Tables
- Hybrid Mobile Operating Tables
- By Application
- General Surgery
- Orthopedic and Trauma Surgery
- Cardiovascular Surgery
- Neurosurgery
- Gynecological Surgery
- Urological Surgery
- Other Applications
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics
- Diagnostic Centers
- Other End Users
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 40.43% of the mobile operating tables market share in 2025. The region combines high surgical spending, a mature ambulatory surgery center system, and continued investment in operating-room technology. Hospitals in the United States are significant buyers of connected, imaging-compatible, and specialty table configurations. Established suppliers benefit from service coverage and existing clinical relationships. The mobile operating tables market in North America also benefits from replacement demand as health systems renovate operating rooms.
Outpatient care is an important part of regional procurement patterns. Getinge and Zimmer Biomet began their ambulatory surgery center partnership in the United States, with plans to offer the combined portfolio in additional regions. The arrangement responds to an outpatient setting where room efficiency and procedure-specific equipment packages are important. Canada and Mexico also contribute to demand as outpatient surgery capacity develops. Suppliers must meet the clinical, service, and regulatory expectations of providers throughout the region.
Europe remains an important region for technically advanced surgical equipment. Buyers place emphasis on ergonomic design, product durability, and clinical customization. The European regulatory environment favors companies with established quality and documentation systems. European manufacturers retain positions in specialty applications and regional hospital accounts. The region also supplies advanced products to other markets through established distribution networks. The mobile operating tables market is supported by modernization programs in large public and private hospital systems.
Asia-Pacific is forecast to expand at a 5.87% CAGR from 2026 to 2031. Hospital construction, healthcare capacity additions, and equipment modernization support demand across the region. China and India are important because of their expanding surgical infrastructure. Japan, South Korea, and Australia support demand for higher-specification equipment in robotic and image-guided procedures. Getinge launched the Maquet Corin table, Maquet Ezea light, and Fluoptics imaging solutions in Singapore in 2024. The launch presented the Corin as Getinge's first connected operating table and included service data and usage statistics functions. Price sensitivity and import costs can still affect purchase timing in parts of Asia-Pacific, the Middle East and Africa, and South America.
- AGA Sanitaetsartikel GmbH
- Alvo Medical Sp. Zo.o.
- Fazzini SRL
- Famed Zywiec Sp. Zo.o.
- Getinge-Maquet Germany Holding GmbH
- Hill-Rom
- Image Diagnostics Inc.
- Lojer Oy
- Merivaara Oy
- Mizuho
- medifa
- Ningbo Techart Medical Equipment Co., Ltd
- Skytron
- Schaerer Medical USA Inc
- Stryker
- STERIS
- UFSK-International OSYS
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope Of The Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Surgical Volumes and Unmet Surgical Demand
- 4.2.2 Growth of Minimally Invasive, Image-Guided and Robotic Surgery
- 4.2.3 Expansion of Ambulatory Surgical Centers
- 4.2.4 Hospital Modernization and Replacement of Legacy Tables
- 4.2.5 Battery-Powered Mobility for Power-Constrained Operating Rooms
- 4.2.6 Connected-Table Service Telemetry and Predictive Maintenance
- 4.3 Market Restraints
- 4.3.1 High Capital Cost of Advanced Mobile Operating Tables
- 4.3.2 Shortage of Trained Operating-Room Personnel
- 4.3.3 Actuator, Controller and Electronics Lead-Time Exposure
- 4.3.4 Reprocessing, Battery and Sensor Complexity
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat Of New Entrants
- 4.7.2 Bargaining Power Of Buyers
- 4.7.3 Bargaining Power Of Suppliers
- 4.7.4 Threat Of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Hydraulic Mobile Operating Tables
- 5.1.2 Electric Mobile Operating Tables
- 5.1.3 Electro-Hydraulic Mobile Operating Tables
- 5.1.4 Manual Mobile Operating Tables
- 5.1.5 Pneumatic Mobile Operating Tables
- 5.1.6 Hybrid Mobile Operating Tables
- 5.2 By Application
- 5.2.1 General Surgery
- 5.2.2 Orthopedic and Trauma Surgery
- 5.2.3 Cardiovascular Surgery
- 5.2.4 Neurosurgery
- 5.2.5 Gynecological Surgery
- 5.2.6 Urological Surgery
- 5.2.7 Other Applications
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Ambulatory Surgical Centers
- 5.3.3 Specialty Clinics
- 5.3.4 Diagnostic Centers
- 5.3.5 Other End Users
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(Includes Global Level Overview, Market Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share For Key Companies, Products & Services, And Recent Developments)}
- 6.3.1 AGA Sanitaetsartikel GmbH
- 6.3.2 Alvo Medical Sp. Zo.o.
- 6.3.3 Fazzini SRL
- 6.3.4 Famed Zywiec Sp. Zo.o.
- 6.3.5 Getinge-Maquet Germany Holding GmbH
- 6.3.6 Hill-Rom Holdings Inc
- 6.3.7 Image Diagnostics Inc.
- 6.3.8 Lojer Oy
- 6.3.9 Merivaara Oy
- 6.3.10 Mizuho Corporation
- 6.3.11 medifa-hesse GmbH & Co. KG
- 6.3.12 Ningbo Techart Medical Equipment Co., Ltd
- 6.3.13 Skytron LLC
- 6.3.14 Schaerer Medical USA Inc
- 6.3.15 Stryker Corporation
- 6.3.16 Steris Plc
- 6.3.17 UFSK-International OSYS GmbH
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

