PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2156869

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2156869
Germany Pharmaceutical Cold Chain Air Logistics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
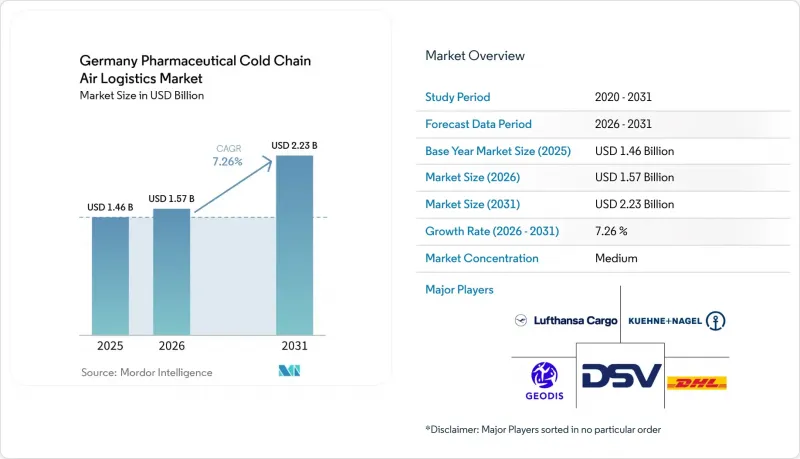
According to Mordor Intelligence, the Germany pharmaceutical cold chain air logistics market size was valued at USD 1.46 billion in 2025 and is projected to expand from USD 1.57 billion in 2026 to USD 2.23 billion by 2031, registering a CAGR of 7.26% between 2026 and 2031.
Biologics, biosimilars, vaccines, and advanced therapies require validated temperature control throughout transit, which supports demand for specialized air services. This report is Segmented by Temperature Range (Chilled, Frozen, Ambient, Deep-Frozen/Ultra-Low), by Pharmaceutical Product Type (Small-Molecule, Biological, Specialty, Cell and Gene Therapies, Veterinary, Other), by Shipment Flow (Domestic, International), and by Region (North Rhine-Westphalia, Bavaria, and More). The Market Forecasts are Provided in Terms of Value (USD).
Germany Pharmaceutical Cold Chain Air Logistics Market Trends and Insights
Biologics and Biosimilars Adoption
Germany's pharmacy-level biosimilar substitution framework expanded from 2025 and shifted established biologics into retail pharmacy channels. This change created additional GDP-compliant delivery routes that smaller operators might not be able to manage internally. Germany's statutory health insurance network included 19,000 pharmacies, each representing a potential destination when biologics move into outpatient dispensing. Manufacturers increased inbound shipments through Frankfurt ahead of substitution-related demand, favoring providers with dedicated pharmaceutical capacity. Monoclonal antibodies, growth factors, and insulin analogs need continuous 2-8 °C handling even when biosimilar entry reduces unit prices. The Germany pharmaceutical cold chain air logistics market therefore, gains demand at both the import stage and the pharmacy delivery stage.
Germany as a Central European Pharmaceutical Distribution Hub
Frankfurt Airport handled 200,000 tons of pharmaceutical and healthcare freight annually through 22,000 m2 of temperature-controlled cargo space in 2025. Of this area, 14,000 m2 was specifically configured for pharmaceutical handling. The site was served by 83 airlines and connected 275 destinations across 91 countries. Its location near BioNTech, Merck, and Boehringer Ingelheim supports daily cold-chain departures instead of weekly consolidation schedules. Frankfurt joined Pharma.Aero as a full member in December 2025, which formalized its participation in pharmaceutical air cargo standards. Munich and Dusseldorf provide additional pharmaceutical gateways, giving Bavaria and North Rhine-Westphalia parallel access to export routes
High Energy Costs for Refrigerated Facilities and Equipment
Germany remained among the European Union's highest-priced industrial electricity markets through 2025. Energy spending at cold-storage sites represented 25-40% of operating costs, compared with less than 5% for ambient warehouses. The revised EU F-Gas Regulation requires a phase-down in high-global-warming-potential refrigerants. This increases investment needs for carbon dioxide and ammonia cascade systems. Separate equipment, redundancy, and calibration are needed for 2-8 °C, -20 °C, and -70 °C zones. These costs place pressure on mid-sized operators that cannot spread energy hedging and compliance upgrades across large national networks.
Other drivers and restraints analyzed in the detailed report include:
- Cell and Gene Therapy Clinical-Trial Activity
- Direct-to-Patient Delivery of Complex Biologics
- Shortage of GDP-Certified Drivers and Cold-Chain Technicians
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Chilled shipments held 48.12% of temperature-range revenue in 2025, making this the largest part of the Germany pharmaceutical cold chain air logistics market share by temperature range. Monoclonal antibodies, biosimilars, and conventional vaccines support this position because they move under standard cold-chain conditions through Frankfurt air lanes. Cell and gene therapies and mRNA-based products need cryogenic handling, which supports demand for deep-frozen and ultra-low services. DHL expanded its Florstadt campus in May 2025 with a fourth warehouse, taking total capacity to 100,000 m2 and adding capability down to -70 °C. The investment positioned the site for commercial advanced-therapy volumes. Carriers also expanded active and passive 2-8 °C packaging on frequent routes, supporting the chilled segment's role as the revenue base.
Deep-frozen and ultra-low shipments are forecast to record a 11.24% CAGR from 2026 to 2031, the fastest growth rate among the temperature ranges. Frozen shipments serve vaccines, insulin products, and biologic medicines with mid-range stability requirements. These products support an established share because their handling procedures are already well defined. Ambient shipments remain a smaller part of pharmaceutical air freight. They mainly include time-critical branded medicines where speed supports the cost of air transportation even without active cooling. The temperature mix is expected to move toward colder requirements through 2031. This change follows the movement of advanced therapies from clinical trials into routine dispensing. Frozen and ambient shipments are expected to lose share gradually as deeper cold chain needs grow. The Germany pharmaceutical cold chain air logistics market requires providers to maintain several validated temperature zones rather than rely on a single chilled offering.
Complete Report Scope:
- By Temperature Range
- Chilled (0-5 °C)
- Frozen (-18-0 °C)
- Ambient
- Deep-Frozen / Ultra-Low (More than -20 °C)
- By Pharmaceutical Product Type
- Small-Molecule Pharmaceuticals
- Branded Pharmaceuticals
- Over-the-Counter (OTC) Pharmaceuticals
- Generic Pharmaceuticals
- Biological Pharmaceuticals (Biologics, Biosimilars, Vaccines, and Blood-Derived Medicinal Products)
- Specialty Pharmaceuticals
- Cell and Gene Therapies
- Veterinary Pharmaceuticals
- Other Pharmaceutical Products
- Small-Molecule Pharmaceuticals
- By Shipment Flow
- Domestic Shipments
- International Shipments
- By Region
- North Rhine-Westphalia
- Bavaria (Bayern)
- Baden-Wurttemberg
- Rest of States
List of Companies Covered in this Report:
- DHL Group
- Kuehne+Nagel International AG
- DSV A/S (including former DB Schenker operations)
- GEODIS (including trans-o-flex)
- CEVA Logistics (CMA CGM Group)
- United Parcel Service, Inc. (UPS Healthcare, including Marken)
- FedEx Corporation
- Lufthansa Cargo AG
- World Courier (Cencora, Inc.)
- Rhenus Group
- Hellmann Worldwide Logistics SE & Co. KG
- Expeditors International of Washington, Inc.
- Nippon Express Holdings, Inc. (NX Group)
- Yusen Logistics Co., Ltd
- Kintetsu World Express, Inc.
- DACHSER SE
- Swissport International AG
- JAS Worldwide
- AIT Worldwide Logistics, Inc.
- Logwin AG
- B.P.L. GmbH (BPL - Biotech & Pharma Logistics)
- Logistics4Pharma GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview and Importance of Pharmaceutical Cold Chain Air Freight Logistics
- 4.2 Market Drivers
- 4.2.1 Biologics and Biosimilars Adoption
- 4.2.2 Germany as a Central European Pharmaceutical Distribution Hub
- 4.2.3 Cell and Gene Therapy Clinical-Trial Activity
- 4.2.4 Direct-to-Patient Delivery of Complex Biologics
- 4.2.5 Rising mRNA and Advanced-Therapy Production
- 4.2.6 Air-Cargo Network Investment and Pharmaceutical Hub Expansion
- 4.3 Market Restraints
- 4.3.1 High Energy Costs for Refrigerated Facilities and Equipment
- 4.3.2 Shortage of GDP-Certified Drivers and Cold-Chain Technicians
- 4.3.3 Cross-Border Price Competition from Eastern European Providers
- 4.3.4 Limited Medical-Grade Drone Corridors for Time-Critical Deliveries
- 4.4 Value and Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Major Pharmaceutical Air Cargo Gateways and Infrastructure
- 4.8 Pharmaceutical Import Export Flows and Major Trade Corridors
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Threat of New Entrants
- 4.9.2 Bargaining Power of Buyers and Consumers
- 4.9.3 Bargaining Power of Suppliers
- 4.9.4 Threat of Substitute Services
- 4.9.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Temperature Range
- 5.1.1 Chilled (0-5 °C)
- 5.1.2 Frozen (-18-0 °C)
- 5.1.3 Ambient
- 5.1.4 Deep-Frozen / Ultra-Low (More than -20 °C)
- 5.2 By Pharmaceutical Product Type
- 5.2.1 Small-Molecule Pharmaceuticals
- 5.2.1.1 Branded Pharmaceuticals
- 5.2.1.2 Over-the-Counter (OTC) Pharmaceuticals
- 5.2.1.3 Generic Pharmaceuticals
- 5.2.2 Biological Pharmaceuticals (Biologics, Biosimilars, Vaccines, and Blood-Derived Medicinal Products)
- 5.2.3 Specialty Pharmaceuticals
- 5.2.4 Cell and Gene Therapies
- 5.2.5 Veterinary Pharmaceuticals
- 5.2.6 Other Pharmaceutical Products
- 5.2.1 Small-Molecule Pharmaceuticals
- 5.3 By Shipment Flow
- 5.3.1 Domestic Shipments
- 5.3.2 International Shipments
- 5.4 By Region
- 5.4.1 North Rhine-Westphalia
- 5.4.2 Bavaria (Bayern)
- 5.4.3 Baden-Wurttemberg
- 5.4.4 Rest of States
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Geographic Coverage, Products and Services, Recent Developments)
- 6.4.1 DHL Group
- 6.4.2 Kuehne+Nagel International AG
- 6.4.3 DSV A/S (including former DB Schenker operations)
- 6.4.4 GEODIS (including trans-o-flex)
- 6.4.5 CEVA Logistics (CMA CGM Group)
- 6.4.6 United Parcel Service, Inc. (UPS Healthcare, including Marken)
- 6.4.7 FedEx Corporation
- 6.4.8 Lufthansa Cargo AG
- 6.4.9 World Courier (Cencora, Inc.)
- 6.4.10 Rhenus Group
- 6.4.11 Hellmann Worldwide Logistics SE & Co. KG
- 6.4.12 Expeditors International of Washington, Inc.
- 6.4.13 Nippon Express Holdings, Inc. (NX Group)
- 6.4.14 Yusen Logistics Co., Ltd
- 6.4.15 Kintetsu World Express, Inc.
- 6.4.16 DACHSER SE
- 6.4.17 Swissport International AG
- 6.4.18 JAS Worldwide
- 6.4.19 AIT Worldwide Logistics, Inc.
- 6.4.20 Logwin AG
- 6.4.21 B.P.L. GmbH (BPL - Biotech & Pharma Logistics)
- 6.4.22 Logistics4Pharma GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
8 APPENDIX

