PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2156936

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2156936
Insulation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
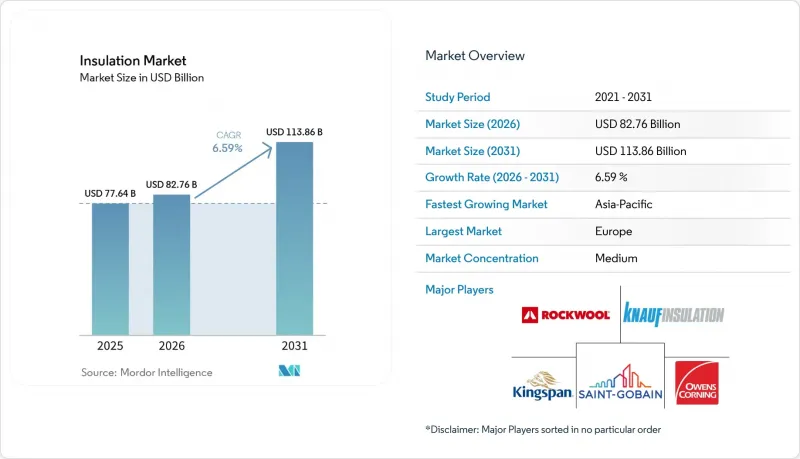
According to Mordor Intelligence, the insulation market size was valued at USD 77.64 billion in 2025 and is estimated to grow from USD 82.76 billion in 2026 to reach USD 113.86 billion by 2031, at a CAGR of 6.59% during the forecast period (2026-2031).
Global Insulation Market Trends and Insights
Tightening Building Energy-Performance Standards
Building codes have shifted from voluntary guidance toward enforceable performance requirements. The European directive requires member states to prepare National Building Renovation Plans. Poor-performing buildings often need envelope improvements before mechanical upgrades become cost-effective. This ordering puts insulation early in many renovation budgets. Washington's Clean Buildings Performance Standard began compliance deadlines on June 1, 2026, for covered commercial buildings. California's code changes also strengthen the regulatory basis for insulation in multifamily and non-residential work.
Building Energy Retrofit Incentives and Renovation Programs
Retrofit programs are becoming a central demand source in mature construction markets. The European Union's Renovation Wave seeks to at least double annual renovation rates and renovate 35 million building units by 2030. Insulation reduces heating demand before renewable heating equipment is installed. This sequencing can improve the effectiveness of later building upgrades. The Inflation Reduction Act supports state-administered Home Energy Rebate programs for household efficiency measures. The Home Electrification and Appliance Rebates program includes up to USD 1,600 for insulation for eligible households. These programs can extend renovation activity into older multifamily housing where project economics were previously difficult.
Volatility in Polymer, Mineral Fiber, and Energy Input Costs
Input costs can pressure margins across the insulation supply chain. Glass fiber and mineral wool manufacturing require substantial energy for furnace operations. Polyurethane foams are exposed to changes in methylene diphenyl diisocyanate (MDI) and toluene diisocyanate (TDI) costs. Producers with fossil-based melting processes face both commodity exposure and pressure from lower-carbon alternatives. Knauf Insulation began operating an electric melting line in Croatia during 2026. The line uses electricity from guaranteed low-carbon sources and can use up to 50% recycled raw material. Such process changes may reshape cost competitiveness over time.
Other drivers and restraints analyzed in the detailed report include:
- Asia-Pacific Construction and Infrastructure Expansion
- EV Battery Thermal Management and Lightweighting
- High Installation Costs and Skilled-Installer Shortages
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fiberglass held 36.38% of the insulation market share in 2025. It benefits from established production, contractor familiarity, and competitive costs in roof, wall, and heating, ventilation, and air conditioning applications. Mineral wool serves projects requiring fire resistance or acoustic performance. Cellulose and natural fibers support selected renovation projects, especially older buildings suited to blow-in installation. Plastic foam is projected to advance at a 7.12% CAGR through 2031. Its performance per unit of thickness supports demand in walls, cold-chain facilities, and battery systems. Aerogel-infused polyurethane can provide a smaller and lighter thermal barrier for vehicle applications.
The insulation market size for fiberglass remains supported by residential batts and blown-in uses. Plastic foam formats, including polyisocyanurate and extruded polystyrene, are increasingly used in continuous wall insulation. Continuous insulation reduces thermal bridging through structural framing. Updated building codes in North America and Europe reinforce this application. Covestro's AdiP technology can reduce steam use by up to 40% and electricity use by 25% per metric ton of MDI produced. ARMACELL supplies elastomeric foam and aerogel products for heating, ventilation, and air conditioning and industrial pipes.
Thermal insulation held 60.72% of the insulation market share in 2025. It is used across buildings, industrial equipment, appliances, and transport systems. The category includes fiberglass, mineral wool, plastic foam, and aerogel products. Acoustic insulation is projected to advance at a 7.65% CAGR through 2031. Urban density and multifamily construction support demand for sound-control materials. Environmental noise is a recognized public health concern in Europe. Dual thermal-acoustic solutions can meet more than one requirement through a single installation.
The insulation market size for thermal products reflects their role in building codes and industrial standards. Fire-protective, cryogenic, and vapor-retarding systems serve more specialized process applications. Cryogenic products are gaining attention in liquefied natural gas infrastructure and cold-process operations. ROCKWOOL A/S and Knauf Insulation offer mineral wool products with thermal and acoustic characteristics. Kingspan Group introduced Troldtekt A-Class acoustic ceiling solutions in Denmark during 2025. The company also reported continued activity in acoustic solutions in its 2026 trading update. Broader certification portfolios can help suppliers serve combined thermal and acoustic specifications.
Complete Report Scope:
- By Material
- Fiberglass
- Mineral Wool
- Plastic Foam
- Cellulose and Natural Fibers
- Other Materials
- By Insulation Function
- Thermal Insulation
- Acoustic Insulation
- Other Insulation Functions
- By Application
- Roof Insulation
- Wall Insulation
- Floor and Basement Insulation
- Other Applications
- By End-User
- Residential
- Non-Residential
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Europe held 36.93% of the insulation market share in 2025. The region has a mature regulatory framework and a broad retrofit pipeline. The European Union's renovation policies and directive requirements support envelope upgrades. Germany, France, the United Kingdom, and Nordic countries remain important revenue contributors. France's and Italy's renovation incentives support high-performance insulation use. Central and Eastern European countries can benefit from European funding for building renovation. These countries include Poland, Czechia, and Romania. Advanced insulation demand is also increasing in Nordic countries with strong national decarbonization programs.
Asia-Pacific is projected to advance at a 7.75% CAGR through 2031. China remains the region's revenue anchor, and India is becoming a more dynamic national market. India's building code framework supports better envelope performance. Japan and South Korea continue to raise energy-efficiency specifications. ASEAN construction activity supports demand in Vietnam, Thailand, and Indonesia. Cold-chain retrofits add industrial demand beyond new construction.
North America retains a stable and significant role in the insulation market. The United States drives regional demand through rebates, commercial construction, and industrial projects. Canada and Mexico add commercial and industrial demand. South America offers longer-term potential as residential standards and industrial activity develop. Brazil and Argentina are central to this opportunity. The Middle East and Africa are supported by construction activity and HVAC-intensive building needs. Saudi Arabia's Vision 2030 program and South Africa's industrial base support regional demand. Lower penetration levels can create a favorable foundation for further insulation adoption.
- ARMACELL
- Aspen Aerogels, Inc.
- Atlas Roofing Corporation
- Carlisle Companies Incorporated
- CNBM INTERNATIONAL CORP.
- Covestro AG
- Dow
- GAF Materials LLC
- Huntsman International LLC
- Johns Manville
- Kingspan Group
- Knauf Insulation
- Owens Corning
- ROCKWOOL A/S
- Saint-Gobain
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Tightening Building Energy-Performance Standards
- 4.2.2 Building Energy Retrofit Incentives and Renovation Programs
- 4.2.3 Asia-Pacific Construction and Infrastructure Expansion
- 4.2.4 EV Battery Thermal Management and Lightweighting
- 4.2.5 Industrial Decarbonization and Process-Energy Optimization
- 4.3 Market Restraints
- 4.3.1 Volatility in Polymer, Mineral Fiber, and Energy Input Costs
- 4.3.2 High Installation Costs and Skilled-Installer Shortages
- 4.3.3 End-of-Life and Recycling Constraints for Composite Systems
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Material
- 5.1.1 Fiberglass
- 5.1.2 Mineral Wool
- 5.1.3 Plastic Foam
- 5.1.4 Cellulose and Natural Fibers
- 5.1.5 Other Materials
- 5.2 By Insulation Function
- 5.2.1 Thermal Insulation
- 5.2.2 Acoustic Insulation
- 5.2.3 Other Insulation Functions
- 5.3 By Application
- 5.3.1 Roof Insulation
- 5.3.2 Wall Insulation
- 5.3.3 Floor and Basement Insulation
- 5.3.4 Other Applications
- 5.4 By End-User
- 5.4.1 Residential
- 5.4.2 Non-Residential
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 NORDIC Countries
- 5.5.3.6 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 ARMACELL
- 6.4.2 Aspen Aerogels, Inc.
- 6.4.3 Atlas Roofing Corporation
- 6.4.4 Carlisle Companies Incorporated
- 6.4.5 CNBM INTERNATIONAL CORP.
- 6.4.6 Covestro AG
- 6.4.7 Dow
- 6.4.8 GAF Materials LLC
- 6.4.9 Huntsman International LLC
- 6.4.10 Johns Manville
- 6.4.11 Kingspan Group
- 6.4.12 Knauf Insulation
- 6.4.13 Owens Corning
- 6.4.14 ROCKWOOL A/S
- 6.4.15 Saint-Gobain
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

