PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2156979

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2156979
Authentication Orchestration - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
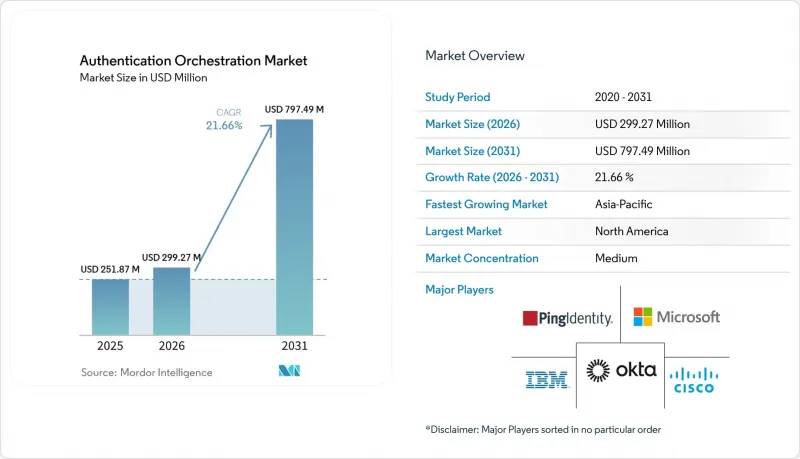
According to Mordor Intelligence, the authentication orchestration market size was USD 251.87 million in 2025 and is estimated to grow from USD 299.27 million in 2026 to reach USD 797.49 million by 2031, at a CAGR of 21.66% during the forecast period 2026-2031.
Global Authentication Orchestration Market Trends and Insights
Identity-Centric Zero-Trust Adoption Anchors Enterprise Authentication Spending
Zero-trust programs are moving from security plans into active purchasing requirements for many organizations, particularly those handling regulated data and complex workforce access. Continuous verification requires checks across sessions, devices, applications, and access requests. The authentication orchestration market benefits from the fact that a single authentication engine cannot reliably manage multiple identity providers and risk signals. Early-stage programs use orchestration software to apply multi-factor authentication consistently across separate environments, instead of maintaining different controls in each application. More mature programs add continuous session checks and behavioral scoring to those foundations, which expands the policy scope after initial deployment. The National Security Agency issued Zero Trust Implementation Guidelines for National Security Systems in January 2026, supporting standards-based procurement across government supply chains.
Phishing-Resistant Authentication Requirements Shorten Procurement Cycles
Regulatory requirements are making phishing-resistant authentication a more immediate purchasing issue for organizations with material digital access risk. NIS2 Article 21 requires multi-factor or continuous authentication for essential entities. The authentication orchestration market can support compliance by enabling organizations to use FIDO2, passkeys, and legacy authentication methods within a single access journey. NIST finalized SP 800-63-4 in July 2025 and recognized syncable passkeys at Authenticator Assurance Level 2. In 2026, the United Kingdom's National Cyber Security Center stated that it recommends using passkeys whenever services support them. These deadlines can reduce the time between technology evaluation and purchasing for regulated financial services organizations with overlapping obligations.
Legacy Application and Protocol Integration Cost Delays Deployment
Legacy integration remains a material barrier for organizations replacing authentication processes, particularly across heavily customized internal applications. Applications built around RACF, LDAP, or SOAP often need discovery work before new policies can go live. Session-based authentication models can also conflict with current OAuth 2.0 refresh-token designs. The authentication orchestration market may face slower near-term adoption where customers manage large on-premises estates and undocumented access flows. These organizations can operate hybrid systems for 12-36 months before policy coverage becomes consistent across their applications. Vendors that offer pre-certified connectors for older protocols can reduce deployment effort and improve their position in long replacement cycles.
Other drivers and restraints analyzed in the detailed report include:
- Account-Takeover and Transaction-Fraud Escalation Forces Authentication Modernization
- Cloud and Hybrid Identity-Stack Complexity Creates Demand for Orchestration Layers
- Privacy and Biometric Data-Governance Constraints Raise Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software held 67.33% of the authentication orchestration market share in 2025. The leading position reflects demand for programmable policy engines across different channels and authentication methods. Organizations use these platforms to select the appropriate authenticator based on the risk context, user behavior, and compliance rules. This approach moves purchasing away from a focus on individual tokens or biometric sensors. It also avoids hardware upgrades and repeated application redeployment. Software can help teams maintain consistent policy logic as identity providers and access channels change.
Services are projected to grow at a 23.71% CAGR from 2026 to 2031. Professional implementation, managed services, and specialist support are becoming important as deployments cover more identity providers, risk engines, and channel-specific authentication journeys. Buyers need help configuring authentication journeys, tuning adaptive risk thresholds, and maintaining clear governance over policy changes. They also need connectors updated as protocols change and as applications add new integration requirements. Okta expanded its orchestration capabilities in early 2026 through its Mosaic Platform SDK and Auth0 platform features for AI agents and digital credentials. These releases show why implementation expertise remains important alongside software subscriptions in the authentication orchestration market.
Cloud accounted for 59.89% of the authentication orchestration market in 2025. Cloud delivery aligns with distributed application estates and identity-as-a-service operating models. It can support authentication across multiple applications without requiring customers to maintain all the infrastructure themselves. On-premises deployment remains relevant in sovereign data environments and classified government networks. It also serves banks that need single-tenant deployments under PCI DSS and HIPAA requirements. Its relative position is narrowing as cloud-managed and self-hosted operating models become easier to manage.
Hybrid deployment is projected to grow at a 23.02% CAGR through 2031. Organizations with legacy on-premises estates and cloud-native applications cannot always quickly adopt a fully cloud-based model. They need an identity layer that issues tokens accepted by both cloud services and internal applications, governed by common policy rules. This supports modernization without requiring the legacy environment to reauthenticate against a cloud provider for every request. Microsoft added passkey profiles and Linux support for phishing-resistant multi-factor authentication credentials in its March 2026 Entra releases. These capabilities reflect ongoing vendor investment in hybrid environments and the authentication orchestration market.
Complete Report Scope:
- By Component
- Software
- Services
- By Deployment Mode
- Cloud
- On-Premises
- Hybrid
- By Organization Size
- Large Enterprises
- Small and Medium-Sized Enterprises
- By Industry Vertical
- Government and Public Administration
- Retail and E-Commerce
- Transportation and Logistics
- Energy and Utilities
- IT and Telecommunication
- Media and Entertainment
- Healthcare and Life Sciences
- Banking, Financial Services, and Insurance (BFSI)
- Other Industry Verticals
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- BENELUX
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 35.16% of the authentication orchestration market share in 2025. The region combines extensive enterprise security budgets, active regulation, and a concentrated vendor base. U.S. federal zero-trust requirements have supported procurement of phishing-resistant multi-factor authentication across agencies and contractor networks. NIST SP 800-63-4 sets a current digital identity framework for federal systems and regulated private organizations. Microsoft required multi-factor authentication for Azure sign-ins across tenants, with extended compliance deadlines continuing through July 2026.
Europe is the second-largest regional market in the authentication orchestration market. NIS2, DORA, and eIDAS 2.0 create parallel compliance requirements across financial services, healthcare, and large digital platforms. All 27 European Union member states must provide a European Digital Identity Wallet by December 2026. The FIDO Alliance stated in September 2025 that a FIDO passkey enrolled in an EUDI Wallet can meet relying-party authentication requirements at high eIDAS assurance levels. Germany, the United Kingdom, France, and the Benelux countries lead regional procurement. The NCSC recommendation for passkeys provides buyers with a clearer, government-aligned reference point. South America remains earlier in adoption, with Brazil and Argentina showing demand from larger financial institutions.
Asia-Pacific is projected to grow at a 22.67% CAGR through 2031. India's Unified Payments Interface logged 102 billion authentication calls in 2025, adding scale and complexity to the authentication infrastructure. Razorpay launched a Reserve Bank of India-compliant biometric passkey solution with Mastercard in March 2026 for online card transactions. Fujitsu deployed its FIDO2 passkey service for SMBC Nikko Securities in February 2026 for online trading. The Middle East is also becoming more active, following the Central Bank of Jordan's selection of BIO-key International for a national biometric authentication initiative in July 2026. These programs extend the authentication orchestration market beyond its established North American and European base.
- Okta, Inc.
- Microsoft Corporation
- Ping Identity Corporation
- IBM Corporation
- Transmit Security, Inc.
- Cisco Systems, Inc.
- Thales
- CyberArk Software Ltd.
- RSA Security LLC
- ForgeRock, Inc.
- Entrust Corporation
- OneSpan Inc.
- HID Global Corporation
- Yubico AB
- SecureAuth Corporation
- OneLogin, Inc.
- Descope, Inc.
- Stytch, Inc.
- Strata Identity, Inc.
- Monokee S.r.l.
- Cross Identity
- Authsignal Limited
- Veriff OU
- BioCatch Ltd.
- IDEMIA Identity and Security France S.A.S.
- NEC Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Identity-Centric Zero-Trust Adoption
- 4.2.2 Regulatory Push for Phishing-Resistant Authentication
- 4.2.3 Cloud and Hybrid Identity-Stack Complexity
- 4.2.4 Account-Takeover and Transaction-Fraud Escalation
- 4.2.5 AI-Agent Identity Journeys and Non-Human Access
- 4.2.6 Authentication Policy Portability Across Identity Providers
- 4.3 Market Restraints
- 4.3.1 Legacy Application and Protocol Integration Cost
- 4.3.2 Privacy and Biometric Data-Governance Constraints
- 4.3.3 Passkey Recovery and Credential-Lifecycle Gaps
- 4.3.4 Risk-Model Explainability and False-Positive Exposure
- 4.4 Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Use Cases
- 4.8.1 Customer Login and Registration Modernization
- 4.8.2 Passwordless Authentication and Passkey Adoption
- 4.8.3 Workforce Access and Single Sign-On (SSO) Transformation
- 4.8.4 Multi-Factor Authentication (MFA) Orchestration Across Channels
- 4.8.5 Adaptive and Risk-Based Authentication for Fraud Prevention
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Threat of Substitutes
- 4.9.2 Bargaining Power of Buyers
- 4.9.3 Bargaining Power of Suppliers
- 4.9.4 Threat of New Entrants
- 4.9.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 Cloud
- 5.2.2 On-Premises
- 5.2.3 Hybrid
- 5.3 By Organization Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium-Sized Enterprises
- 5.4 By Industry Vertical
- 5.4.1 Government and Public Administration
- 5.4.2 Retail and E-Commerce
- 5.4.3 Transportation and Logistics
- 5.4.4 Energy and Utilities
- 5.4.5 IT and Telecommunication
- 5.4.6 Media and Entertainment
- 5.4.7 Healthcare and Life Sciences
- 5.4.8 Banking, Financial Services, and Insurance (BFSI)
- 5.4.9 Other Industry Verticals
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 BENELUX
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Okta, Inc.
- 6.4.2 Microsoft Corporation
- 6.4.3 Ping Identity Corporation
- 6.4.4 IBM Corporation
- 6.4.5 Transmit Security, Inc.
- 6.4.6 Cisco Systems, Inc.
- 6.4.7 Thales
- 6.4.8 CyberArk Software Ltd.
- 6.4.9 RSA Security LLC
- 6.4.10 ForgeRock, Inc.
- 6.4.11 Entrust Corporation
- 6.4.12 OneSpan Inc.
- 6.4.13 HID Global Corporation
- 6.4.14 Yubico AB
- 6.4.15 SecureAuth Corporation
- 6.4.16 OneLogin, Inc.
- 6.4.17 Descope, Inc.
- 6.4.18 Stytch, Inc.
- 6.4.19 Strata Identity, Inc.
- 6.4.20 Monokee S.r.l.
- 6.4.21 Cross Identity
- 6.4.22 Authsignal Limited
- 6.4.23 Veriff OU
- 6.4.24 BioCatch Ltd.
- 6.4.25 IDEMIA Identity and Security France S.A.S.
- 6.4.26 NEC Corporation
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-Space and Unmet-Need Assessment

