PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2157014

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2157014
Water-Soluble Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
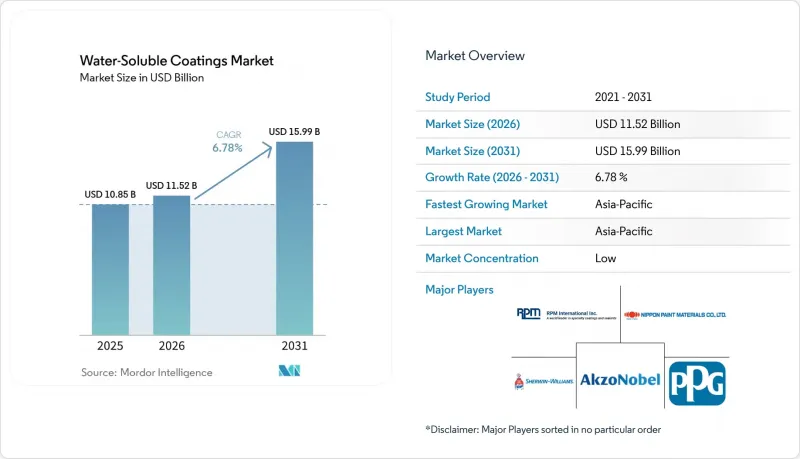
According to Mordor Intelligence, the water-soluble coatings market size was valued at USD 10.85 billion in 2025 and is estimated to grow from USD 11.52 billion in 2026 to USD 15.99 billion by 2031, at a CAGR of 6.78% during the forecast period (2026-2031).
Global Water-Soluble Coatings Market Trends and Insights
Tightening VOC and Indoor-Air-Quality Requirements
Volatile organic compound (VOC) regulation is becoming a stronger basis for product selection in the water-soluble coatings market. The U.S. Environmental Protection Agency updated national architectural coatings standards in January 2025. California's South Coast Air Quality Management District (SCAQMD) Rule 1113 limits most architectural categories to less than 50 g/L VOC. These measures favor waterborne systems where manufacturers need dependable compliance. Research published by the Royal Society of Chemistry (RSC) showed that UK decorative paint VOC emissions fell from 0.532 kg per person per year in 2004 to 0.210 kg per person per year in 2019 following the implementation of the EU Paints Directive. China's GB/T 41659-2025 standard extends this regulatory direction into a major manufacturing economy.
Architectural Repainting and Green-Building Activity
Green building programs are increasing demand for low-emission materials across construction and renovation work. LEED operates across more than 180 countries and applies requirements for indoor environmental quality. The Building Research Establishment Environmental Assessment Method (BREEAM) also supports lower-emission material specifications across many construction projects. The water-soluble coatings market benefits when low VOC requirements are included in original construction contracts. These specifications can continue to influence repainting and refurbishment decisions during a building's operating life. India's Green Rating for Integrated Habitat Assessment (GRIHA) program and Singapore's Green Mark scheme also support waterborne specifications in construction procurement.
Longer Drying and Cure Sensitivity to Humidity and Temperature
Water-based systems require controlled conditions for reliable film formation. High humidity or low temperatures can extend drying times compared with solvent-borne alternatives. Humidity above 80% can impair film quality without climate-controlled application booths, adding capital costs for smaller fabricators and regional contractors. Two-component waterborne polyurethane systems can also have shorter pot life under elevated humidity. Fast-drying additives, water-release resins, and infrared curing can mitigate these issues, but add to overall costs.
Other drivers and restraints analyzed in the detailed report include:
- Automotive OEM and Refinish Conversion to Water-Based Systems
- Performance Gains in Acrylic, Polyurethane, Epoxy, and Hybrid Systems
- Raw-Material and Additive Cost Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Acrylic accounted for 38.11% of the water-soluble coatings market in 2025, supported by its established use in interior and exterior architectural coatings. Contractors widely recognize these formulations, and their cost position supports use across large building projects. China's interior and exterior wall coatings category reached 99% waterborne penetration in 2025, reflecting years of regulatory pressure and customer acceptance for water-based architectural products. Alkyd systems continue to serve wood trim applications that require film hardness. Epoxy systems address direct-to-metal and heavy-duty flooring requirements. Fluoropolymer systems support durable facade and cool-roof applications. Formaldehyde-based systems retain narrow roles in paper and textile coatings, although increasing enforcement of the Registration, Evaluation, Authorization and Restriction of Chemicals (REACH) in Europe is driving pressure to substitute.
Polyurethane grew at a 7.23% CAGR through 2031 within the water-soluble coatings market. Demand came from wood flooring, furniture manufacturing, and automotive refinishing, which required greater mechanical performance. Double-crosslinked waterborne polyurethane exhibited tensile strength, hardness, and adhesion performance comparable to those of conventional solvent-borne two-component (2K) products. Polyurethane-acrylic combinations balanced performance requirements with cost considerations. Lubrizol's July 2025 launch of Sancure 942 illustrated the move toward broader commercial use of specialty polyurethane dispersions. These formulations were used for residential and commercial wood-floor finishes, reducing the performance gap that had previously restricted waterborne use in premium applications. The water-soluble coatings market, therefore, expanded its offering beyond standard architectural paint.
Complete Report Scope:
- By Coating Type
- Acrylic
- Polyurethane
- Alkyd
- Epoxy
- Fluoropolymers
- Formaldehyde-Based Systems
- Other Types
- By End-User Industry
- Construction and Infrastructure
- Automotive and Transportation
- Furniture, Flooring and Wood Products
- Electronics and Appliances
- Packaging
- Marine and Offshore
- Aerospace and Defense
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 39.73% of the water-soluble coatings market in 2025 and is forecast to expand at a 7.48% CAGR through 2031. China supports regional demand through urban housing, manufacturing scale, and successive VOC reforms. The penetration of water-based wall coatings reflects the extent of conversion in architectural applications. Japan and South Korea contribute to the demand for high-specification industrial coatings. ASEAN countries offer further growth through construction and vehicle assembly. The region combines large existing output with growing requirements for compliant formulations.
North America holds the second-largest position in the water-soluble coatings market. California's South Coast Air Quality Management District (SCAQMD) Rule 1113 limits most architectural categories to less than 50 g/L VOC. Federal architectural-coatings requirements and state-level standards reinforce this regulatory foundation. Institutional and commercial construction supports steady demand for compliant coating products. Canada's sustainable building activity is aligned with LEED v4.1 and is transitioning to LEED v5. Mexico also benefits from nearshoring investment in automotive assembly and electronics manufacturing.
Europe is a mature market with high waterborne penetration across decorative coatings. The EU Paints Directive and REACH requirements established regional harmonization ahead of many other markets. Germany, the United Kingdom, and France have largely completed decorative-paint conversion. Growth is concentrated in maintenance, facade protection, industrial applications, and specialty products. South America, the Middle East, and Africa are smaller but increasingly relevant markets. Brazil's construction and automotive assembly support demand, although humid conditions can present challenges for film formation. The UAE's Estidama Pearl Rating System and Saudi Arabia's Vision 2030 projects are driving the adoption of low-VOC specifications in commercial and industrial procurement.
- Akzo Nobel N.V.
- Arkema
- Asian Paints Limited
- Axalta Coating Systems
- Berger Paints
- Covestro AG
- Hempel
- Jotun
- Kansai Paint Co., Ltd.
- Nippon Paint Holdings Co., Ltd.
- PPG Industries, Inc.
- RPM International Inc.
- Teknos Group
- The Sherwin-Williams Company
- Tikkurila
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Tightening VOC and Indoor-Air-Quality Requirements
- 4.2.2 Architectural Repainting and Green-Building Activity
- 4.2.3 Automotive OEM and Refinish Conversion to Water-Based Systems
- 4.2.4 Performance Gains in Acrylic, Polyurethane, Epoxy and Hybrid Systems
- 4.2.5 Under-Served Demand for Low-Odor Coatings in Occupied Facilities
- 4.3 Market Restraints
- 4.3.1 Longer Drying and Cure Sensitivity to Humidity and Temperature
- 4.3.2 Raw-Material and Additive Cost Volatility
- 4.3.3 Water Sensitivity, Substrate Preparation and Corrosion-Protection Gaps
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size And Growth Forecasts (Value)
- 5.1 By Coating Type
- 5.1.1 Acrylic
- 5.1.2 Polyurethane
- 5.1.3 Alkyd
- 5.1.4 Epoxy
- 5.1.5 Fluoropolymers
- 5.1.6 Formaldehyde-Based Systems
- 5.1.7 Other Types
- 5.2 By End-User Industry
- 5.2.1 Construction and Infrastructure
- 5.2.2 Automotive and Transportation
- 5.2.3 Furniture, Flooring and Wood Products
- 5.2.4 Electronics and Appliances
- 5.2.5 Packaging
- 5.2.6 Marine and Offshore
- 5.2.7 Aerospace and Defense
- 5.2.8 Others
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 NORDIC Countries
- 5.3.3.6 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Akzo Nobel N.V.
- 6.4.2 Arkema
- 6.4.3 Asian Paints Limited
- 6.4.4 Axalta Coating Systems
- 6.4.5 Berger Paints
- 6.4.6 Covestro AG
- 6.4.7 Hempel
- 6.4.8 Jotun
- 6.4.9 Kansai Paint Co., Ltd.
- 6.4.10 Nippon Paint Holdings Co., Ltd.
- 6.4.11 PPG Industries, Inc.
- 6.4.12 RPM International Inc.
- 6.4.13 Teknos Group
- 6.4.14 The Sherwin-Williams Company
- 6.4.15 Tikkurila
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

