PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2157053

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2157053
Industrial Tires - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
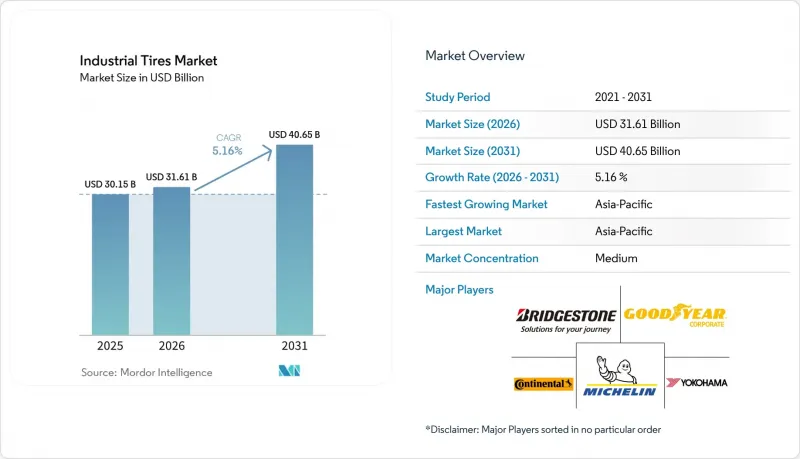
According to Mordor Intelligence, the industrial tires market size was valued at USD 30.15 billion in 2025 and is estimated to grow from USD 31.61 billion in 2026 to reach USD 40.65 billion by 2031, at a CAGR of 5.16% during the forecast period (2026-2031).
Global Industrial Tires Market Trends and Insights
Infrastructure and Construction Equipment Investment
Government-backed infrastructure programs increase equipment utilization and support tire consumption in the industrial tires market across construction, quarrying, and road-building activities. India allocated USD 34.8 billion to the Ministry of Road Transport and Highways for fiscal year 2026-27, an 8% increase from the prior year. The ministry completed 5,313 km of national highways in fiscal year 2025-26, exceeding its target by 15%. Large programs give contractors greater confidence in maintaining active equipment fleets and support demand across original equipment and aftermarket channels. Data-center construction also increases demand for earthmovers and loaders, particularly at remote, land-intensive sites in North America and the Asia-Pacific. This work requires excavation, grading, and aggregate handling before a facility becomes operational, increasing the operating hours of tires used at the site. Quarry activity can therefore sustain off-the-road tire use even when residential and commercial construction remains constrained by financing costs.
Mining Fleet Expansion for Critical Minerals
Demand for copper, lithium, cobalt, and nickel supports a longer investment cycle for mining fleets and the industrial tires market. The International Energy Agency projects that demand for these minerals could double by 2030 under its Stated Policies Scenario and triple under its Net Zero Emissions by 2050 Scenario. Mine development requires investment in haul trucks, loaders, and support equipment before production output can rise. Harder rock and deeper excavation increase tire wear as accessible surface deposits are depleted over time. This raises tire consumption per machine-hour and increases the importance of a dependable supply of replacements at operating sites. BHP maintained capital expenditure guidance of USD 11 billion for each of fiscal years 2026 and 2027, with copper operations central to its program. In April 2025, Sailun's Maxam brand secured a 5-year agreement to supply tire solutions for Rio Tinto's 230-ton mining trucks at the Simandou project in Guinea.
Volatile Natural Rubber and Reinforcement Material Costs
Natural rubber supply responds slowly to demand because productive trees require long planting and maturation cycles. More than 40% of global rubber plantations consisted of trees older than 30 years, according to the Association of Natural Rubber Producing Countries. Older plantations limit supply responsiveness even when pricing makes additional production economically attractive. The association estimated natural rubber production growth of 0.5% in 2026, below demand growth of 1.3%, producing a 400,000-ton supply deficit. Higher oil prices can also increase synthetic rubber costs and reduce the scope for material substitution. Tire price increases can lag input-cost increases by 6 to 12 months, placing greater pressure on smaller and less integrated producers. These conditions can extend replacement decisions among price-sensitive fleet operators in the industrial tires market.
Other drivers and restraints analyzed in the detailed report include:
- Warehouse Automation and Material-Handling Intensification
- Agricultural Mechanization in Emerging Economies
- High Replacement Cost and Extended Premium-Tier Service Life
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Radial tires held 58.13% of the industrial tires market share in 2025 and are forecast to grow at a 5.84% CAGR through 2031. This reflects a long-running shift away from bias-ply construction across mining, construction, and material-handling fleets operating in demanding conditions. Radial designs offer lower fuel consumption, longer carcass life, and better heat dissipation than bias alternatives, which is significant as equipment operating hours and fuel costs remain elevated. The radial category is both the largest and fastest-growing tire type, combining established fleet use with a continuing shift in purchasing preferences.
Bias-ply tires remain relevant where rugged performance at low speeds and under high impact is more important than fuel efficiency, including in some underground mining settings and on heavy loaders operating on rough terrain. Solid tires are gaining use in enclosed warehouses, as eliminating puncture risk can outweigh the ride-comfort trade-off for vehicles operating on predictable indoor surfaces. Belted-bias tires retain a narrower role in agricultural and construction applications where rim sizes limit radial fitment, and operators require greater load-carrying capability. Electric off-highway machines deliver immediate torque from a standstill and increase bead and sidewall stresses, creating distinct design requirements for tire suppliers. In December 2025, Guizhou Tire Co., Ltd. launched its Dianqing electric-drive Off-The-Road (OTR) series, featuring reinforced carcass construction and heat-dissipating tread compounds for high-torque equipment.
Complete Report Scope:
- By Tire Type
- Radial Tires
- Bias Tires
- Belted-Bias Tires
- Solid Tires
- Others
- By Application
- Construction
- Mining
- Material Handling
- Agriculture
- Other Applications
- By Vehicle Type
- Earthmovers
- Loaders and Dozers
- Tractors
- Forklifts
- Other Vehicle Types
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 38.68% of the industrial tires market in 2025 and is forecast to grow at a 6.06% CAGR through 2031. China remains a major producer and consumer of construction equipment, while India and Southeast Asia are increasingly central to regional demand growth. India's USD 34.8 billion road transport budget for fiscal year 2026-27 and its active highway program support demand for construction and earthmover tires. Indonesia, Vietnam, and the Philippines combine infrastructure investment with rising agricultural mechanization, creating demand across several tire applications.
North America's industrial tires market is more heavily dependent on replacement demand and value-focused purchasing. Public infrastructure funding, data-center development, and energy-transition projects support construction tire demand beyond housing activity. The U.S. critical-minerals initiative supports possible fleet expansion for lithium and rare-earth extraction in Nevada, Arizona, and Alaska. Europe's consumption reflects equipment renewal linked to industrial decarbonization and Stage V non-road emissions standards. Germany, France, and the Nordic countries show demand for tire pressure monitoring and predictive maintenance services, supporting premium pricing.
The Middle East and Africa combine construction-led and mining-led demand patterns. Saudi Arabia and the United Arab Emirates drive equipment demand through urban projects and Vision 2030 programs. South Africa, the Democratic Republic of the Congo, Zambia, and Ghana support mining tire demand through metals extraction. In September 2026, Ascenso introduced an all-steel radial OTR range at Electra Mining Africa in South Africa. Argentina's lithium areas and Chile's copper belt add fleet demand, while remote mines require reliable regional tire delivery programs.
- APOLLO TYRES LTD
- Balkrishna Industries Limited (BKT)
- Bridgestone Corporation
- CEAT Limited
- Continental AG
- Hankook Tire & Technology
- JK Tyre & Industries Ltd.
- Michelin
- MRF Tyres
- Nokian Tyres plc
- Pirelli & C. S.p.A.
- Sumitomo Rubber Industries, Ltd.
- The Goodyear Tire & Rubber Company
- THE YOKOHAMA RUBBER CO., LTD.
- Titan International, Inc.
- Trelleborg Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Infrastructure and Construction Equipment Investment
- 4.2.2 Mining Fleet Expansion for Critical Minerals
- 4.2.3 Warehouse Automation and Material-Handling Intensification
- 4.2.4 Agricultural Mechanization in Emerging Economies
- 4.2.5 Electrification-Driven Tire Redesign for Off-Highway Equipment
- 4.3 Market Restraints
- 4.3.1 Volatile Natural Rubber and Reinforcement Material Costs
- 4.3.2 High Replacement Cost and Extended Premium-Tire Service Life
- 4.3.3 Low-Cost and Counterfeit Tire Competition
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size And Growth Forecasts (Value)
- 5.1 By Tire Type
- 5.1.1 Radial Tires
- 5.1.2 Bias Tires
- 5.1.3 Belted-Bias Tires
- 5.1.4 Solid Tires
- 5.1.5 Others
- 5.2 By Application
- 5.2.1 Construction
- 5.2.2 Mining
- 5.2.3 Material Handling
- 5.2.4 Agriculture
- 5.2.5 Other Applications
- 5.3 By Vehicle Type
- 5.3.1 Earthmovers
- 5.3.2 Loaders and Dozers
- 5.3.3 Tractors
- 5.3.4 Forklifts
- 5.3.5 Other Vehicle Types
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 APOLLO TYRES LTD
- 6.4.2 Balkrishna Industries Limited (BKT)
- 6.4.3 Bridgestone Corporation
- 6.4.4 CEAT Limited
- 6.4.5 Continental AG
- 6.4.6 Hankook Tire & Technology
- 6.4.7 JK Tyre & Industries Ltd.
- 6.4.8 Michelin
- 6.4.9 MRF Tyres
- 6.4.10 Nokian Tyres plc
- 6.4.11 Pirelli & C. S.p.A.
- 6.4.12 Sumitomo Rubber Industries, Ltd.
- 6.4.13 The Goodyear Tire & Rubber Company
- 6.4.14 THE YOKOHAMA RUBBER CO., LTD.
- 6.4.15 Titan International, Inc.
- 6.4.16 Trelleborg Group
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

