PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2157058

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2157058
Plastic Pressure Pipes - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the plastic pressure pipes market size was valued at USD 17.34 billion in 2025 and is estimated to grow from USD 18.28 billion in 2026 to reach USD 23.81 billion by 2031, at a CAGR of 5.43% during the forecast period (2026-2031).
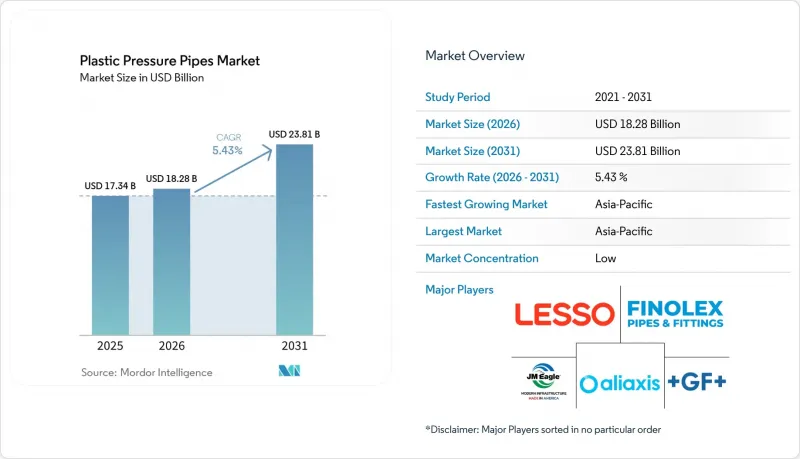
Global Plastic Pressure Pipes Market Trends and Insights
Aging Water and Wastewater Networks Requiring Pressure-Pipe Replacement
The plastic pressure pipes market benefits when utilities replace aging water and wastewater infrastructure. The U.S. Environmental Protection Agency finalized requirements in October 2024 for drinking water systems to identify and replace lead service lines within 10 years. Federal funding of USD 15 billion supports the lead service line transition under the Bipartisan Infrastructure Law. This turns a portion of deferred maintenance into a compliance-led procurement cycle for High-Density Polyethylene (HDPE) and PVC-O pipe producers. Rehabilitation specifications also increasingly favor trenchless-compatible grades such as PE100-RC, which can increase revenue per installed meter. American Water Works Association (AWWA) and ISO standards, the 2024 U.S. EPA Lead and Copper Rule revision, and the EU Urban Wastewater Treatment Directive influence public-project specifications and material selection.
Expansion of Efficient Irrigation and Water-Conservation Infrastructure
Efficient irrigation is widening the addressable demand base for the plastic pressure pipes market in water-scarce regions. China issued Guobiao (GB/T) 19796.1-2025 for polyethylene pressure-pipe agricultural irrigation saddles, with implementation effective in May 2026. India's PM Krishi Sinchayee Yojana operates alongside Jal Jeevan Mission 2.0 and supports certified uPVC pipe procurement for farm distribution. The Vinyl Institute reported PVC delivery efficiency of 89%-99%, compared with 60%-65% for earthen canals, which supports the use of pressurized systems in irrigation projects. Molecor's TR6 is a PN6-oriented PVC irrigation pipe certified under UNE-EN 17176 and ISO 16422, with 15% higher stiffness than conventional PVC-U PN6. These requirements support products that use less material while meeting farm-water distribution needs.
Polymer and Additive Price Volatility
Polymer and additive price changes restrain the plastic pressure pipes market because resin is a major input cost. The U.S. Producer Price Index for plastics pipe and pipe fitting manufacturing stood at 418.1 in July 2026. The index reflects continued exposure to ethylene and PVC monomer cost cycles. Price movements affect manufacturers, contractors, and public-project budgets at the same time. A stable resin environment allows producers to plan capacity and bid on longer infrastructure programs with greater certainty. India imposed a minimum import price on PVC resin in July 2026, showing that resin price instability can also prompt policy action.
Other drivers and restraints analyzed in the detailed report include:
- Corrosion Resistance and Lower Installed Cost Versus Metallic Alternatives
- Trenchless Rehabilitation Enabled by Flexible PE and Fusion-Jointed Systems
- Fragmented Certification and Pressure-Rating Requirements Across Countries
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PVC held 48.67% of the plastic pressure pipes market in 2025. Its position reflects lower resin cost, an established contractor skill base, and compatibility with existing fittings used in water distribution and agricultural systems. PVC-O is gaining use in large-diameter municipal mains because its hydrostatic design basis is 7,100 psi, compared with 4,000 psi for conventional PVC. The higher rating permits thinner walls at comparable pressure levels and can reduce material use and installation weight. Polypropylene (PP) and other materials serve specialized higher-temperature industrial and chemical applications where PVC has operating limitations.
PE is projected to advance at a 6.24% CAGR through 2031. It supports trenchless rehabilitation, large-diameter fusion-welded water transmission, and agricultural drip systems. CHINA LESSO reported expanded specialized agricultural piping into Africa and Southeast Asia in the first half of 2026. The company also reported high-performance composite piping research and several associated patents during that period. Material selection, therefore, reflects the required pressure performance, installation method, temperature exposure, and expected service conditions.
Complete Report Scope:
- By Material
- Polyvinyl Chloride (PVC)
- Polyethylene (PE)
- Polypropylene (PP)
- Other Materials
- By End-User Industry
- Water and Wastewater Treatment
- Building and Construction
- Agriculture
- Oil and Gas
- Mining
- Industrial
- Other End-User Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 45.06% of the plastic pressure pipes market in 2025 and is projected to advance at a 6.39% CAGR through 2031. China and India are supported by municipal water, rural distribution, and agricultural-irrigation programs. JJM 2.0 gives India a long-term rural water procurement program through December 2028. China's GB/T 19796.1-2025 standard has applied to PE agricultural irrigation saddles since May 2026. Japan and South Korea provide replacement demand shaped by mature networks and high-quality requirements. Southeast Asia and South Asia add demand through urban expansion and water-network development.
In North America and Europe, demand is weighted toward rehabilitation, including PE100-RC and PVC-O grades that meet municipal and industrial specifications. The U.S. lead service line rule creates a defined replacement obligation over 10 years. ISO 11300-1:2026 provides a technical basis for PE use in trenchless renewal of underground water networks. European regulatory requirements influence the selection of EN 12201 PE and PVC-O in urban renewal projects. The United Kingdom also has a sustained water infrastructure investment program, which supports domestic demand for pressure pipe producers.
South America and the Middle East and Africa are emerging growth areas in the plastic pressure pipes market. GF Industry and Infrastructure Flow Solutions signed a CHF 100 million (approximately USD 126.5 million) contract with SABESP in April 2026 to modernize water distribution networks in 375 municipalities in Sao Paulo state. Saudi Arabia's water strategy targets more than 10,000 km of new water transmission infrastructure by 2030 and includes USD 30 billion of investment. CHINA LESSO inaugurated an Ethiopian production base in May 2025, while Polyfab Plastic Middle East FZC supplies several African markets through its export network. These regions combine water scarcity, infrastructure needs, and export-oriented supplier activity.
- Aliaxis Holdings SA
- APL Apollo
- ASTRAL PIPES
- CHINA LESSO
- Finolex Industries Limited
- GF Industry and Infrastructure Flow Solutions
- JM EAGLE, INC.
- KPT Piping System
- LUNA PLAST a.s. na EDB
- Martoni Group
- Molecor
- P&F Global
- Polyfab Plastic Middle East FZC
- Supreme
- TRUFLO
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging Water and Wastewater Networks Requiring Pressure-Pipe Replacement
- 4.2.2 Expansion of Efficient Irrigation and Water-Conservation Infrastructure
- 4.2.3 Corrosion Resistance and Lower Installed Cost Versus Metallic Alternatives
- 4.2.4 Trenchless Rehabilitation Enabled by Flexible PE and Fusion-Jointed Systems
- 4.2.5 Digital Leak Detection and Asset-Monitoring Compatibility of New Pipe Networks
- 4.3 Market Restraints
- 4.3.1 Polymer and Additive Price Volatility
- 4.3.2 Fragmented Certification and Pressure-Rating Requirements Across Countries
- 4.3.3 Limited Availability of Verified Recycled Resin for Pressure Applications
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Material
- 5.1.1 Polyvinyl Chloride (PVC)
- 5.1.2 Polyethylene (PE)
- 5.1.3 Polypropylene (PP)
- 5.1.4 Other Materials
- 5.2 By End-User Industry
- 5.2.1 Water and Wastewater Treatment
- 5.2.2 Building and Construction
- 5.2.3 Agriculture
- 5.2.4 Oil and Gas
- 5.2.5 Mining
- 5.2.6 Industrial
- 5.2.7 Other End-User Industries
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Aliaxis Holdings SA
- 6.4.2 APL Apollo
- 6.4.3 ASTRAL PIPES
- 6.4.4 CHINA LESSO
- 6.4.5 Finolex Industries Limited
- 6.4.6 GF Industry and Infrastructure Flow Solutions
- 6.4.7 JM EAGLE, INC.
- 6.4.8 KPT Piping System
- 6.4.9 LUNA PLAST a.s. na EDB
- 6.4.10 Martoni Group
- 6.4.11 Molecor
- 6.4.12 P&F Global
- 6.4.13 Polyfab Plastic Middle East FZC
- 6.4.14 Supreme
- 6.4.15 TRUFLO
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

