PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2157064

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2157064
North America Hydraulic Presses - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
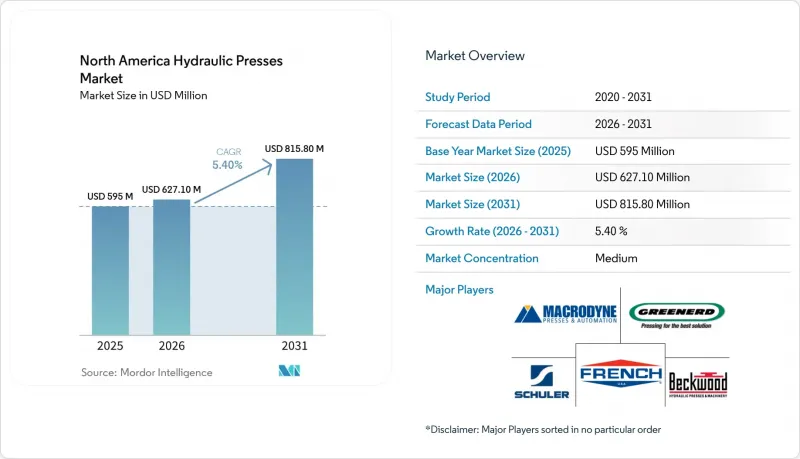
According to Mordor Intelligence, the North America hydraulic presses market size was valued at USD 595 million in 2025 and is estimated to grow from USD 627.10 million in 2026 to reach USD 815.80 million by 2031, at a CAGR of 5.40% during the forecast period (2026-2031).
North America Hydraulic Presses Market Trends and Insights
Automotive Lightweighting and Advanced Material Forming
The North America hydraulic presses market benefits from vehicle programs that use aluminum, ultra-high-strength steel, and other materials in body structures and battery systems. Battery trays, side sills, and crash-management parts need controlled force and dwell time during forming. Novelis stated that aluminum battery enclosures can reduce weight by up to 50% compared with equivalent steel designs and improve energy density by 30% per unit. Hydraulic systems can use programmed ram speed, full-stroke tonnage, and controlled dwell to support these requirements. Tier 1 and Tier 2 suppliers in Michigan, Ontario, and Coahuila are updating older lines to process 1,200 MPa advanced high-strength steel grades. The North America hydraulic presses market, therefore, faces specifications that increasingly involve battery-pack engineers as well as press-shop tooling teams, which can extend procurement while raising equipment requirements.
Reshoring and Domestic Manufacturing Capacity Expansion
New factory investment is increasing the need for forming equipment in North American production locations. The Reshoring Initiative reported that 63% of surveyed original equipment manufacturers planned United States capital expenditure in 2026 or 2027 for reshoring or domestic expansion. John Deere announced a USD 70 million excavator factory in Kernersville, North Carolina, within a USD 20 billion United States manufacturing commitment over 10 years. Contract manufacturers that supply expanding original equipment manufacturers may need press capacity before final vehicle or equipment production reaches scale. This sequence makes new plant plans relevant to the North America hydraulic presses market before equipment orders are placed. It also supports demand for H-frame and four-column systems used in structural stamping and forging lines.
High Initial Investment and Long Equipment Payback
High capital requirements can limit purchases by small and medium-sized fabricators. Custom high-tonnage systems that include automation, tooling, and installation can require multi-million-dollar commitments and payback periods of 7 to 12 years. NIST identified capital-cost predictability and equipment payback horizons as important competitiveness constraints for United States manufacturers. Staffing concerns can compound this issue when a buyer cannot secure operators and maintenance personnel for a new line. Leasing, pay-per-part arrangements, and public equipment financing can reduce the initial barrier, although their use remains limited in many mid-sized businesses. The North America hydraulic presses market can therefore have a strong project pipeline, while some planned investments take longer to become firm orders.
Other drivers and restraints analyzed in the detailed report include:
- Automation, Robotics, and Smart-Press Integration
- Demand for High-Force Forming in Aerospace and Defense
- Hydraulic Component, Steel, and Energy Cost Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
H-Frame and Straight-Side presses held 48% of the North America hydraulic presses market share in 2025. Their gib-guided ram architecture helps maintain parallelism under eccentric loading. This makes the configuration suitable for high-volume automotive stamping and aerospace structural parts that need consistent dimensions. ANDRITZ Schuler launched the HFA plus+ fineblanking press series in January 2026, with force ratings from 3,200 to 15,500 kN and a servo-controlled hydraulic-pump drive. The company stated that the new drive provides double-digit energy-efficiency improvements. H-frame scale also makes rebuilds and control upgrades more economical over longer equipment lifecycles.
C-Frame and Gap-Frame presses represent the fastest-growing configuration, with an 8.2% CAGR from 2026 to 2031. Their open-throat design provides access from 3 sides, which supports manual work and robot-loaded manufacturing cells. The smaller footprint can suit electronics, medical-device, and small-batch automotive supplier facilities. Battery-cell component assembly, connector staking, and sensor-housing forming are adding demand for C-frame presses in the 20 to 150 ton range. Four-Post and Two-Post configurations remain relevant for composite molding, powder compaction, and rubber forming. Benchtop presses serve research and prototype work, while specialized systems cover isothermal and superplastic aerospace forming.
The 101-500 ton class accounted for 48.3% of segment revenue in 2025. This capacity range serves sheet-metal stamping, deep drawing, bending, and general fabrication. It can handle many aluminum and advanced high-strength steel applications used by automotive Tier 1 and Tier 2 suppliers. The range is a common specification for new stamping lines across the North America hydraulic presses market. Domestic builders and European integrators both offer equipment in this range, which keeps competition active and prices relatively transparent. Its broad customer base helps stabilize demand even when a single end-use sector slows.
Presses above 2,000 tons are the fastest-growing tonnage segment, with a forecast 6.8% CAGR through 2031. Aerospace and defense customers use these systems for large titanium and aluminum structures formed in a single cycle. This approach can reduce fastener counts and assembly time on airframes and naval platforms. Programs for fighter aircraft, shipbuilding, and hypersonic systems support requirements from 2,000 to 30,000 tons. The 501-1,000 ton and 1,001-2,000 ton classes support forging and heavy structural forming. Presses up to 100 tons remain useful for bench assembly, coining, and low-volume prototype work, while safety requirements influence commissioning and installation costs across every force class.
Complete Report Scope:
- By Frame / Structural Configuration
- C-Frame / Gap-Frame Hydraulic Presses
- H-Frame / Straight-Side / Gib-Guided Hydraulic Presses
- Four-Post / Four-Column Hydraulic Presses
- Two-Post / Column Hydraulic Presses
- Benchtop / Workshop Hydraulic Presses
- Other Specialized Hydraulic Press Configurations
- By Tonnage / Press Force
- Up to 100 Tons
- 101-500 Tons
- 501-1,000 Tons
- 1,001-2,000 Tons
- Above 2,000 Tons
- By Application / Forming Process
- Sheet Metal Forming and Deep Drawing
- Forging
- Bending and Straightening
- Punching, Blanking, and Coining
- Compression Molding
- Powder Compaction
- Hydroforming
- Assembly, Press-Fitting, and General Pressing
- Other Specialized Applications
- By End-Use Industry
- Automotive and Transportation
- Aerospace and Defense
- Industrial Machinery and General Manufacturing
- Electrical and Electronics
- Plastics, Rubber, and Composites
- Construction and Heavy Equipment
- Energy and Power Equipment
- Rail and Marine
- Powder Metallurgy, Ceramics, and Advanced Materials
- Other End-Use Industries
- By Geography
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- ANDRITZ Schuler
- Macrodyne Technologies Inc.
- Beckwood Press Company
- Greenerd Press & Machine Company, Inc.
- French Oil Mill Machinery Co.
- Enerpac Tool Group Corp.
- Pacific Press Technologies
- HPM North America
- Neff Press
- Dake Corp.
- Betenbender Manufacturing, Inc.
- Multipress, Inc.
- Sutherland Presses
- Eagle Press & Equipment Co. Ltd.
- AIDA Engineering, Ltd.
- Komatsu Ltd.
- JIER Machine-Tool Group Co., Ltd.
- Fagor Arrasate
- Siempelkamp
- LASCO Umformtechnik GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.1.1 Market Drivers
- 4.1.1.1 Automotive Lightweighting and Advanced Material Forming
- 4.1.1.2 Reshoring and Domestic Manufacturing Capacity Expansion
- 4.1.1.3 Automation, Robotics, and Smart-Press Integration
- 4.1.1.4 Demand for High-Force Forming in Aerospace and Defense
- 4.1.1.5 Retrofit Demand from Installed Press Bases and Local Service Requirements
- 4.1.1.6 Energy Efficiency Mandates and Demand for Servo-Hydraulic Press Upgrades
- 4.1.2 Market Restraints
- 4.1.2.1 High Initial Investment and Long Equipment Payback
- 4.1.2.2 Hydraulic Component, Steel, and Energy Cost Volatility
- 4.1.2.3 Tariff, Trade-Policy, and Cross-Border Supply-Chain Uncertainty
- 4.1.2.4 Skilled Workforce Shortage and Technician Availability Constraints
- 4.1.1 Market Drivers
- 4.2 Value Chain and Supply Chain Analysis
- 4.2.1 Raw Materials and Structural Components
- 4.2.2 Hydraulic Power Units, Pumps, Valves, and Cylinders
- 4.2.3 Controls, Sensors and Automation Components
- 4.2.4 Tooling and Die Ecosystem
- 4.2.5 Installation, Maintenance, Retrofit, and Rebuild Services
- 4.3 Regulatory Landscape
- 4.3.1 Hydraulic Press Machinery and Occupational Safety Requirements
- 4.3.2 Hydraulic Fluid, Noise, and Environmental Compliance Requirements
- 4.3.3 Regional Machinery Safety and Conformity Requirements
- 4.4 Technological Outlook
- 4.4.1 Servo-Hydraulic and Energy-Efficient Drive Systems
- 4.4.2 Advanced Controls and Closed-Loop Force/Position Control
- 4.4.3 Automation, Robotics, and Automated Material Handling
- 4.4.4 Connected Presses, IIoT, and Condition Monitoring
- 4.4.5 Predictive Maintenance and Process Traceability
- 4.4.6 Hybrid Hydraulic-Electric Press Technologies
- 4.4.7 Advanced Material and Composite Forming Technologies
- 4.5 Impact of Geopolitical and Trade Developments
- 4.5.1 Tariffs and Import Restrictions
- 4.5.2 Supply-Chain Risks for Hydraulic and Control Components
- 4.5.3 Localization of Hydraulic Press Manufacturing
- 4.6 Industry and Manufacturing Trends
- 4.7 Sustainability and Energy Efficiency
5 Market Size & Growth Forecasts
- 5.1 By Frame / Structural Configuration
- 5.1.1 C-Frame / Gap-Frame Hydraulic Presses
- 5.1.2 H-Frame / Straight-Side / Gib-Guided Hydraulic Presses
- 5.1.3 Four-Post / Four-Column Hydraulic Presses
- 5.1.4 Two-Post / Column Hydraulic Presses
- 5.1.5 Benchtop / Workshop Hydraulic Presses
- 5.1.6 Other Specialized Hydraulic Press Configurations
- 5.2 By Tonnage / Press Force
- 5.2.1 Up to 100 Tons
- 5.2.2 101-500 Tons
- 5.2.3 501-1,000 Tons
- 5.2.4 1,001-2,000 Tons
- 5.2.5 Above 2,000 Tons
- 5.3 By Application / Forming Process
- 5.3.1 Sheet Metal Forming and Deep Drawing
- 5.3.2 Forging
- 5.3.3 Bending and Straightening
- 5.3.4 Punching, Blanking, and Coining
- 5.3.5 Compression Molding
- 5.3.6 Powder Compaction
- 5.3.7 Hydroforming
- 5.3.8 Assembly, Press-Fitting, and General Pressing
- 5.3.9 Other Specialized Applications
- 5.4 By End-Use Industry
- 5.4.1 Automotive and Transportation
- 5.4.2 Aerospace and Defense
- 5.4.3 Industrial Machinery and General Manufacturing
- 5.4.4 Electrical and Electronics
- 5.4.5 Plastics, Rubber, and Composites
- 5.4.6 Construction and Heavy Equipment
- 5.4.7 Energy and Power Equipment
- 5.4.8 Rail and Marine
- 5.4.9 Powder Metallurgy, Ceramics, and Advanced Materials
- 5.4.10 Other End-Use Industries
- 5.5 By Geography
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 Competitive Landscape
- 6.1 Strategic Moves
- 6.2 Market Share Analysis
- 6.3 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Products and Services, Recent Developments)
- 6.3.1 ANDRITZ Schuler
- 6.3.2 Macrodyne Technologies Inc.
- 6.3.3 Beckwood Press Company
- 6.3.4 Greenerd Press & Machine Company, Inc.
- 6.3.5 French Oil Mill Machinery Co.
- 6.3.6 Enerpac Tool Group Corp.
- 6.3.7 Pacific Press Technologies
- 6.3.8 HPM North America
- 6.3.9 Neff Press
- 6.3.10 Dake Corp.
- 6.3.11 Betenbender Manufacturing, Inc.
- 6.3.12 Multipress, Inc.
- 6.3.13 Sutherland Presses
- 6.3.14 Eagle Press & Equipment Co. Ltd.
- 6.3.15 AIDA Engineering, Ltd.
- 6.3.16 Komatsu Ltd.
- 6.3.17 JIER Machine-Tool Group Co., Ltd.
- 6.3.18 Fagor Arrasate
- 6.3.19 Siempelkamp
- 6.3.20 LASCO Umformtechnik GmbH
7 Market Opportunities & Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.1.1 Energy-Efficient and Servo-Hydraulic Presses
- 7.1.2 Retrofit and Modernization of Legacy Presses
- 7.1.3 Automated and Connected Hydraulic Press Systems
- 7.1.4 Emerging-Market Manufacturing Expansion
- 7.1.5 High-Tonnage Applications
- 7.1.6 Advanced Materials and Composite Forming
- 7.1.7 Replacement vs. New-Capacity Demand Outlook

