PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2163401

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2163401
Construction Equipment Finance - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the construction equipment finance market size was valued at USD 100.3 billion in 2025 and is estimated to grow from USD 104.3 billion in 2026 to reach USD 134.4 billion by 2031, at a CAGR of 5.2% during the forecast period (2026-2031).
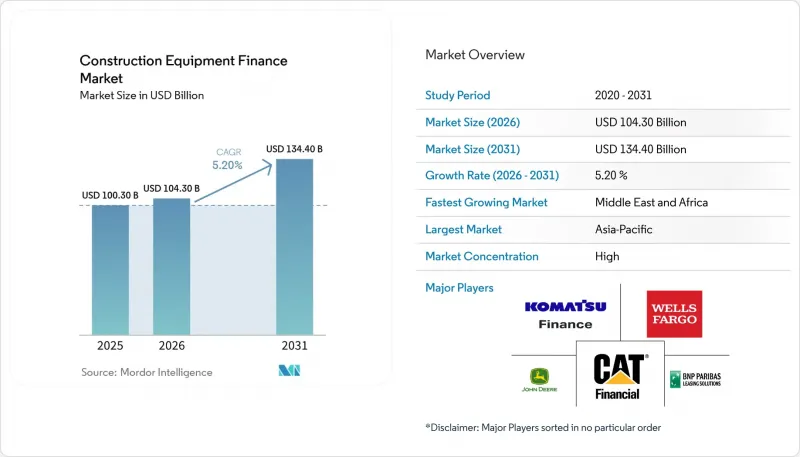
Global Construction Equipment Finance Market Trends and Insights
Infrastructure and Construction Investment Driving Equipment Acquisition
Public infrastructure commitments remain a major source of demand for the construction equipment finance market. Large public projects require machinery purchases or leases before contractors receive project revenue. The Equipment Leasing and Finance Association stated that construction machinery investment grew 3.2% annualized in the fourth quarter of 2025. It also reported a 15% year-over-year increase in March 2026, with momentum expected through at least the third quarter of 2026. Morocco front-loaded infrastructure spending equal to 11.9% of 2024 GDP for connectivity and tourism investment through 2030. Such programs create recurring financing opportunities and can support longer repayment terms when equipment works on projects backed by sovereign capital.
High Equipment Acquisition Costs and Contractor Liquidity Preservation
Higher equipment costs make cash purchases less practical for many contractors and support the use of the construction equipment finance market. The Equipment Leasing and Finance Association found that 85% of construction end users used equipment finance as their primary procurement route in 2025. This was the highest proportion among the end-user sectors tracked in the survey. Cash-flow optimization was the leading reason for financing, cited by 62% of end users. Protection from obsolescence and tax advantages followed at 55% and 51%, respectively. Larger financed ticket sizes can raise revenue per transaction even when the number of transactions grows slowly.
High Financing Costs and Contractor Credit Risk
Elevated funding costs can reduce deal conversion in the construction equipment finance market even when equipment demand remains firm. The June 2026 CapEx Finance Index reported year-to-date new business volume growth of 11.3%. The association also identified the cost of funds as the primary industry risk during the second half of 2026. Smaller contractors are especially exposed because their revenue depends on project timing and their equity buffers can be limited. Rate-sensitive borrowers may face pressure when project margins narrow. Credit-quality requirements can therefore limit originations among smaller businesses, even though this customer group creates substantial equipment demand.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Asset-Light, Flexible and Project-Aligned Equipment Access
- Expansion of OEM-Captive, Dealer and Embedded Equipment Finance
- Used-Equipment Residual-Value and Secondary-Market Liquidity Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Loans, term loans, and hire-purchase represented 53.2% of the construction equipment finance market share in 2025. These products remain familiar to lenders and provide clear ownership transfer to contractors. Larger contractors often use them to place equipment on their balance sheets. Secured loans and lines of credit together accounted for 30% of equipment acquisition financing methods, according to the Equipment Leasing and Finance Association. Finance leases and capital leases provide another route for organizations that want balance-sheet recognition while maintaining defined asset terms. Government bodies and major infrastructure contractors use these structures when procurement policy and accounting treatment require predictable commitments.
Operating leases are forecast to expand at a 6.9% CAGR through 2031, the highest rate among financing types. The construction equipment finance market size for this format benefits from contractors seeking return options at the end of a project. Leasing was the dominant capital-expenditure model for 31% of European construction leaders surveyed by BNP Paribas Leasing Solutions. Operating leases require strong residual-value assessment and remarketing capability. Revolving and fleet facilities serve a narrower but growing role among large rental fleets. These facilities provide flexible credit availability that can track changes in equipment demand and project pipelines. The mix of products allows borrowers to select ownership, usage, and repayment structures that match their operating needs.
Earthmoving equipment accounted for 39.1% of the construction equipment finance market share in 2025. Excavators, dozers, graders, and loaders are needed for road building, site preparation, rail work, and urban development. Their broad use supports both origination activity and lender confidence in collateral. Construction equipment ranked first in financing appetite for the 12th consecutive year in a 2026 survey of finance professionals. Earthmoving assets tend to have established resale channels, which helps support underwriting decisions. Their role across project types also limits reliance on one construction application.
Material handling and lifting equipment is forecast to grow at a 6.1% CAGR through 2031. The construction equipment finance market size for this category is supported by vertical urban construction, logistics facilities, and offshore wind projects. Tower cranes meet the needs of taller buildings and constrained sites. Automated lifting systems support equipment requirements at e-commerce fulfillment centers. Heavy marine lifting equipment is needed for offshore wind installation. Roadbuilding and compaction equipment follow transport infrastructure cycles, while concrete equipment is more exposed to building activity. Specialized equipment, including tunnel-boring machines and lifting rigs, usually requires bespoke finance because of high ticket values and project-specific use.
Complete Report Scope:
- By Financing Type
- Loans, Term Loans and Hire-Purchase
- Finance Leases / Capital Leases
- Operating Leases
- Revolving And Fleet Facilities
- By Equipment Type
- Earthmoving Equipment
- Material Handling and Lifting Equipment
- Roadbuilding and Compaction Equipment
- Concrete Equipment
- Other Specialized Equipment
- By Application
- Building Construction
- Infrastructure and Civil Engineering
- Mining and Quarrying
- Industrial, Energy and Process Facilities
- Mixed / Multi-Application Fleets
- By End User
- Construction and Civil Contractors
- Equipment Rental Companies
- Mining and Quarrying Companies
- Government and Municipal Entities
- Industrial, Energy and Other Owner-Operators
- By Financing Provider
- Banks and Bank-Owned Equipment-Finance Units
- OEM-Captive Finance Companies
- Independent Lessors, NBFCs and Specialty Finance Companies
- Other On-Balance-Sheet Providers
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- Thailand
- Malaysia
- Singapore
- Vietnam
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Turkey
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific held 39.6% of the global construction equipment finance market share in 2025. China and India remain the region's main demand centers because both support large infrastructure programs. China's state-led investment cycle creates concentrated equipment-finance origination opportunities. India's National Infrastructure Pipeline supports procurement for roads, railways, and urban development. ICBC Financial Leasing supports financing across engineering machinery, port equipment, and railway infrastructure assets. Southeast Asian countries, including Indonesia, Vietnam, Malaysia, and Thailand, are emerging centers for equipment-finance activity. Japan recorded steadier demand from urban renewal and disaster-resilience projects. Japan Bank for International Cooperation provided USD 14.3 million within a USD 23.8 million syndicated facility to PT. SMFL Leasing Indonesia in 2025 for construction equipment leasing.
North America and Europe account for substantial construction equipment finance volume because financing penetration and fleet replacement needs are high. The United States has a mature credit infrastructure and a large installed machinery base. Construction equipment remained the third-largest equipment category by new business volume. In Europe, established leasing frameworks support use-based access to machinery. Groupe BPCE created BPCE Equipment Solutions after acquiring Societe Generale Equipment Finance in the first quarter of 2025. South America remains smaller, with demand linked to commodity investment and infrastructure stimulus, while currency risk and credit availability can constrain access.
The Middle East and Africa recorded the fastest projected regional CAGR at 6.8% through 2031. Saudi Arabia and the UAE support equipment demand through large construction programs and infrastructure investment. These programs create demand for specialized equipment and related financing structures. The region also has a distinct Shariah-compliant finance channel, including Ijarah-based leasing. This channel shapes product design and lender eligibility for equipment procurement. Al Rajhi Bank offers an equipment-finance program for business customers in Saudi Arabia. The construction equipment finance market share in this region remains below that of the Asia-Pacific region, but the project pipeline supports higher growth. Regional providers must combine conventional and Shariah-compliant products to address different customer needs.
- Caterpillar Financial Services (Cat Financial)
- Deere & Company / John Deere Financial
- Komatsu Financial
- Volvo Financial Services
- CNH Industrial Capital
- Wells Fargo Equipment Finance
- BNP Paribas Leasing Solutions
- Mitsubishi HC Capital
- DLL Group (De Lage Landen)
- Sumitomo Mitsui Finance and Leasing (SMFL)
- Bank of America Equipment Finance
- J.P. Morgan Equipment Finance
- Liebherr Financial Services
- JCB Finance
- SANY Finance
- First Citizens Bank Equipment Finance
- ORIX Corporation
- Mizuho Leasing
- ICBC Financial Leasing (ICBC Leasing)
- BPCE Equipment Solutions
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Infrastructure and Construction Investment Driving Equipment Acquisition
- 4.2.2 High Equipment Acquisition Costs and Contractor Liquidity Preservation
- 4.2.3 Shift Toward Asset-Light, Flexible and Project-Aligned Equipment Access
- 4.2.4 Expansion of OEM-Captive, Dealer and Embedded Equipment Finance
- 4.2.5 Digital and Telematics-Enabled Equipment Finance
- 4.2.6 Rising Equipment Replacement, Fleet Modernization and Electrification Needs
- 4.3 Market Restraints
- 4.3.1 High Financing Costs and Contractor Credit Risk
- 4.3.2 Used-Equipment Residual-Value and Secondary-Market Liquidity Risk
- 4.3.3 Equipment Obsolescence and Technology-Driven Residual-Value Uncertainty
- 4.3.4 Fragmented Asset Data and Telematics Interoperability Constraints
- 4.4 Value Chain Analysis
- 4.4.1 Equipment OEMs and Dealer-Based Finance Origination
- 4.4.2 Captive Finance, Banks and Independent Leasing Providers
- 4.4.3 Credit Underwriting, Asset Monitoring and Contract Servicing
- 4.4.4 Equipment Remarketing, Residual-Value Management and Recovery
- 4.5 Regulatory Landscape
- 4.5.1 Equipment Lending, Leasing, and Collateral-Enforcement Regulations
- 4.5.2 Lease Accounting, Tax and Asset-Ownership Treatment
- 4.5.3 Emissions, Equipment Eligibility and Environmental Compliance
- 4.5.4 Data Privacy, Telematics and Financial Cybersecurity Requirements
- 4.6 Technological Outlook
- 4.6.1 Digital Equipment-Finance Origination and Automated Credit Verification
- 4.6.2 AI-Enabled Credit Scoring, Risk Assessment and Fraud Detection
- 4.6.3 Telematics- and IoT-Enabled Asset Monitoring and Predictive Maintenance
- 4.6.4 API-Driven Embedded Finance and Digital Payment Infrastructure
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Financing Type
- 5.1.1 Loans, Term Loans and Hire-Purchase
- 5.1.2 Finance Leases / Capital Leases
- 5.1.3 Operating Leases
- 5.1.4 Revolving And Fleet Facilities
- 5.2 By Equipment Type
- 5.2.1 Earthmoving Equipment
- 5.2.2 Material Handling and Lifting Equipment
- 5.2.3 Roadbuilding and Compaction Equipment
- 5.2.4 Concrete Equipment
- 5.2.5 Other Specialized Equipment
- 5.3 By Application
- 5.3.1 Building Construction
- 5.3.2 Infrastructure and Civil Engineering
- 5.3.3 Mining and Quarrying
- 5.3.4 Industrial, Energy and Process Facilities
- 5.3.5 Mixed / Multi-Application Fleets
- 5.4 By End User
- 5.4.1 Construction and Civil Contractors
- 5.4.2 Equipment Rental Companies
- 5.4.3 Mining and Quarrying Companies
- 5.4.4 Government and Municipal Entities
- 5.4.5 Industrial, Energy and Other Owner-Operators
- 5.5 By Financing Provider
- 5.5.1 Banks and Bank-Owned Equipment-Finance Units
- 5.5.2 OEM-Captive Finance Companies
- 5.5.3 Independent Lessors, NBFCs and Specialty Finance Companies
- 5.5.4 Other On-Balance-Sheet Providers
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Indonesia
- 5.6.4.7 Thailand
- 5.6.4.8 Malaysia
- 5.6.4.9 Singapore
- 5.6.4.10 Vietnam
- 5.6.4.11 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Turkey
- 5.6.5.4 South Africa
- 5.6.5.5 Egypt
- 5.6.5.6 Rest of Middle East and Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis (Top 5-6 players)
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Caterpillar Financial Services (Cat Financial)
- 6.4.2 Deere & Company / John Deere Financial
- 6.4.3 Komatsu Financial
- 6.4.4 Volvo Financial Services
- 6.4.5 CNH Industrial Capital
- 6.4.6 Wells Fargo Equipment Finance
- 6.4.7 BNP Paribas Leasing Solutions
- 6.4.8 Mitsubishi HC Capital
- 6.4.9 DLL Group (De Lage Landen)
- 6.4.10 Sumitomo Mitsui Finance and Leasing (SMFL)
- 6.4.11 Bank of America Equipment Finance
- 6.4.12 J.P. Morgan Equipment Finance
- 6.4.13 Liebherr Financial Services
- 6.4.14 JCB Finance
- 6.4.15 SANY Finance
- 6.4.16 First Citizens Bank Equipment Finance
- 6.4.17 ORIX Corporation
- 6.4.18 Mizuho Leasing
- 6.4.19 ICBC Financial Leasing (ICBC Leasing)
- 6.4.20 BPCE Equipment Solutions
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
- 7.1.1 Flexible Financing for Electric and Low-Emission Construction Equipment
- 7.1.2 Flexible, Usage- and Project-Linked Repayment Models for SMEs and Contractors
- 7.1.3 Data-Enabled Financing for Underserved and Secondary Equipment Markets

