PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2163592

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2163592
Multispectral LiDAR Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
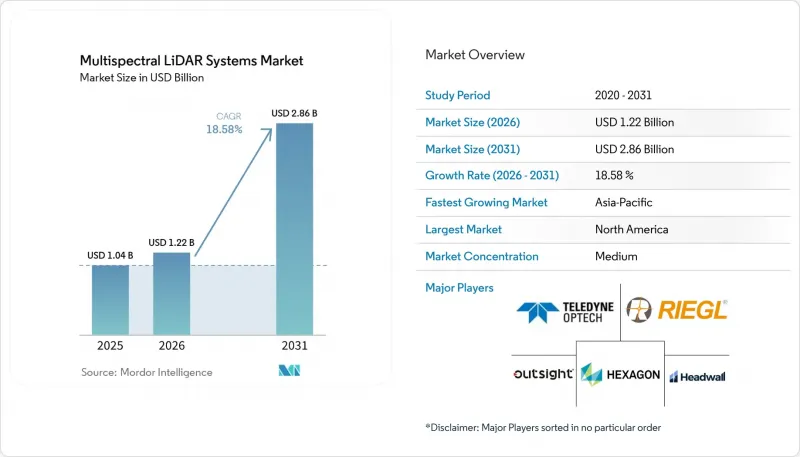
According to Mordor Intelligence, the multispectral LiDAR systems market size is projected to expand from USD 1.04 billion in 2025 to USD 1.22 billion in 2026, and to USD 2.86 billion by 2031, registering a CAGR of 18.58% between 2026 and 2031.
Global Multispectral LiDAR Systems Market Trends and Insights
Demand for Simultaneous 3D Structure and Spectral Classification
Passive imagery and single-wavelength LiDAR can struggle to distinguish objects with similar shapes but different materials. Asphalt, moist soil, and grass can have comparable geometric profiles while showing different NIR and SWIR reflectance. Multispectral systems capture these structural and spectral signals in the same pass. A 2025 study reported improved urban scene classification from co-registered multispectral point clouds when compared with single-band baselines. This capability supports the use of material labels in downstream robotics and sorting workflows. The Multispectral LiDAR Systems Market benefits when classification needs are as important as spatial measurement, particularly when operators need results from a single coordinated collection process.
Growth in Coastal, Inland-Water, and Topo-Bathymetric Mapping
National mapping programs provide a steady source of demand for topo-bathymetric systems. These programs generally use multiyear procurement cycles, which can reduce sensitivity to short-term commercial survey budgets. Teledyne Geospatial introduced Fathom in February 2025 with a 2,000,000 points/sec topographic channel, a green bathymetric channel, and a 120 MP RGB and NIR camera. Leica Geosystems introduced CoastalMapper in February 2025, capable of collecting 1 million bathymetric and 2 million topographic points/second, covering 360 km2/hr. These releases made integrated coastal mapping systems more accessible as standard products within the Multispectral LiDAR Systems Market. NOAA's coastal topobathy data program and the U.S. Army Corps of Engineers continue to support demand for green and NIR configurations.
High Acquisition, Calibration, and Processing Cost
Multispectral LiDAR systems require proprietary optical designs, multichannel detectors, and wavelength-specific calibration. These features make their acquisition cost higher than that of single-wavelength platforms. Project operators may struggle to spread this cost across assignments that do not need material classification. Processing also requires more computing capacity and specialized skills because the point clouds contain multiple registered channels. Nonstandard radiometric correction workflows can increase operating complexity. The constraint is strongest in South America and Middle East, and Africa, where import duties and limited calibration capacity can increase the total cost of ownership for participants in the Multispectral LiDAR Systems Market.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Precision Forestry and Natural-Resource Monitoring
- One-Flight Data Fusion Reducing Repeat Missions and Registration Error
- Limited Benchmark Datasets and Ground Truth
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Airborne systems held 48.63% of the product-type segment in 2025. Their position reflects operational range, payload capacity, and a long procurement history. Fixed-wing aircraft and helicopters remain suitable for coastal surveys and large forestry assignments. These missions benefit from endurance and the ability to carry several sensors.
UAV-mounted systems are projected to expand at a 19.83% CAGR from 2026 to 2031. Lower payload weight can reduce cost per hectare for forestry and mine-site teams. RIEGL presented the miniVUX-4UAV at INTERGEO 2026, featuring up to 400 kHz operation and 12 mm accuracy on a platform below 1 kg. Terrestrial systems remain focused on geological outcrops and industrial stockpiles, while mobile systems support highway and port applications. The Multispectral LiDAR Systems Industry continues to experience a product gap between academic mobile prototypes and standard commercial catalogs, leaving an opening in the Multispectral LiDAR Systems Market.
Green and NIR configurations accounted for 39.47% of the Multispectral LiDAR Systems Market in 2025. The 532 nm green and 1,064 nm NIR pairing supports bathymetry and topographic intensity contrast. This pairing remains central to coastal and vegetation mapping. National hydrographic programs continue to favor this configuration for water and terrain surveys.
NIR and SWIR configurations are projected to expand at a 19.67% CAGR through 2031. Automotive perception and ore sorting benefit from their additional material specificity. IEC 60825-1 eye-safety requirements also influence the use of longer wavelengths in some industrial and military applications. Green, NIR, and SWIR triband systems bridge the gap between established 2-channel products and multiband designs. Tunable and broadband systems remain largely at the prototype stage, although research in 2026 showed continued work on photonic LiDAR architectures. These architecture choices affect product development within the Multispectral LiDAR Systems Market.
Complete Report Scope:
- By Product Type
- Airborne Multispectral LiDAR Systems
- UAV-Mounted Multispectral LiDAR Systems
- Terrestrial Multispectral LiDAR Systems
- Mobile and Vehicle-Mounted Multispectral LiDAR Systems
- By Wavelength Configuration
- Green + Near-Infrared (NIR)
- Green + NIR + Short-Wave Infrared (SWIR)
- NIR + SWIR
- Multiband and Four-or-More Discrete Wavelengths
- Tunable and Broadband Spectral LiDAR
- By Platform
- Fixed-Wing Aircraft
- Helicopters
- Uncrewed Aerial Vehicles (UAVs)
- Ground Vehicles and Industrial Machines
- Tripod, Gantry, and Laboratory Platforms
- By End-User Industry
- Government and Defense Agencies
- Surveying, Mapping, and Geospatial Service Providers
- Engineering, Construction, and Infrastructure (AEC) Firms
- Utilities, Energy, and Power Operators
- Mining and Extractive Industry Operators
- Agriculture and Forestry Operators
- Environmental, Conservation, and Natural-Resource Organizations
- Research Institutions and Universities
- Automotive
- Industrial Robotics
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of the Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 34.67% of the Multispectral LiDAR Systems Market share in 2025. NOAA, the U.S. Army Corps of Engineers, and the U.S. Geological Survey support demand for coastal and topographic mapping. Canada adds demand from natural-resource inventory and forest carbon accounting. Mexico remains at an earlier stage, with activity concentrated in infrastructure corridor mapping. The February 2025 launches of Fathom and CoastalMapper were directed toward North American coastal survey requirements.
Asia-Pacific is projected to expand at a 19.87% CAGR between 2026 and 2031. China's autonomous vehicle programs and demand for drone-based infrastructure inspection support in the region. India's National Infrastructure Pipeline supports the mapping needs of highways, railways, and water bodies. Japan's aging civil engineering workforce strengthens the case for automated drone survey methods. Compact UAV sensors are positioned for commercial survey firms that need lower-cost access to the Multispectral LiDAR Systems Market.
Europe had a meaningful presence in 2025, led by Germany, the United Kingdom, and France. Finland and Sweden have extensive operational experience with multispectral airborne LiDAR, including work with the Finnish Geospatial Research Institute's HeliALS system. Hexagon acquired ITRES in June 2026, bringing airborne hyperspectral and thermal imaging capabilities into its Leica geospatial portfolio. South America offers potential in Amazon monitoring and precision agriculture but faces duties and calibration constraints, while the Middle East and Africa remain in an early adoption stage, with demand tied mainly to defense, oil and gas, and pipeline mapping projects in the Multispectral LiDAR Systems Market.
- Teledyne Optech Incorporated
- RIEGL Laser Measurement Systems GmbH
- Hexagon AB
- Leica Geosystems AG
- IRIDESENSE SAS
- Outsight SA
- Finnish Geospatial Research Institute
- National Land Survey of Finland
- Headwall Photonics, Inc.
- GRYFN, Inc.
- Ouster, Inc.
- Velodyne Lidar, Inc.
- SBG Systems SAS
- Applanix Corporation
- Specim, Spectral Imaging Ltd.
- Teledyne CARIS, Inc.
- Optech Incorporated
- OPEGIEKA Sp. z o.o.
- SensUp SAS
- Outsight Tech SAS
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Demand for Simultaneous 3D Structure and Spectral Classification
- 4.2.2 Growth in Coastal, Inland-Water, and Topo-Bathymetric Mapping
- 4.2.3 Expansion of Precision Forestry and Natural-Resource Monitoring
- 4.2.4 Material-Aware Automation in Mining, Quarries, and Biomass Handling
- 4.2.5 One-Flight Data Fusion Reducing Repeat Missions and Registration Error
- 4.2.6 AI Training Demand for Co-Registered Spectral-Structural Point Clouds
- 4.3 Market Restraints
- 4.3.1 High Acquisition, Calibration, and Processing Cost
- 4.3.2 Limited Benchmark Datasets and Ground Truth
- 4.3.3 Cross-Channel Co-Registration and Radiometric Drift in Operational Fleets
- 4.3.4 Spectral-Band Selection Lock-In and Workflow Fragmentation
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Supply-Chain Analysis
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Airborne Multispectral LiDAR Systems
- 5.1.2 UAV-Mounted Multispectral LiDAR Systems
- 5.1.3 Terrestrial Multispectral LiDAR Systems
- 5.1.4 Mobile and Vehicle-Mounted Multispectral LiDAR Systems
- 5.2 By Wavelength Configuration
- 5.2.1 Green + Near-Infrared (NIR)
- 5.2.2 Green + NIR + Short-Wave Infrared (SWIR)
- 5.2.3 NIR + SWIR
- 5.2.4 Multiband and Four-or-More Discrete Wavelengths
- 5.2.5 Tunable and Broadband Spectral LiDAR
- 5.3 By Platform
- 5.3.1 Fixed-Wing Aircraft
- 5.3.2 Helicopters
- 5.3.3 Uncrewed Aerial Vehicles (UAVs)
- 5.3.4 Ground Vehicles and Industrial Machines
- 5.3.5 Tripod, Gantry, and Laboratory Platforms
- 5.4 By End-User Industry
- 5.4.1 Government and Defense Agencies
- 5.4.2 Surveying, Mapping, and Geospatial Service Providers
- 5.4.3 Engineering, Construction, and Infrastructure (AEC) Firms
- 5.4.4 Utilities, Energy, and Power Operators
- 5.4.5 Mining and Extractive Industry Operators
- 5.4.6 Agriculture and Forestry Operators
- 5.4.7 Environmental, Conservation, and Natural-Resource Organizations
- 5.4.8 Research Institutions and Universities
- 5.4.9 Automotive
- 5.4.10 Industrial Robotics
- 5.4.11 Other End-User Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of the Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market RankandShare, Products and Services, Recent Developments)
- 6.4.1 Teledyne Optech Incorporated
- 6.4.2 RIEGL Laser Measurement Systems GmbH
- 6.4.3 Hexagon AB
- 6.4.4 Leica Geosystems AG
- 6.4.5 IRIDESENSE SAS
- 6.4.6 Outsight SA
- 6.4.7 Finnish Geospatial Research Institute
- 6.4.8 National Land Survey of Finland
- 6.4.9 Headwall Photonics, Inc.
- 6.4.10 GRYFN, Inc.
- 6.4.11 Ouster, Inc.
- 6.4.12 Velodyne Lidar, Inc.
- 6.4.13 SBG Systems SAS
- 6.4.14 Applanix Corporation
- 6.4.15 Specim, Spectral Imaging Ltd.
- 6.4.16 Teledyne CARIS, Inc.
- 6.4.17 Optech Incorporated
- 6.4.18 OPEGIEKA Sp. z o.o.
- 6.4.19 SensUp SAS
- 6.4.20 Outsight Tech SAS
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

