PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2163605

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2163605
China Milling Machines - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
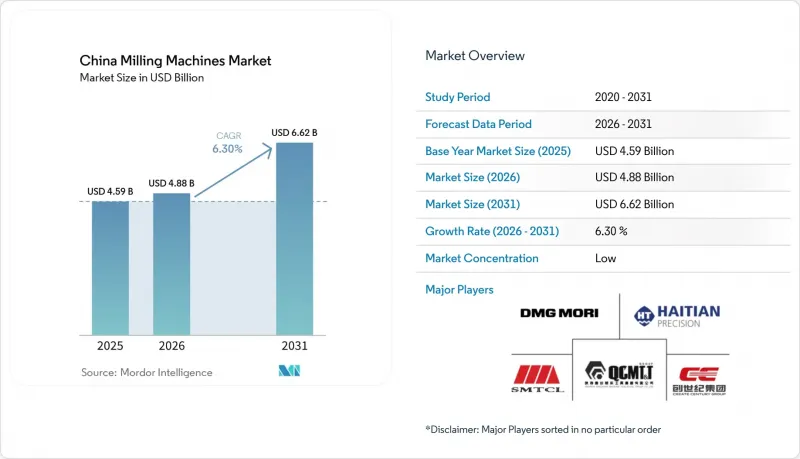
According to Mordor Intelligence, the China milling machines market size is expected to grow from USD 4.59 billion in 2025 to USD 4.88 billion in 2026 and is forecast to reach USD 6.62 billion by 2031 at 6.30% CAGR over 2026-2031.
China Milling Machines Market Trends and Insights
Large-Scale Manufacturing Base Sustains Broad Milling-Machine Demand
China accounted for 29% of global manufacturing output, creating demand for milling equipment across a wide range of industrial activities. Value-added output at machinery enterprises above the designated scale grew 8.2% in 2025. Metal-cutting machine-tool output reached 868,200 units in 2025, which was 9.7% higher than 2024. New orders rose 9.3% in 2025, and recorded 7.9% increase in orders on hand. This pattern supports the China milling machines market because demand comes from capacity additions as well as routine replacement. Its wide end-user base reduces the effect that weakness in any one manufacturing sector could have on equipment demand. This diversity gives machine suppliers a broader order base across production cycles.
EV and Automotive Capacity Expansion Is Increasing Demand for Precision Machining
China produced approximately 16 million electric cars in 2025, representing nearly 75% of global electric-car production. Electric models accounted for more than 35% of China's total car exports in 2025, compared with 20% in 2024. Motor housings, e-axle casings, rotor bores, and battery-tray structures require precision milling across the supplier base. China also produced more than 400,000 electric trucks in 2025, exceeding its combined output during 2020-2024. Higher tolerance requirements are encouraging component suppliers to replace older equipment with more capable CNC machines. This creates a durable demand channel for the China milling machines market as vehicle production and related parts capacity expand. Suppliers that meet automotive accuracy and throughput needs can benefit across several component categories.
Intense Domestic Competition Is Putting Pressure on Milling-Machine Prices and Margins
Metal-cutting machine-tool output increased 9.7% in 2025, while new orders increased 9.3%. The combination indicates active demand but also a large domestic supply base. National performance standards establish a quality floor, but they do not limit the number of competitors in lower and mid-range equipment. Fixed-asset investment in the machine-tool and tooling sector declined in 2025. Price competition can restrict the funds that smaller producers can devote to research and development. This pressure may slow the movement of some China milling machines market participants into higher-value categories. Producers with limited resources may find it harder to fund extended product development.
Other drivers and restraints analyzed in the detailed report include:
- Factory Automation Is Increasing Demand for CNC Machines Compatible with Automated Production Cells
- Domestic high-end machine-tool development expands demand for advanced milling equipment
- Export Controls and Trade Tensions Complicate Access to Advanced Technologies and Overseas Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Vertical milling machines held 49.5% of China milling machines market revenue in 2025. Their position reflects broad use in general engineering shops, mold-and-die facilities, and automotive component production. Vertical spindle layouts are familiar to operators and support straightforward programming for many standard parts. They also serve the large, small, and medium-sized machining base that relies on vertical machining centers as core production equipment. The segment's installed base supports ongoing demand for replacement machines and related upgrades. This makes vertical equipment the volume anchor of the China milling machines market.
Horizontal milling machines are forecast to grow at a 7.3% CAGR through 2031. Automotive original equipment manufacturers and Tier 1 suppliers use these systems where throughput, rigidity, and multi-pallet automation are important. Horizontal layouts can support longer unattended production cycles in automated manufacturing cells. Gantry mills and large-format machining centers serve wind turbine housings, aerospace structures, and energy equipment components. Haitian Precision introduced three 5-axis machining centers at CCMT 2026 for medium and large complex parts, high-efficiency production, and curved-surface machining. This development shows how suppliers are extending their offerings beyond standard vertical platforms.
3-axis machines accounted for 53.5% of the China milling machines market size in 2025. They are widely used for automotive castings, machinery housings, mold cavities, and general-purpose parts. Their cost and application range make them suitable for the broad mid-market. The installed base is substantial, but mature product categories face continued price pressure. 4-axis equipment provides an intermediate option for more complex contours and selected automotive parts. As a result, 3-axis systems remain the central revenue base for the China milling machines market.
5-axis and above machines are forecast to grow at a 10.5% CAGR through 2031. Aerospace blisks, turbine blades, semiconductor equipment housings, and complex NEV drivetrain parts require simultaneous multi-axis motion. These machines sell at three to five times the average price of comparable 3-axis platforms. Chinese suppliers held more than 8% of the high-tier CNC machine market in recent years. This compares with the 80% domestic-market-share target set under Made in China 2025 for 2025. The gap highlights the continuing role of Japanese and European suppliers in the most demanding applications. Fiscal support for industrial mother-machine producers encourages domestic development of 5-axis capabilities.
Complete Report Scope:
- By Machine Type
- Vertical Milling Machines
- Horizontal Milling Machines
- Others (Gantry mills, etc.)
- By Axis Type
- 3-Axis Machine
- 4-Axis Machine
- 5-Axis and More
- By Technology
- Conventional / Manual Milling Machines
- CNC Milling Machines
- Hybrid Machines
- By End-User Industry
- Automotive & Transportation
- Aerospace & Defense
- Industrial Machinery
- Energy & Power
- Medical Devices
- Electronics & Semiconductor
- Construction & Mining Equipment
- General Manufacturing
- Others
List of Companies Covered in this Report:
- Ningbo Haitian Precision Machinery Co., Ltd.
- Shenyang Machine Tool Co., Ltd.
- Qinchuan Machine Tool and Tool Group Corp.
- Shenzhen Create Century Machinery Co., Ltd.
- DMG MORI Co., Ltd.
- DN Solutions Co., Ltd.
- Hyundai WIA Corporation
- GROB-WERKE GmbH & Co. KG
- FANUC Corporation
- JTEKT Corporation
- Yamazaki Mazak Corporation
- Okuma Corporation
- Dalian Machine Tool Group (DMTG)
- Makino Milling Machine Co., Ltd.
- Nantong Guosheng Intelligence Technology Group Co., Ltd.
- Zhejiang RIFA Precision Machinery Co., Ltd.
- Chongqing Machine Tool Co., Ltd.
- Guangdong Taikan NC Machine Co., Ltd.
- Jinan First Machine Tool Co., Ltd.
- Haas Automation, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
- 3.1 Market Snapshot (2025 vs. 2031)
- 3.2 Key Findings by Segment
- 3.3 Key Growth Opportunities
4 Market Landscape
- 4.1 Market Overview
- 4.1.1 Global Milling Machine Market Ecosystem
- 4.1.2 Evolution of Milling Machines
- 4.2 Market Drivers
- 4.2.1 Large-scale manufacturing base sustains broad milling-machine demand
- 4.2.2 EV and automotive capacity expansion increases precision-machining demand
- 4.2.3 Factory automation increases demand for CNC machines suited to automated production cells
- 4.2.4 Domestic high-end machine-tool development expands demand for advanced milling equipment
- 4.2.5 Industrial equipment renewal accelerates the replacement of aging machining assets
- 4.2.6 Aerospace, semiconductor, energy, and high-end equipment expansion raises complex-machining demand
- 4.3 Market Restraints
- 4.3.1 Intense domestic competition is putting pressure on milling-machine prices and margins
- 4.3.2 Export controls and trade tensions complicate access to advanced technologies and overseas markets
- 4.3.3 Dependence on advanced imported components limits high-end machine development
- 4.3.4 Weak investment conditions among smaller manufacturers can delay machine purchases
- 4.4 Market Trends
- 4.4.1 Milling is shifting from conventional three-axis machining toward five-axis and high-precision platforms
- 4.4.2 CNC milling machines are becoming integrated components of smart factories
- 4.4.3 Chinese machine-tool manufacturers are increasingly using exports to expand beyond the domestic market
- 4.5 Value / Supply-Chain Analysis
- 4.5.1 Raw Materials & Critical Components
- 4.5.2 Machine Design & Engineering
- 4.5.3 Machine Manufacturing & Assembly
- 4.5.4 Distribution, System Integration & Installation
- 4.5.5 Aftermarket & Lifecycle Services
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.7.1 Five-axis simultaneous machining
- 4.7.2 Robotic machine tending and automated production cells
- 4.7.3 IoT-enabled CNC and intelligent machining
- 4.8 Insights on the Global Machine Tools Market
- 4.9 Trade Analysis
- 4.10 Impact of Geopolitical Events on the Market
5 Market Size & Growth Forecasts
- 5.1 By Machine Type
- 5.1.1 Vertical Milling Machines
- 5.1.2 Horizontal Milling Machines
- 5.1.3 Others (Gantry mills, etc.)
- 5.2 By Axis Type
- 5.2.1 3-Axis Machine
- 5.2.2 4-Axis Machine
- 5.2.3 5-Axis and More
- 5.3 By Technology
- 5.3.1 Conventional / Manual Milling Machines
- 5.3.2 CNC Milling Machines
- 5.3.3 Hybrid Machines
- 5.4 By End-User Industry
- 5.4.1 Automotive & Transportation
- 5.4.2 Aerospace & Defense
- 5.4.3 Industrial Machinery
- 5.4.4 Energy & Power
- 5.4.5 Medical Devices
- 5.4.6 Electronics & Semiconductor
- 5.4.7 Construction & Mining Equipment
- 5.4.8 General Manufacturing
- 5.4.9 Others
6 Competitive Landscape
- 6.1 Market Concentration Overview
- 6.2 Key Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Ningbo Haitian Precision Machinery Co., Ltd.
- 6.4.2 Shenyang Machine Tool Co., Ltd.
- 6.4.3 Qinchuan Machine Tool and Tool Group Corp.
- 6.4.4 Shenzhen Create Century Machinery Co., Ltd.
- 6.4.5 DMG MORI Co., Ltd.
- 6.4.6 DN Solutions Co., Ltd.
- 6.4.7 Hyundai WIA Corporation
- 6.4.8 GROB-WERKE GmbH & Co. KG
- 6.4.9 FANUC Corporation
- 6.4.10 JTEKT Corporation
- 6.4.11 Yamazaki Mazak Corporation
- 6.4.12 Okuma Corporation
- 6.4.13 Dalian Machine Tool Group (DMTG)
- 6.4.14 Makino Milling Machine Co., Ltd.
- 6.4.15 Nantong Guosheng Intelligence Technology Group Co., Ltd.
- 6.4.16 Zhejiang RIFA Precision Machinery Co., Ltd.
- 6.4.17 Chongqing Machine Tool Co., Ltd.
- 6.4.18 Guangdong Taikan NC Machine Co., Ltd.
- 6.4.19 Jinan First Machine Tool Co., Ltd.
- 6.4.20 Haas Automation, Inc.
7 Market Opportunities & Future Outlook
- 7.1 Emerging Growth Opportunities
- 7.2 Strategic Recommendations
- 7.3 Future Outlook

