PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2184668

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2184668
Asia Pacific Automotive Engine - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
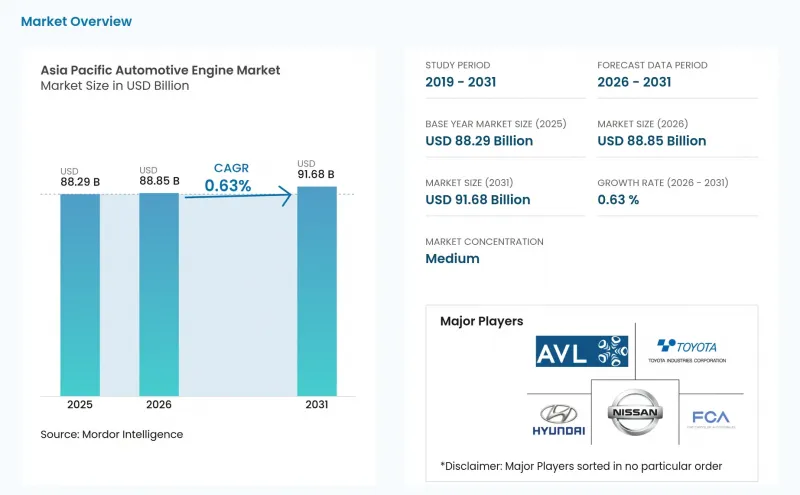
According to Mordor Intelligence, the Asia Pacific automotive engine market size was valued at USD 88.29 billion in 2025, and is expected to reach USD 88.85 billion in 2026, and is projected to reach USD 91.68 billion by 2031, at a CAGR of 0.63% during the forecast period (2026-2031).
Asia Pacific Automotive Engine Market Trends and Insights
Rapid Growth in OEM Production and Vehicle Parc Across Emerging Asia Pacific Economies
China experienced a notable increase in passenger vehicle production, reflecting steady growth compared to the previous year. India also achieved significant production growth, supported by the reopening of rural credit lines. Indonesia and Thailand, leveraging tariff advantages, collectively expanded their vehicle assembly operations, with Japanese and Chinese brands establishing knock-down lines. By 2025, the vehicle parc in the region reached a substantial level, driving strong aftermarket demand for engines, particularly those within the mid-life age range. In response to varying fuel-quality and testing standards, automakers have introduced "India-spec" and "China-spec" engines. These engines feature locked ECU firmware, resulting in fragmented supply chains and increased engineering budgets. Such developments ensure that the Asia Pacific automotive engine market remains closely tied to replacement cycles, even as the adoption of new-vehicle electrification continues to gain momentum .
Stringent Regional Emission Norms Driving ICE Downsizing & Efficiency Tech
China has enforced its National VI-b rule, mandating real-driving-emissions testing and promoting the adoption of particulate filters in gasoline vehicles. In India, the Bharat Stage VI regulation significantly reduced permissible NOx emissions in light diesel vehicles. This change necessitated the use of selective catalytic reduction with urea dosing, increasing the cost per engine. Japan's 2025 update to its Post New Long-Term norms tightened limits on particle numbers, hastening the shift to dual-injection gasoline systems. Meanwhile, South Korea's LEV III standards have steered original equipment manufacturers (OEMs) towards adopting turbocharged three-cylinder engines. Collectively, these regulations are squeezing profit margins for Tier-1 suppliers in the Asia Pacific automotive engine sector. However, they simultaneously open doors for specialists in aftertreatment and lightweighting solutions.
Accelerating BEV / ZEV Adoption Eroding Long-Term ICE Demand
New-energy vehicles captured a significant share of passenger-car sales in China. Meanwhile, Japan and South Korea experienced moderate adoption of battery electric vehicles (BEVs), driven by substantial purchase subsidies and extensive fast-charging networks. In India, electric two-wheelers gained notable traction, supported by state incentives offering considerable financial benefits. As original equipment manufacturers (OEMs) accelerate electrification to meet fleet CAFE targets, traditional internal combustion engine (ICE) platforms are losing scale, creating challenges for the automotive engine market across the Asia Pacific region.
Other drivers and restraints analyzed in the detailed report include:
- Localization Race for AI-Driven Smart Machining of Engine Blocks in ASEAN
- Public Grants for Hydrogen-ICE R&D in South Korea and China's Port Equipment
- Fuel-Price Volatility & Supply-Chain Shocks for Refined Products
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Opposed-piston prototypes currently hold a minute slice, yet the configuration posts a 1.67% CAGR to 2031, as Achates-licensed two-stroke designs for port equipment claim higher thermal efficiency. In-line engines maintained a 45.16% share of the Asia Pacific automotive engine market in 2025 due to packaging ease in compact cars and light trucks. V-type units still power premium SUVs and heavy haulers above 3 liters, though their relevance fades as turbo-hybrid fours replace V6s. Subaru's boxer layout and Volkswagen Group W-types remain confined to niche sports and luxury models. Downsizing, forced induction, and combustion-hybrid synergies reinforce the in-line architecture's dominance within the Asia Pacific automotive engine market.
Product planners now invest in flexible machining lines that switch from gasoline to hybrid block variants without lengthy changeovers. This agility protects capital returns while the opposed-piston concept eyes long-haul segments demanding lower specific fuel consumption. Continued R&D contracts from Chinese ports and Australian miners could draw more suppliers to the layout, but validation cycles and unfamiliar maintenance needs slow mass uptake.
Gasoline led with a 46.18% share in 2025, powered by the two-wheeler boom across India, Indonesia, and Vietnam. Diesel slipped to an estimated 26% share as city bans and tighter soot limits bite. Hydrogen ICE, while embryonic, clocks the fastest 1.75% CAGR through 2031, helped by South Korean and Japanese pilots. While natural-gas engines power Indian three-wheelers and mid-weight trucks, they have yet to make significant inroads beyond metro corridors. In the Asia Pacific automotive engine industry, hybrid-ICE systems, led by Toyota and Honda, have gained notable traction in passenger-car builds, blurring the lines between traditional combustion and electrification.
Despite policymakers promoting ethanol, LPG, and synthetic-fuel blends to greenify older fleets, infrastructure limitations and certification challenges have kept their market share minimal. As a result, suppliers are pivoting: focusing on gasoline hybrid modules for volume, diesel for torque-sensitive fleets, and hydrogen ICE for specialized, high-demand hubs.
Complete Report Scope:
- By Placement Type
- In-line
- V-type
- W-type
- Boxer / Flat
- Opposed-piston
- By Fuel Type
- Gasoline
- Diesel
- Natural Gas / CNG
- Hybrid-ICE (Mild, Full, Plug-in)
- Alternative Fuels (Ethanol, LPG, e-Fuels)
- Hydrogen ICE
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Medium & Heavy Commercial Vehicles
- Two-Wheelers & Powersports
- Off-road / Agricultural / Construction
- By Engine Capacity
- Below 1.5 L
- 1.5 to 3 L
- Over 3 L
- By Country
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
List of Companies Covered in this Report:
- Toyota Motor Corporation
- Honda Motor Co., Ltd.
- Hyundai Motor Group
- Nissan Motor Corporation
- Fiat Chrysler Automotive Group
- SAIC Motor Corporation
- Cummins Inc.
- Mitsubishi Heavy Industries Engine & Turbo
- Suzuki Motor Corporation
- Yanmar Holdings
- Isuzu Motors Ltd.
- Tata Motors Ltd.
- Ashok Leyland Ltd.
- Chongqing Changan Automobile
- Weichai Power Co., Ltd.
- BYD Auto Co., Ltd.
- Kirloskar Oil Engines
- Guangxi Yuchai Machinery
- Great Wall Motor Co.
- Hino Motors Ltd.
- Dongfeng Motor Group
- FAW Jiefang Automotive
- Jiangling Motors
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Growth in OEM Production and Vehicle PARC Across Emerging Asia Pacific Economies
- 4.2.2 Stringent Regional Emission Norms Driving ICE Downsizing & Efficiency Tech
- 4.2.3 Localization Race for AI-Driven Smart Machining of Engine Blocks in ASEAN
- 4.2.4 Exploding Ride-Hailing/Delivery Aftermarket for ECU Remapping of Small Engines
- 4.2.5 Public Grants for Hydrogen-ICE R&D in South Korea and China's Port Equipment
- 4.2.6 Government Pilots for Low-Carbon Synthetic Fuels (Japan & Australia)
- 4.3 Market Restraints
- 4.3.1 Accelerating BEV / ZEV Adoption Eroding Long-Term ICE Demand
- 4.3.2 Fuel-Price Volatility & Supply-Chain Shocks for Refined Products
- 4.3.3 Talent Flight From Traditional ICE R&D to EV Software & Battery Sectors
- 4.3.4 Metro-Level Bans on Legacy ICE Two-Wheelers in Tier-1 Asian Cities
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Placement Type
- 5.1.1 In-line
- 5.1.2 V-type
- 5.1.3 W-type
- 5.1.4 Boxer / Flat
- 5.1.5 Opposed-piston
- 5.2 By Fuel Type
- 5.2.1 Gasoline
- 5.2.2 Diesel
- 5.2.3 Natural Gas / CNG
- 5.2.4 Hybrid-ICE (Mild, Full, Plug-in)
- 5.2.5 Alternative Fuels (Ethanol, LPG, e-Fuels)
- 5.2.6 Hydrogen ICE
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Light Commercial Vehicles
- 5.3.3 Medium & Heavy Commercial Vehicles
- 5.3.4 Two-Wheelers & Powersports
- 5.3.5 Off-road / Agricultural / Construction
- 5.4 By Engine Capacity
- 5.4.1 Below 1.5 L
- 5.4.2 1.5 to 3 L
- 5.4.3 Over 3 L
- 5.5 By Country
- 5.5.1 China
- 5.5.2 India
- 5.5.3 Japan
- 5.5.4 South Korea
- 5.5.5 Rest of Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Toyota Motor Corporation
- 6.4.2 Honda Motor Co., Ltd.
- 6.4.3 Hyundai Motor Group
- 6.4.4 Nissan Motor Corporation
- 6.4.5 Fiat Chrysler Automotive Group
- 6.4.6 SAIC Motor Corporation
- 6.4.7 Cummins Inc.
- 6.4.8 Mitsubishi Heavy Industries Engine & Turbo
- 6.4.9 Suzuki Motor Corporation
- 6.4.10 Yanmar Holdings
- 6.4.11 Isuzu Motors Ltd.
- 6.4.12 Tata Motors Ltd.
- 6.4.13 Ashok Leyland Ltd.
- 6.4.14 Chongqing Changan Automobile
- 6.4.15 Weichai Power Co., Ltd.
- 6.4.16 BYD Auto Co., Ltd.
- 6.4.17 Kirloskar Oil Engines
- 6.4.18 Guangxi Yuchai Machinery
- 6.4.19 Great Wall Motor Co.
- 6.4.20 Hino Motors Ltd.
- 6.4.21 Dongfeng Motor Group
- 6.4.22 FAW Jiefang Automotive
- 6.4.23 Jiangling Motors
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

