PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2184683

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2184683
Baking Ingredients - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the baking ingredients market size is projected to expand from USD 19.15 billion in 2025 and USD 20.55 billion in 2026 to USD 29.39 billion by 2031, registering a CAGR of 7.42% between 2026 to 2031.
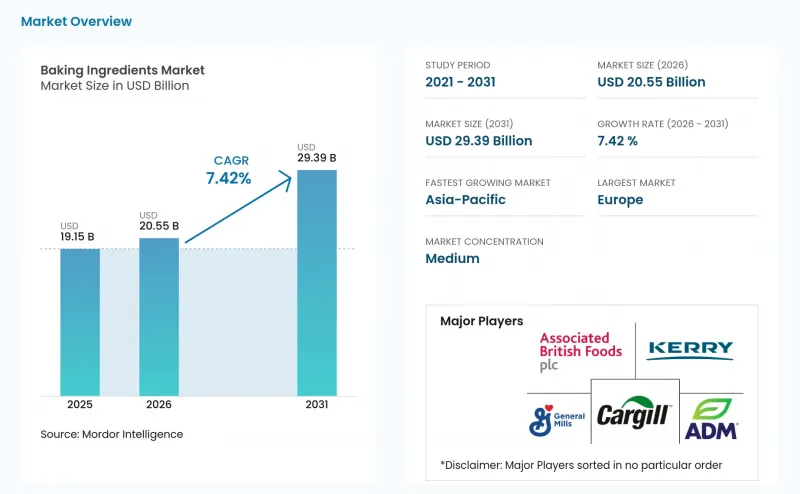
Global Baking Ingredients Market Trends and Insights
Surging Demand for Clean-Label and Natural Bakery Inputs
Ingredient procurement strategies are undergoing a fundamental shift due to rising consumer transparency expectations. Clean-label formulations have transitioned from being a premium offering to a baseline requirement. Reflecting this trend, the European Food Safety Authority (EFSA) issued guidance in 2024 on novel food authorization, emphasizing the demand for recognizable and minimally processed ingredients . Suppliers that invest in natural extraction technologies and sustainable sourcing practices stand to gain competitive advantages in this evolving landscape. Clean-label reformulation has become a commercial requirement for many ingredient suppliers. In April 2025, 2 U.S. federal agencies announced steps to remove petroleum-based synthetic dyes from the food supply by the end of 2026. The American Bakers Association's FD&C Colors Pledge commits more than 90% of its member companies to completing the phaseout by December 31, 2028.
Rising Bread and Pastry Consumption
Bread held 43.27% of revenue in 2025, but demand is shifting toward functional and premium formats. Kerry estimated global bread production at 143 million metric tons per year in March 2026. The company also stated that 10% of production is lost or wasted, creating demand for shelf-life-extending systems. China's baked-food consumption was 7-8 kg per person in 2025, compared with 40 kg in the United States and 25 kg in Japan. This gap supports longer-term volume expansion as Chinese bakery consumption develops. Cakes and pastries are also increasing demand for specialty sweeteners, clean-label fats, and enzyme systems that maintain structure and freshness.
Volatile Wheat and Edible-Oil Prices Squeezing Margins
Raw-material instability is an immediate concern for bakery procurement teams. The FAO Cereal Price Index rose 17.2% year over year in September 2026 and reached its highest level since August 2023. The rise was linked to Black Sea logistics constraints and dry weather in North American winter-wheat areas. The World Bank reported that global edible-oil consumption is expected to exceed supply growth by nearly 3 million metric tons in 2025-26. This puts pressure on fats and shortenings used in pastry, laminated dough, and cookies. Conventional ingredient suppliers face displacement risk when bakeries reformulate, while enzyme systems can help reduce input requirements.
Other drivers and restraints analyzed in the detailed report include:
- Functional Ingredients Targeting Gut Health and High-Protein Needs
- Technological Advancements in Baking Processes
- Stringent Regulations and Food Safety Standards
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Enzymes are the fastest-growing ingredient type, with the baking ingredients market size for enzymes projected to rise at an 8.15% CAGR through 2031. Phospholipase, amylase, and lipase systems can match the performance of synthetic emulsifiers in commercial baking operations. Kerry, Novonesis, and IFF report that multi-enzyme systems can reduce vital wheat gluten use by up to 50% per metric ton of flour. Novonesis has used machine learning to assess 35 commercial flour varieties and identify enzyme parameters that can reduce trials. The baking ingredients market is therefore rewarding solutions that improve processing while helping customers simplify labels.
Emulsifiers held 37.66% of baking ingredients market share in 2025 because they remain widely used as multifunctional aids in industrial bread and pastry production. Their large installed base gives suppliers a meaningful revenue foundation, even as enzyme alternatives gain acceptance. Sugars and sweeteners are seeing greater interest in natural alternatives, although cost and taste replication limit broader use in value products. Fats and shortenings remain essential to laminated pastry and croissant production despite clean-label pressure. Leavening agents are comparatively stable, while enzymes are increasingly used to supplement them in commercial products designed for a longer shelf life. The broader baking ingredients industry is shifting toward systems that perform several functions at once.
Dry or powder form held 64.72% of revenue in 2025 because it works well with automated dosing systems and ambient storage. Powder ingredients also avoid the cold-chain costs associated with many liquid alternatives. Leavening agents, enzyme powder blends, and specialty flour premixes are especially suited to shelf-stable processing. These advantages make powder a practical choice for high-volume baking sites where batch consistency is important. The baking ingredients market continues to rely on powdered formats in regions where cold-chain infrastructure is limited.
Liquid ingredients are forecast to grow at a 7.78% CAGR through 2031, led by enzyme preparations and wet-process sweetener solutions. Liquid inputs can provide more uniform dispersion in continuous-mixing lines than powder metering. This change is most advanced in European and North American industrial bakeries, where continuous mixing has become more common than batch processing. Natural liquid sweeteners, including glucose syrups, inverted sugar syrups, and honey variants, help producers manage texture and water activity in soft sweet goods. Refrigerated logistics and higher storage costs limit liquid adoption in parts of Asia-Pacific, MEA, and South America. Powder's scale advantage will therefore remain important even as liquid systems take a larger role in sophisticated production lines.
Complete Report Scope:
- Ingredient Type
- Flours and Starches
- Sugars and Sweeteners
- Fats and Shortenings
- Emulsifiers
- Leavening Agents
- Enzymes
- Other Ingredient Types
- Form
- Dry/Powder
- Liquid
- End Use
- Commercial
- Household
- Applications
- Bread
- Cakes and Pastries
- Cookies and Biscuits
- Rolls and Pies
- Other Applications
- Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Netherlands
- Poland
- Belgium
- Sweden
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Indonesia
- South Korea
- Thailand
- Singapore
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
- Middle East and Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
- Nigeria
- Egypt
- Morocco
- Turkey
- Rest of Middle East and Africa
- North America
Geography Analysis
In 2024, Europe commands a dominant 33.50% market share, bolstered by its rich bakery traditions, discerning consumer tastes, and regulatory frameworks prioritizing clean-label and sustainable ingredients. The region's mature market landscape not only paves the way for premium product positioning but also encourages the integration of functional ingredients. Suppliers are increasingly investing in application laboratories and technical services, underscoring their commitment to fostering customer innovation. Europe's stringent food safety and environmental standards, often setting the global benchmark, compel suppliers to adapt their formulations. A case in point: the European Food Safety Authority's 2024 re-evaluation of silicon dioxide (E 551) as a food additive, which included updated toxic element limit specifications, underscores the region's vigilance in ingredient safety. Meanwhile, the ramifications of Brexit linger, impacting supply chain logistics and regulatory adherence. In response, suppliers are adopting dual-location strategies, balancing market access with the complexities of heightened administrative demands.
Asia-Pacific is on a rapid ascent, boasting a 7.12% CAGR projected through 2030. This growth is largely attributed to urbanization, increasing disposable incomes, and a westernized diet, all of which are driving up bread and pastry consumption. Efforts to harmonize regulations across ASEAN markets are not only dismantling trade barriers but also aligning food safety standards with global best practices. This alignment presents a golden opportunity for suppliers adept in compliance. Additionally, owing to the rising consumption, the import of baked goods is also increasing in the region. According to the Observatory of Economic Complexity data from 2024, China imported USD 952 million worth of baked goods. As the region cements its status as a manufacturing hub, it enjoys supply chain advantages for global distribution.
North America is witnessing steady growth, thanks to its well-entrenched commercial bakery infrastructure and a discerning household baking segment that fuels demand for premium ingredients. Navigating the region's regulatory maze, which includes FDA updates and state-specific additive restrictions, is no small feat. Yet, this complexity is driving innovation, particularly in clean-label formulations. Looking at Canada, the bakery and tortilla products market is set for a 3.4% nominal sales dip in 2024, but a rebound with a 4.3% volume growth is on the horizon. This uptick is bolstered by declining flour prices, which enhance profitability even as other ingredient categories exert margin pressures. E-commerce is reshaping the landscape, with a surge in home baking ingredient kit sales. Suppliers are seizing this moment, crafting direct-to-consumer strategies that not only sidestep traditional retail channels but also foster brand loyalty and elevate consumer education.
- Cargill, Incorporated
- Archer Daniels Midland Company
- Kerry Group
- Associated British Foods Plc
- Puratos Group
- Lesaffre
- AB Enzymes
- Ingredion Inc.
- DSM-Firmenich
- Tate & Lyle plc
- CSM Ingredients
- Bakels Group
- Novozymes
- International Flavors and Fragrances Inc.
- General Mills Inc.
- Biocatalyst Ltd
- Riken Vitamin Co.
- Jungbunzlauer Suisse AG
- Stern Ingredients
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Demand for Clean-Label and Natural Bakery Inputs
- 4.2.2 Rising Bread and Pastry Consumption
- 4.2.3 Functional Ingredients Targeting Gut-Health and High-Protein Needs
- 4.2.4 Technological Advancements in Baking Processes
- 4.2.5 E-commerce Expansion of Home-Baking Ingredient Kits
- 4.2.6 Upcycling Food Waste into Novel Fibre-Rich Flours
- 4.3 Market Restraints
- 4.3.1 Volatile Wheat and Edible-Oil Prices Squeezing Margins
- 4.3.2 Stringent Regulations and Food Safety Standards
- 4.3.3 Supply Chain Disruptions and Ingredient Shortages
- 4.3.4 Competition from Homemade and Artisanal Bakery Products
- 4.4 Supply Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers/Consumers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 Ingredient Type
- 5.1.1 Flours and Starches
- 5.1.2 Sugars and Sweeteners
- 5.1.3 Fats and Shortenings
- 5.1.4 Emulsifiers
- 5.1.5 Leavening Agents
- 5.1.6 Enzymes
- 5.1.7 Other Ingredient Types
- 5.2 Form
- 5.2.1 Dry/Powder
- 5.2.2 Liquid
- 5.3 End Use
- 5.3.1 Commercial
- 5.3.2 Household
- 5.4 Applications
- 5.4.1 Bread
- 5.4.2 Cakes and Pastries
- 5.4.3 Cookies and Biscuits
- 5.4.4 Rolls and Pies
- 5.4.5 Other Applications
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.1.4 Rest of North America
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 Italy
- 5.5.2.4 France
- 5.5.2.5 Spain
- 5.5.2.6 Netherlands
- 5.5.2.7 Poland
- 5.5.2.8 Belgium
- 5.5.2.9 Sweden
- 5.5.2.10 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 Indonesia
- 5.5.3.6 South Korea
- 5.5.3.7 Thailand
- 5.5.3.8 Singapore
- 5.5.3.9 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Colombia
- 5.5.4.4 Chile
- 5.5.4.5 Peru
- 5.5.4.6 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 South Africa
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 United Arab Emirates
- 5.5.5.4 Nigeria
- 5.5.5.5 Egypt
- 5.5.5.6 Morocco
- 5.5.5.7 Turkey
- 5.5.5.8 Rest of Middle East and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Ranking Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials (if available), Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Cargill, Incorporated
- 6.4.2 Archer Daniels Midland Company
- 6.4.3 Kerry Group
- 6.4.4 Associated British Foods Plc
- 6.4.5 Puratos Group
- 6.4.6 Lesaffre
- 6.4.7 AB Enzymes
- 6.4.8 Ingredion Inc.
- 6.4.9 DSM-Firmenich
- 6.4.10 Tate & Lyle plc
- 6.4.11 CSM Ingredients
- 6.4.12 Bakels Group
- 6.4.13 Novozymes
- 6.4.14 International Flavors and Fragrances Inc.
- 6.4.15 General Mills Inc.
- 6.4.16 Biocatalyst Ltd
- 6.4.17 Riken Vitamin Co.
- 6.4.18 Jungbunzlauer Suisse AG
- 6.4.19 Stern Ingredients
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

